
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
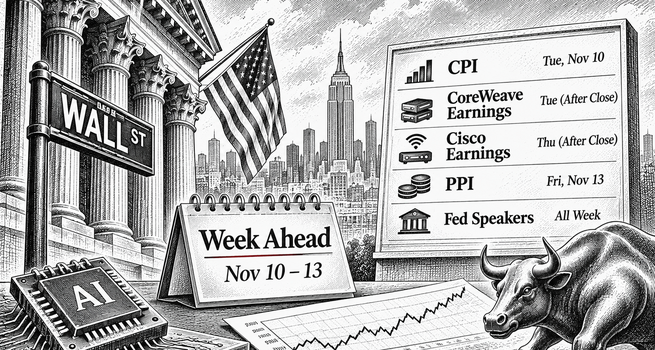
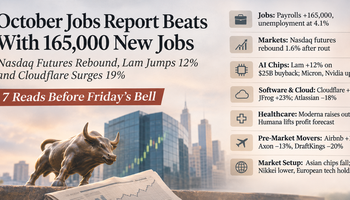
Wall Street enters the heart of the week on firmer footing after Monday's rally, in which the Dow gained 1,104 points, or 2.2%, the S&P 500 rose about 2.4% and the Nasdaq Composite climbed 2.7%, clawing back part of last week's rout triggered by the Democrats' sweep of Congress in the midterm elections. October's consumer price index, released before Tuesday's open, is the week's single most important event: headline CPI is forecast to rise 0.3% month-on-month after September's 0.6%, with core CPI expected to slow to 0.2% from 0.3%, and no year-on-year figures will be published because the 2025 Government Shutdown left the comparable data uncollected.
The AI trade, which drove last week's selling, faces fresh tests from CoreWeave after Tuesday's close and from Cisco and Applied Materials on Thursday evening, while Friday's producer price index, forecast to moderate to 0.4% from 1.3%, completes the Inflation picture. More than a dozen Federal Reserve appearances through the week will be parsed for clues ahead of the December 8 to 9 meeting, where futures price a rate hike with roughly 80% probability after Friday's strong jobs report. The political overhang from the midterms, and what a Democratic Congress means for the data-center buildout, remains the backdrop variable most capable of reigniting volatility.
Major Ex-Dividend Dates This Week
Day |
Company |
Ticker |
Dividend |
Yield |
|---|---|---|---|---|
|
Tuesday, Nov 10 |
Ford Motor |
$0.15 |
4.82% |
|
|
Tuesday, Nov 10 |
Target |
$1.16 |
2.93% |
|
|
Tuesday, Nov 10 |
IBM |
$1.69 |
2.76% |
|
|
Tuesday, Nov 10 |
American Electric Power |
$0.97 |
3.07% |
|
|
Thursday, Nov 12 |
Apple |
$0.27 |
0.32% |
|
|
Thursday, Nov 12 |
TJX Companies |
$0.48 |
1.42% |
|
|
Thursday, Nov 12 |
D.R. Horton |
$0.50 |
1.31% |
|
|
Thursday, Nov 12 |
Diamondback Energy |
$1.18 |
2.64% |
|
|
Friday, Nov 13 |
Duke Energy |
$1.09 |
3.40% |
|
|
Friday, Nov 13 |
J.M. Smucker |
$1.12 |
3.43% |
|
|
Friday, Nov 13 |
Truist Financial |
$0.52 |
4.21% |
Monday, November 9 (Recap)
Market
Technology led a broad rebound after a week in which the Nasdaq Composite closed nearly 12% below its October 6 record, confirming a correction, and the S&P 500 technology sector and the Philadelphia Semiconductor index posted their steepest one-day falls in more than six years. Falling oil prices helped, with West Texas Intermediate settling down more than 4% and Brent more than 5%. Nvidia (NASDAQ:NVDA) sat out the rally, sliding 4% after CEO Jensen Huang acknowledged a relationship with a woman whom U.S. intelligence officials, according to The New York Times, identify as an agent of China's Ministry of State Security; the company's board has launched an independent internal investigation.
Earnings
Before the open, Constellation Energy (NASDAQ:CEG) reported Earnings of $5.06 a share against an estimate of $3.90, and NRG Energy (NYSE:NRG) delivered $4.68 against $3.35, with both power producers also beating on revenue. KKR (NYSE:KKR) and Ferguson (NYSE:FERG) also beat earnings forecasts. After the close, Occidental Petroleum (NYSE:OXY) beat expectations, Rocket Lab (NASDAQ:RKLB) posted record Revenue of $268 million with its Backlog rising to about $3.6 billion, and Take-Two Interactive (NASDAQ:TTWO) kept Grand Theft Auto VI on track for its November 19 launch.
Economic Data
Wholesale trade for September rose 0.7%, accelerating from 0.5% in August, while the New York Fed's survey showed one-year consumer inflation expectations holding steady at 3.9% in October.
Federal Reserve
Chicago Fed President Austan Goolsbee and Richmond Fed President Tom Barkin opened a busy week of Fed commentary.
Tuesday, November 10
Earnings
TransDigm (NYSE:TDG), Venture Global (NYSE:VG), On Holding (NYSE:ONON) and D-Wave Quantum (NYSE:QBTS) report before the open. The session's pivotal report comes after the close from CoreWeave (NASDAQ:CRWV), the AI cloud provider at the centre of concerns over how the AI buildout is being financed, whose Market Value has shrunk to about $27 billion after weeks of heavy selling; analysts expect a loss of $1.27 a share on revenue of $3.54 billion. Any sign that the company can finance and complete its data-center projects despite the new political climate would ease some of the anxiety that has hung over the sector. Rigetti Computing (NASDAQ:RGTI), Mercury Systems (NASDAQ:MRCY) and Firefly Aerospace (NASDAQ:FLY) also report after the close.
Economic Data
October CPI lands at 8:30 am ET. Headline CPI is forecast to rise 0.3% month-on-month, slowing from 0.6% in September, and core CPI 0.2%, down from 0.3%. With no year-on-year figures published this month, the monthly changes and their components carry more weight than usual. Economists expect a cooling in shelter costs, notably owners' equivalent rent and lodging, and steadier diesel prices to ease pressure on energy-intensive goods. A soft core print would be welcome after two months of upside surprises, but it would not by itself derail expectations of a December hike. Earlier, the NFIB Index of Small Business Optimism for October, prior at 97.9 and forecast at 98.1, is released at 6:00 am ET, and the New York Fed's Quarterly Report on household Debt and Credit follows at 11:00 am ET.
Federal Reserve
Tuesday is the week's busiest day for Fed commentary. Governor Christopher Waller speaks in England at 4:00 am ET, ahead of the CPI release. Dallas Fed President Lorie Logan follows at 10:50 am ET and Kansas City Fed President Jeffrey Schmid at 1:30 pm ET. Vice Chair for Supervision Michelle Bowman appears at a Council on Foreign Relations event at 3:30 pm ET and again at 6:30 pm ET, while Philadelphia Fed President Anna Paulson speaks at 4:30 pm ET and 6:30 pm ET. Together, the appearances give officials an early opportunity to react to the CPI data.
Wednesday, November 11
Earnings
The earnings calendar is thin. Corteva (NYSE:CTVA), Tetra Tech (NASDAQ:TTEK) and EnerSys (NYSE:ENS) report after the close.
Market
Bond markets are closed for Veterans Day, while Equity markets trade as normal. With no economic reports or Fed appearances scheduled, stocks will take their cue from the market's digestion of Tuesday's CPI print and CoreWeave's results.
Thursday, November 12
Earnings
Brookfield Corporation (NYSE:BN) and Nebius Group (NASDAQ:NBIS) report before the open, with Nebius, like CoreWeave, a bellwether for AI cloud capacity. The evening brings the week's most consequential technology results: Cisco Systems (NASDAQ:CSCO), expected to earn $1.32 a share on revenue of $18.11 billion, will be read for networking Demand tied to AI data centers, while Applied Materials (NASDAQ:AMAT), expected to earn $4.06 a share on revenue of $10.30 billion, offers a direct gauge of chip-equipment orders after the semiconductor index's sharp drawdown. Nu Holdings (NYSE:NU) and Cerebras Systems (NASDAQ:CBRS) also report after the close, and Ross Stores (NASDAQ:ROST), Williams-Sonoma (NYSE:WSM) and Macy's (NYSE:M) add a retail read ahead of the holiday season.
Economic Data
Weekly jobless claims for the week ending November 7, prior at 189,000 and forecast at 195,000, land at 8:30 am ET, with claims still consistent with the tight labour market that last week's strong jobs report confirmed. Existing home sales for October, prior at 4.0 million and forecast to slip to 3.8 million, follow at 10:00 am ET, with elevated Mortgage rates continuing to cap activity. The monthly Treasury balance for October, prior at -$27 billion, closes the day's releases at 2:00 pm ET.
Federal Reserve
Cleveland Fed President Beth Hammack holds a moderated conversation with Ohio State University students at 9:00 am ET, and Fed Governor Michael Barr speaks at a Yale Program on Financial Stability event at 10:00 am ET. San Francisco Fed President Mary Daly follows at 1:10 pm ET, and New York Fed President John Williams, a permanent voter on the rate-setting committee, joins a panel discussion at 6:30 pm ET.
Friday, November 13
Earnings
The corporate calendar is quiet, with only smaller companies reporting, leaving the session's direction to the morning's inflation data.
Economic Data
October PPI lands at 8:30 am ET. Headline producer prices are forecast to rise 0.4% month-on-month, down from 1.3% in September, and core PPI, which excludes food and energy, 0.3%, down from 0.7%. On an annual basis, producer prices are forecast at 6.6%, up from 6.3%, a reminder of how far Upstream cost pressures have built this year. Because components such as airfares and medical services feed directly into PCE, the Fed's preferred inflation gauge, a hot PPI print following a tame CPI would complicate the inflation picture heading into December.
Federal Reserve
San Francisco Fed President Mary Daly speaks at a University of Nevada event at 12:00 pm ET, and Fed Vice Chair Philip Jefferson closes the week's commentary at a UC San Diego Economics department event at 7:00 pm ET.
Geopolitical Backdrop
The political fallout from last week's midterms remains the dominant variable for markets. Democrats won control of both chambers of Congress as well as several governors' races in data-center-heavy states such as Texas, after a campaign in which public backlash over the environmental and local impact of data centers featured prominently. Investors are weighing whether the result will slow approvals, raise costs or tighten regulation for the AI buildout, an overhang that strategists expect to linger until the scale of any slowdown becomes clearer. Easing oil prices, which fell sharply on Monday, offer some relief on the inflation front.
Overseas, Asian markets rallied strongly on Tuesday, led by a 4.3% jump in South Korea's Kospi and a 2.9% gain in Japan's Nikkei 225. China's inflation and trade figures, Japan's producer prices, and inflation data from India, Brazil and Mexico provide a global read on price pressures, while UK third-quarter GDP on Thursday, trade figures from Germany and the UK, and GDP releases from Russia, Poland and the Philippines round out the international calendar. In Brazil, markets will also watch the central bank's policy minutes alongside retail sales and business sentiment data.
The Week in Context
Two threads will determine how the week is ultimately read. First, whether Monday's rebound marks the start of a recovery in the AI trade or merely a pause in the selling. Technology has underperformed the S&P 500 over the past month by the widest Margin since 2002, and strategists have described something close to a buyers' strike in the sector. Results from CoreWeave, Cisco and Applied Materials that show AI demand and financing holding up despite the new political landscape would support the case for a durable recovery, while disappointments would reinforce fears that the buildout is entering a slower phase.
Second, whether Tuesday's CPI and Friday's PPI confirm that inflation is moderating. With the Fed having hiked in September, held in October and now priced for a further move in December, and about two more quarter-point increases expected in total for this cycle, a hot core reading would add yet more tightening to a market already struggling to absorb it, while a soft print would offer some relief. With the S&P 500 still up nearly 8% for 2026 and Volatility elevated, this week will go a long way toward deciding whether the post-midterm selloff was a correction to buy or the start of something deeper.

 Nov 10, 2026
 Please wait processing your request...