
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
index Update
US equities closed higher on Friday as weak employment data reduced expectations for a September Fed rate hike. The S&P 500 gained 0.6% to a record 7,758, the Nasdaq advanced 1.3%, and the Dow added 152 points. Lower Treasury yields supported sentiment, while SpaceX surged 15.8% and Palantir climbed 10.3%; Sandisk, Western Digital and Berkshire Hathaway traded lower.
Market Movers
Among the top-performing stocks of the session MasterBeef Group. surged 137.87%, while Avita Medical, Inc. rallied 63.58%. On the losing side, PN Smart Energy Limited. fell 61.28%, while CVRx, Inc. declined 59.76%, making them the weakest performers during the trading day.
Commodities Update
WTI crude rose to around USD 79 per barrel and Brent climbed above USD 84 on Monday, extending recent gains as uncertainty over reopening the Strait of Hormuz sustained Supply concerns. Negotiations between Iran and Oman remain unresolved, while conflicting US-Iran signals have clouded the outlook for an agreement. Prices also gained support from reported attacks on Saudi Arabia’s Jazan refinery and an ADNOC-operated tanker in the Strait.
Gold held above USD 4,300 per ounce and silver traded near USD 64 on Monday after gaining more than 7% and 10%, respectively, last week. Precious metals remained supported by an unexpected 23,000 decline in US payrolls in July, which lowered the probability of a September Federal Reserve rate hike to around 44% from 67% a week earlier, alongside persistent geopolitical uncertainty surrounding the Strait of Hormuz.
Macro Updates
Dollar Remains Pressured by Weak US Labour Data
The dollar index hovered near 99.6 on Monday after weak July payrolls and downward revisions signalled a deteriorating US labour market, reducing the probability of a September Fed rate hike to around 44%. Investors now await key Inflation data while monitoring persistent US-Iran tensions and uncertainty surrounding a potential agreement.
Bonds Commentary
The US 10-year Treasury Yield held near 4.66% on Monday but remained under pressure after weak July Payroll data and downward revisions signalled a softening labour market, reducing the probability of a September Fed rate hike to around 44%. Investors now await key inflation data while monitoring continued US-Iran tensions and uncertainty over a potential agreement.
Futures Update
US stock futures edged lower on Monday as rising oil prices and fading hopes for reopening the Strait of Hormuz renewed inflation concerns. Investors also awaited key US inflation data after weak July employment figures reduced expectations for a September Fed rate hike, while upcoming Earnings from Applied Materials, Cisco and CoreWeave remained in focus.
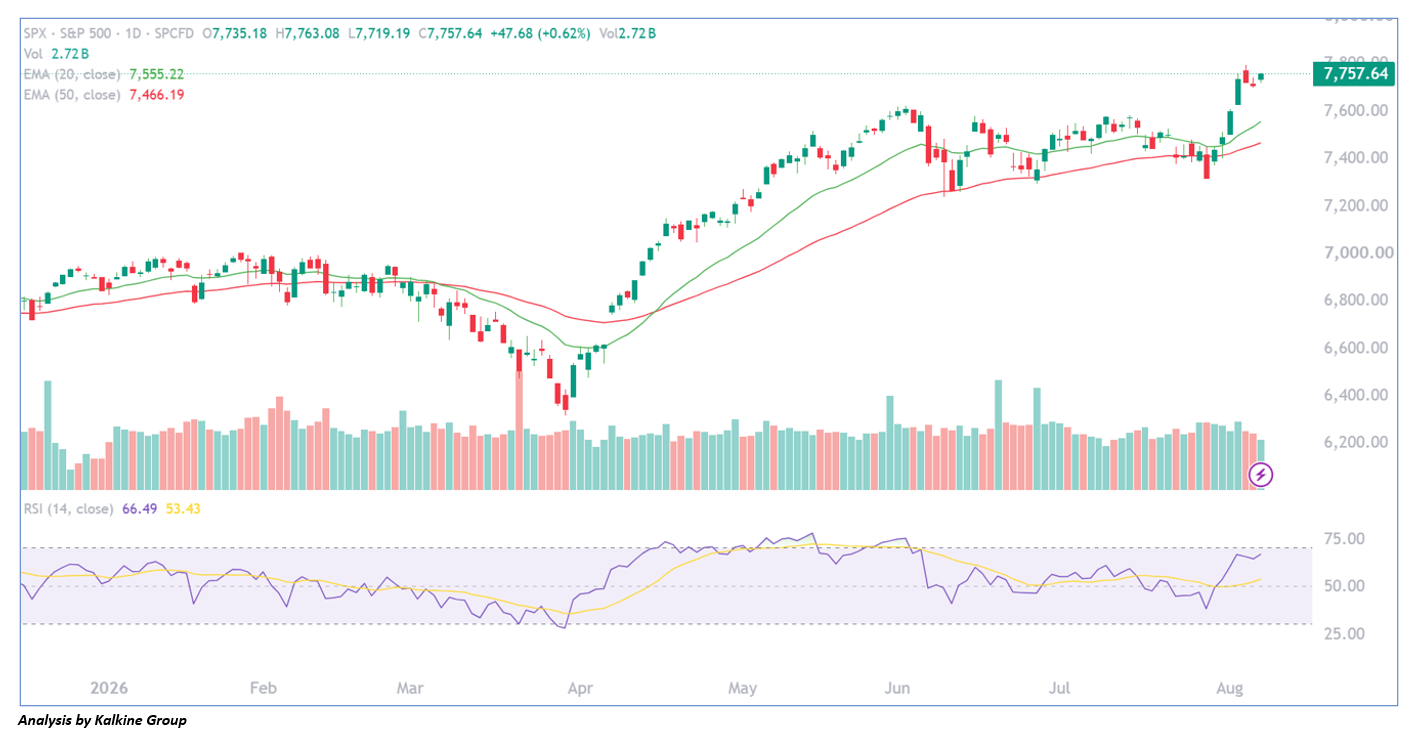
Stocks extended their early gains on Friday and remained firmly in positive territory throughout the session, with all major averages closing higher and the S&P 500 marking another record closing high. The index retains a bullish intraday bias, trading comfortably above its 21-day EMA at 7,555 and 50-day EMA at 7,466, highlighting continued strength in the underlying trend. With the RSI at 66.49, momentum remains positive but is nearing overbought territory, warranting some caution following the recent advance. As long as the S&P 500 holds above the 7,700–7,720 support zone, the bullish setup remains intact, with further upside toward 7,800–7,850 possible in the near term.

 Nov 05, 2026



 Please wait processing your request...