
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks began November mostly lower as technology and energy shares weighed on the market. The S&P 500 fell 0.5% and the Nasdaq lost 1.1%, while the Dow gained 214 points. Oracle dropped 8.8% after announcing a USD 10 billion share offering and plans to raise a similar amount through debt. AMD fell 7.5%, Micron lost 5.8%, and ExxonMobil declined 4% as oil prices eased on hopes of renewed US–Iran talks. Walmart rose 3.4% and Amazon gained 2.2% as investors awaited the US midterm elections and labour market data.
Market Movers
Among the top-performing stocks of the session VCI Global Limited surged 168.40%, while ClearOne, Inc. rallied 65.69%. On the losing side, AI OKTO CORP. fell 47.75%, while SVRN, Inc. declined 39.67%, making them the weakest performers during the trading day.
Commodities Update
US crude rose above USD 98 per barrel and Brent exceeded USD 106 on Tuesday as reports of a US strike on Iran’s Qeshm Island renewed concerns over Supply disruptions. Both benchmarks recovered part of Monday’s losses, when signs of progress in US–Iran talks pushed US crude down more than 6% and Brent more than 7%. Negotiations continued as rising energy costs put pressure on the Trump administration during the US midterm elections.
Gold fell toward USD 3,900 per ounce and silver toward USD 49 per ounce on Tuesday, reversing the previous session’s gains as reports of a US strike on Iran’s Qeshm Island lifted oil prices and renewed Inflation concerns. Selling in technology and AI stocks spread to precious metals as investors liquidated holdings across markets. Investors also watched US–Iran talks for signs of progress and the US midterm elections for their impact on control of Congress.
Macro Updates
US Economic Optimism Reaches Highest Level Since February
The RealClearMarkets/TIPP Economic Optimism index rose to 48.5 in November 2026 from 46.8 in October, exceeding the forecast of 46.2. All three components improved. The six-month economic outlook saw the largest gain, rising to 45.3 from 42.7, while the personal financial outlook increased to 54.1 from 53.4 and confidence in federal economic policy rose to 46.0 from 44.4.
US Logistics Costs Rise at Fastest Pace Since March 2022 as Retailers Stock Up
The US Logistics Managers’ Index rose to 70.7 in October 2026 from 70.2 in September, marking the second-fastest pace of sector growth in four years. Retailers built inventories ahead of holiday sales, lifting the inventory levels index to 66.9 from 58.9. Warehousing and transportation capacity continued to contract. Although transportation prices rose more slowly, faster increases in inventory costs and warehousing prices pushed the aggregate logistics costs index to 257.5, its highest reading since March 2022.
US Dollar Steadies as Investors Await Midterm Results and Jobs Data
The US Dollar Index steadied near 101.8 on Tuesday after a volatile Monday. Prediction markets put the odds of Democrats gaining control of the Senate at 74%, while Interest Rate markets priced in a roughly 73% chance of a December Fed rate hike following October’s pause. Investors awaited the week’s US jobs report for clues on the rate outlook. Signs of progress in US–Iran talks had also weighed on oil prices and eased Demand for the dollar as a safe haven.
Bonds Commentary
The US 10-year Treasury Yield edged up to 4.94% on Tuesday after falling 3 basis points on Monday, as investors awaited the midterm election results and the JOLTS Job openings report. Oil prices also rebounded following reports of a US strike on Iran’s Qeshm Island. The Treasury lowered its fourth-quarter borrowing estimate by USD 10 billion to USD 618 billion because it began the quarter with more cash than expected. Excluding that cash cushion, projected borrowing needs were USD 24 billion above the August estimate.
Futures Update
US stock futures were mixed on Tuesday. Dow futures fell about 400 points and S&P 500 futures slipped 0.1%, while Nasdaq 100 futures rose 0.3% after the index entered a technical correction. Investors remained cautious as US midterm voting began and oil rebounded following reports of a US strike on Iran’s Qeshm Island. In premarket trading, Apple fell 3.9% on a weak Margin outlook, Palantir lost 3.8% despite stronger-than-expected earnings, and Pfizer slipped 0.6% after reporting results. AMD and Super Micro Computer gained 2% and 1.5%, respectively, ahead of their Earnings releases.
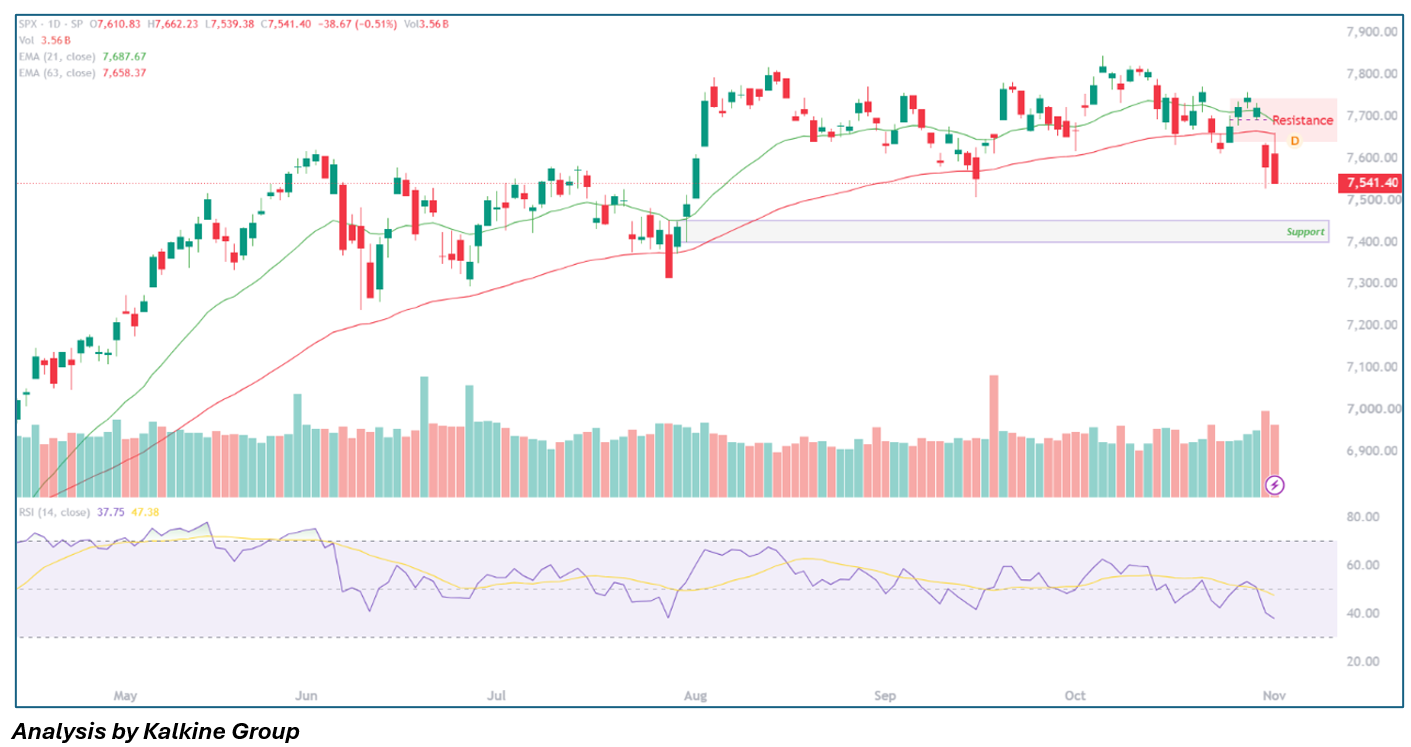
Major U.S. indices reversed early-session gains on Monday, dragged into negative territory by midday selling pressure across tech and benchmark equities. The S&P 500 Index (SPX) fell -0.51% (-38.67 pts) to 7,541.40 on 3.56B shares, closing near its intraday trough of 7,539.38 after a failed retest of overhead resistance at 7,680–7,730. With price pinned below both the 63-day EMA (7,658.37) and 21-day EMA (7,687.67) and the 14-day RSI weakening to 37.75, failure to hold 7,539.38 threatens an extension toward structural support at 7,400–7,450, while immediate resistance remains at 7,600.00–7,658.37.


 Nov 02, 2026



 Please wait processing your request...