
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
The S&P 500 rose 0.4% and the Nasdaq gained 0.7% on Tuesday as AI-related stocks rebounded, while the Dow fell 197 points. Nvidia climbed 2.3% after four straight declines, AMD gained 3.6% ahead of earnings, and Oracle rallied 6%. Apple fell 1.9% after warning that higher memory chip costs could squeeze holiday-quarter margins, while Palantir slipped 1.6% as growth in US commercial contract value slowed. Investors awaited midterm election results, with Democrats favoured to regain the House and control of the Senate still uncertain.
Market Movers
Among the top-performing stocks of the session Chanson International Holding surged 241.24%, while Rising Dragon Acquisition Corp. rallied 121.57%. On the losing side, Supernus Pharmaceuticals, Inc. fell 32.85%, while Roze AI Inc. declined 32.81%, making them the weakest performers during the trading day.
Commodities Update
Brent crude rose above USD 104 per barrel and US crude climbed towards USD 97 on Wednesday as uncertainty over US–Iran peace talks prompted a partial rebound. Both sides were reviewing new proposals from mediators, though Iran expressed dissatisfaction with Washington’s response. Limited US strikes on Iranian missile systems earlier in the week appeared to signal little appetite for a broader escalation. Brent remained down about 8% for the week and US crude more than 7%, as hopes for a diplomatic breakthrough and signs of recovering Middle Eastern crude exports eased Supply concerns.
Gold rose more than 2% to trade above USD 4,000 per ounce on Wednesday, while silver gained more than 4% to approach USD 52 per ounce. Democratic gains in the US midterm elections raised expectations of political gridlock and reduced the perceived scope for fiscal expansion. The US dollar fell to a four-week low and Treasury yields declined, lifting Demand for both metals. US–Iran talks remained unresolved, and investors awaited Friday’s US nonfarm payrolls report, with markets pricing in a 79% chance of a Federal Reserve rate hike in December.
Macro Updates
US Dollar index Falls to Five-Week Low as Democrats Lead in Early Polls
The US Dollar Index fell below 101.5 on Wednesday as early midterm polls pointed to a possible Democratic majority in both chambers of Congress. Investors weighed whether political gridlock could curb government spending and whether tighter AI regulation and corporate oversight could slow growth. With US–Iran talks unresolved, markets also monitored the risk of renewed US strikes and awaited the US jobs report later in the week for clues on the Federal Reserve’s rate outlook.
US Crude Inventories Fall 5.27 Million Barrels Against Expectations for a Build
US crude inventories fell by 5.27 million barrels in the week ended October 30, compared with an expected increase of 2.1 million barrels and a draw of 2.03 million barrels the previous week. Gasoline stocks rose by 1.43 million barrels, distillate stocks fell by 270,000 barrels, and crude stocks at Cushing increased by 511,000 barrels. A 400,000-barrel release reduced the Strategic Petroleum Reserve to 282.2 million barrels. In the week ended October 23, US crude production rose to 13.99 million barrels per day from 13.27 million a week earlier.
Bonds Commentary
The US 10-year Treasury Yield fell to 4.93% on Wednesday as Democratic gains in Congress reduced expectations for further tax cuts and spending, easing concerns about federal borrowing. Prospects for tighter AI regulation also weighed on growth expectations, while the market-implied probability of a 25-basis-point Fed rate hike in December fell to 77% from 84% a week earlier. The Treasury lowered its fourth-quarter borrowing estimate by USD 10 billion to USD 618 billion, reflecting a larger opening cash balance. Excluding that cash cushion, borrowing needs were USD 24 billion above the August estimate.
Futures Update
US stock futures were mixed on Wednesday after Democrats won control of both chambers of Congress. S&P 500 futures fell 0.1% and Nasdaq 100 futures slipped 0.3%, while Dow futures rose about 100 points. Investors weighed the prospect of tighter AI regulation and less room for tax cuts or higher government spending. Major technology stocks traded lower before the open, with Microsoft and Amazon each down 0.9%, while AMD gained more than 5% after Earnings and Revenue beat expectations.
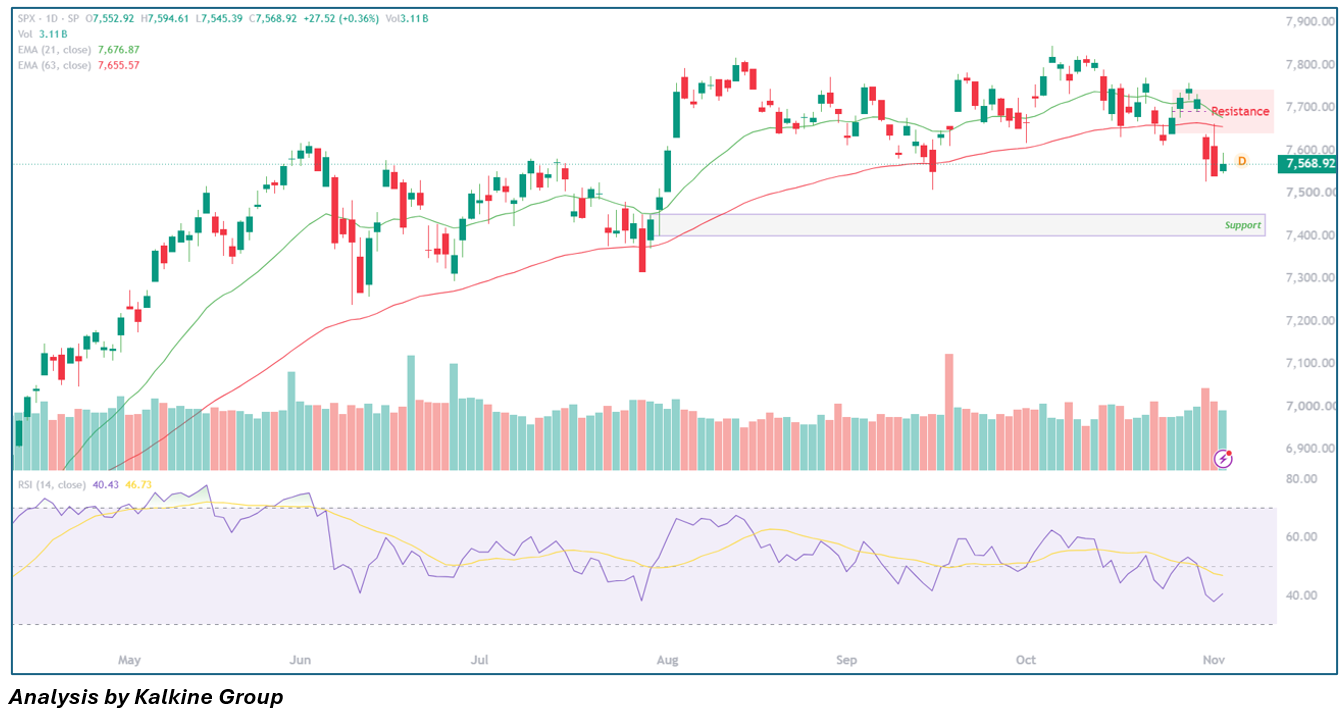
U.S. stocks diverged on Tuesday, with tech attempting to stabilize while blue chips faced fresh selling. After Monday’s sharp sell-off, the S&P 500 rose 0.36% to 7,568.92, holding above an early low of 7,545.39, but the bounce looks fragile: the index remains below its short-term averages, with resistance clustered at the 63-day EMA (7,655.57), the 21-day EMA (7,676.87), and the 7,720 ceiling. Momentum also favors sellers, as the 14-period RSI at 40.43 sits below its signal line at 46.73, pointing to weak buying strength. Holding above 7,540-7,545 keeps a retest of 7,600-7,620 possible, while a break below 7,545 could send the index toward the 7,400-7,450 support zone, and downside risk eases meaningfully only if it reclaims 7,655-7,680.


 Nov 02, 2026




 Please wait processing your request...