
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stock indices closed higher on Wednesday, led by a rebound in heavyweight technology and financial stocks. The S&P 500 gained 0.5%, the Nasdaq rose 0.2% and the Dow added 295 points. Nvidia advanced on Acquisition reports, Alphabet benefited from a favourable antitrust ruling and Dell surged following strong results and upgraded guidance, while Palo Alto Networks and Broadcom declined.
Market Movers
Among the top-performing stocks of the session bioAffinity Technologies, Inc. surged 47.95%, while Focus Universal Inc. rallied 33.57%. On the losing side, Wetour Robotics Limited, Inc. fell 33.84%, while Apimeds Pharmaceuticals US, Inc. declined 25.71%, making them the weakest performers during the trading day.
Commodities Update
Gold climbed above USD 4,400 per ounce and silver approached USD 66 as a weaker dollar, declining Treasury yields, easing Inflation pressures and slower US private employment supported precious metals. Gains were partly tempered by expectations of a potential Fed rate hike, while easing concerns over a prolonged US-Iran conflict and moderating oil prices provided additional support.
WTI and Brent Crude remained volatile near one-month highs of USD 91 and USD 96 per barrel, respectively, as renewed US-Iran hostilities heightened concerns over oil flows through the Strait of Hormuz. However, Trump’s expectation of a short-lived conflict, continued vessel traffic through the strait and rising Iraqi exports helped ease immediate Supply disruption fears.
Macro Updates
US Job Cuts Rise in August but Remain Below 2025 Levels
US employers announced 52,881 job cuts in August 2026, up from 33,429 in July but 38.5% lower year-over-year. Consumer products recorded the most cuts, followed by food, technology, financial and communication companies, with restructuring the leading reason. Year-to-date layoffs reached 529,914, down 41% from 2025, although technology remained the most affected sector.
Dollar Weakens as Yen Rally and Easing Inflation Weigh
The US dollar index declined to around 99.5 as a sharp yen rally, cooling inflation signals, weaker private employment growth and easing oil prices pressured the greenback. However, expectations of a possible Fed rate hike limited the decline, with investors awaiting weekly jobless claims and August Payroll data for further policy guidance.
Bonds Commentary
The 10-year US Treasury Yield eased to around 4.78% from three-year highs as cooling inflation signals, weaker private employment growth and moderating oil prices reduced upward pressure. However, expectations of a potential Fed rate hike continued to limit the decline, with investors awaiting jobless claims and August payroll data for further policy cues.
Futures Update
US Equity futures were mixed on Thursday as investors assessed the impact of higher interest rates on corporate performance. Dow futures rose 0.2%, the S&P 500 remained flat and Nasdaq 100 futures fell 0.6%, pressured by declines in Broadcom and other AI-chip stocks. Hewlett Packard Enterprise also dropped after disappointing results, while Citi, Tesla and Eli Lilly gained around 1%.
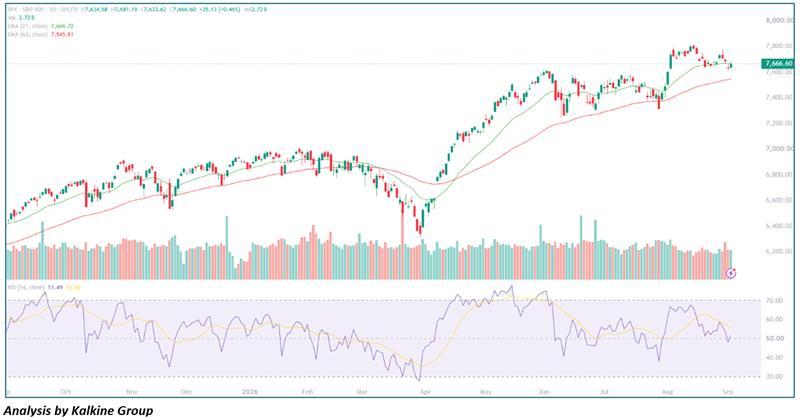
Stocks moved broadly higher during Wednesday’s session, recovering from the weakness seen over the previous few sessions. The major averages rebounded into positive territory, although the pace of buying remained relatively subdued. The S&P 500 is trading near 7,666.60, hovering around its 21-day EMA of 7,666.72 while remaining well above the 63-day EMA of 7,545.81, keeping the broader trend constructive. However, the RSI at 51.49 has slipped below its signal line, suggesting that near-term momentum is weakening. Immediate resistance is placed around 7,680–7,700, followed by 7,750–7,800, while support is seen at 7,635–7,600. A decisive move above 7,700 could strengthen the upside momentum, whereas a break below 7,635 could trigger further profit-taking toward 7,600. Overall, the intraday outlook remains neutral to slightly bullish, with the index likely to stay range-bound unless either key level is decisively breached.

 Nov 03, 2026





 Please wait processing your request...