
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks closed mixed on Wednesday, with the S&P 500 gaining 0.2% and the Dow rising 120 points, while the Nasdaq slipped 0.2%. Treasury measures to curb long-term borrowing costs and improve dollar Liquidity supported equities, although the Fed minutes indicated that some policymakers still favoured rate hikes. Pharmaceutical stocks surged following positive melanoma Vaccine trial results from Merck and Moderna, while weak OpenAI results pressured chipmakers such as AMD and Intel. Retail stocks were mixed following Earnings reports from TJX, Target and Lowe’s.
Market Movers
Among the top-performing stocks of the session Moderna, Inc. surged 176.97%, while ZeroStack Corp. rallied 169.55%. On the losing side, Profusa, Inc. fell 50.62%, while IP Strategy Holdings, Inc. declined 46.38%, making them the weakest performers during the trading day.
Commodities Update
Crude oil prices rose more than 2% on Thursday, with WTI reaching around $86.70 per barrel and Brent climbing to $93.80, their highest levels since July 24. Prices advanced after President Donald Trump announced broad economic measures targeting Iran’s financial, commercial and shipping networks to intensify pressure over the conflict, its nuclear programme and the Strait of Hormuz. Supply concerns remain elevated amid the US blockade of Iranian ports and heightened shipping risks, although oil from other Gulf producers continues to pass through Hormuz. Tensions escalated further after the UAE suspended economic ties with Iran over alleged missile attacks.
Gold eased below $4,500 an ounce and silver traded near $67 on Thursday, retaining most of their previous-session gains of more than 4% and nearly 6%, respectively. Precious metals remained supported by a sharp decline in US Treasury yields after the Treasury Department announced plans to more than double repurchases of long-term government debt. Lower yields reduced the Opportunity cost of holding non-interest-bearing assets, although hawkish signals from the Federal Reserve and persistent Inflation risks linked to US-Iran tensions tempered sentiment.
Macro Updates
Dollar index Holds Near Three-Month Low
The US Dollar Index held around 98.8 on Thursday, remaining near a three-month low after the Treasury expanded its long-term bond buyback programme to improve liquidity and contain borrowing costs. Although some Federal Reserve policymakers supported raising interest rates this year to curb inflation, persistent US-Iran tensions and related inflation risks kept the currency under pressure.
Bonds Commentary
Long-term US Treasury yields remained sharply lower after the Treasury Department announced plans to at least double Buybacks of securities with maturities between 10 and 30 years to improve market liquidity. The 10-year yield traded near 4.64%, down from a 20-month high of 4.75%, while the 30-year yield fell below 5.2% after reaching a 19-year high of 5.34%. However, persistent inflation concerns, rising fiscal deficits, heavy AI-related Debt issuance and the possibility of further Federal Reserve rate hikes continued to pressure the bond market.
Futures Update
US Equity futures edged lower on Thursday, with S&P 500, Dow and Nasdaq 100 contracts falling as much as 0.5%, as Treasury yields rebounded amid concerns over inflation and abundant liquidity. Higher energy prices and escalating US-Iran tensions further pressured sentiment, while banks and AI-related stocks weakened. Walmart shares also dropped more than 6% after its second-quarter sales missed expectations.
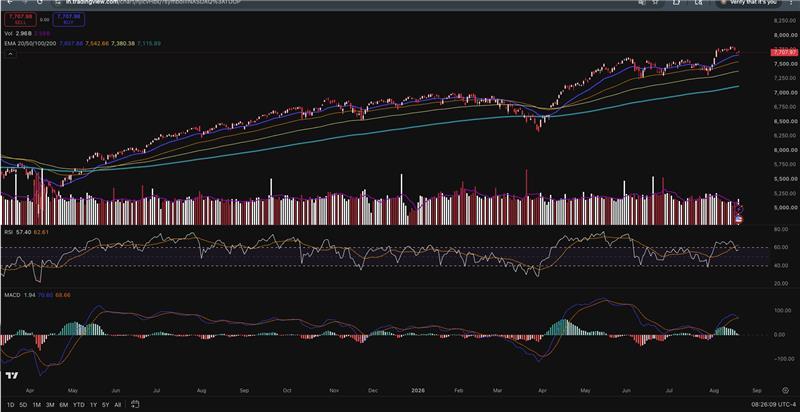
The S&P 500 remains in a bullish daily setup, trading around 7,708 and holding above its rising 20-, 50-, 100- and 200-day EMAs. However, the index is consolidating near its recent highs, suggesting some profit-taking after the strong rally. RSI at 57 indicates positive momentum without entering overbought territory, while the MACD remains bullish, supporting the broader uptrend.
On the upside, 7,745–7,750 is the immediate resistance zone, followed by 7,790–7,820, which represents the recent high area. A decisive breakout above 7,820 could open the path toward 7,900–8,000.
On the downside, 7,650–7,670 is the immediate support zone, followed by 7,530–7,550 around the 50-day EMA. A deeper correction could find major support near 7,380–7,400.
Overall view: Bullish above 7,650; breakout above 7,820 would strengthen the uptrend.

 Nov 05, 2026



 Please wait processing your request...