
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks ended mixed on Monday as weakness in chipmakers outweighed gains in broader sectors. The S&P 500 fell 0.3% and the Nasdaq declined 1%, while the Dow gained 140 points. Nvidia, Broadcom, Micron, AMD and Intel retreated amid concerns over AI infrastructure returns and ahead of Nvidia’s earnings. Meanwhile, elevated energy prices sustained Inflation concerns, while Visa and Mastercard rallied more than 3%.
Market Movers
Among the top-performing stocks of the session Expion360 Inc. surged 80.49%, while Sadot Group Inc. rallied 75.72%. On the losing side, First Breach Inc. fell 48,62%, while T3 Defense Inc. declined 46.58%, making them the weakest performers during the trading day.
Commodities Update
Crude oil prices fell 3% on Tuesday, with WTI near USD 82.5 per barrel and Brent around USD 89.5, extending the previous session’s 2.4% decline. Prices weakened as signs of potential diplomatic progress between Iran and the US eased supply-disruption concerns, while Washington’s latest pressure measures were less severe than expected. However, uncertainty remains over the impact on oil flows through the Strait of Hormuz and possible tensions with China, Iran’s largest crude buyer.
Gold held near USD 4,650 per ounce, close to a three-month high, while silver eased toward USD 68 but remained near a two-month peak. Both metals were supported by the Debasement trade after the US Treasury expanded long-dated Debt buybacks, reviving concerns over fiscal sustainability, persistent inflation and dollar weakness. Rising gold ETF inflows strengthened Investment demand, while silver also benefited from robust industrial consumption across solar energy, electric vehicles and AI data-centre infrastructure.
Macro Updates
Dollar Stabilises on Safe-Haven Demand Amid Fiscal Concerns
The US dollar index held near 99, supported by safe-haven demand following Washington’s plans to impose sanctions on countries trading with Iran. However, the greenback remained close to three-month lows as expanded Treasury debt Buybacks renewed concerns over US fiscal sustainability and long-term dollar weakness. Investors now await PCE inflation data and Fed Chair Kevin Warsh’s Jackson Hole speech for Monetary Policy signals.
Bonds Commentary
The 10-year US Treasury Yield held near 4.7% as investors assessed the expanded debt buyback programme and reports that it could be funded through the government’s cash account. Concerns persisted that the measure may provide only temporary relief from fiscal pressures and dollar weakness, while markets awaited US PCE inflation data and Fed Chair Kevin Warsh’s Jackson Hole speech for monetary policy signals.
Futures Update
US Equity futures rose 0.5% on Tuesday as chip and AI infrastructure stocks rebounded and softer Treasury yields improved sentiment. Nvidia edged higher ahead of its earnings, although concerns persisted over heavy AI Capital spending and near-term demand. Broader markets also advanced, while oil prices eased despite fresh US sanctions threats against entities facilitating trade with Iran. GE Vernova and Veritiv gained more than 2%.
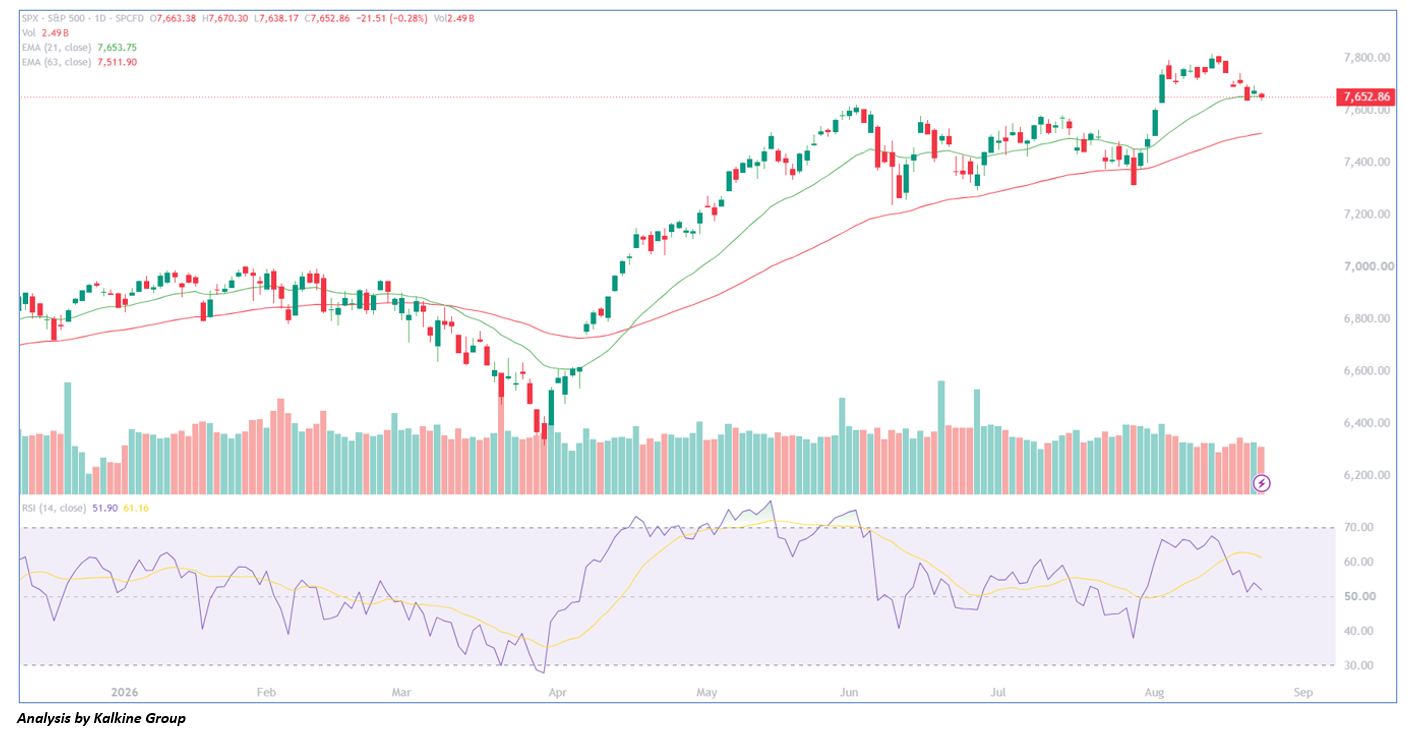
The S&P 500 is testing key dynamic support near the 21-day EMA at 7,653.75 after retreating from the recent 7,800 highs. Intraday momentum has turned cautiously neutral-to-bearish, with the 14-period RSI easing to 51.90 and muted Volume suggesting measured profit-taking rather than heavy selling pressure. A sustained break below the 7,638–7,650 support zone could trigger further downside toward the 7,600 psychological level and the 63-day EMA at 7,511.90. Conversely, holding above 7,654 and reclaiming 7,670 would strengthen the case for a short-term rebound toward the 7,700–7,750 resistance zone.

 Nov 05, 2026



 Please wait processing your request...