
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stock indexes closed higher on Tuesday as technology and semiconductor shares rallied, with the S&P 500 up 0.8%, Nasdaq 100 up 1.7%, and Dow adding 136 points to a record 52,319. Easing oil prices reduced inflation concerns, while Q2 delivered strong gains, led by a 14%+ rise in the S&P 500 and ~20% surge in the Nasdaq.
Market Movers
Among the top-performing stocks of the session 707 Cayman Holdings Limited. surged 267.59%, while Cuprina Holdings (Cayman) Limited. rallied 47.76%. On the losing side, Sable Offshore Corp. fell 55.81%, while Universe Pharmaceuticals Inc declined 49.92%, making them the weakest performers during the trading day.
Commodities Update
WTI crude fell below USD 69 per barrel and Brent declined to around USD 72 per barrel, both reaching their lowest levels since February 27, as markets weighed progress in US–Iran peace negotiations and the gradual recovery in shipping through the Strait of Hormuz. Improving tanker flows, easing geopolitical tensions, a surge in Iranian oil exports to over 40 million barrels following the lifting of a US naval blockade, and record Russian shipments that boosted seaborne inventories all reinforced expectations of increased global supply. However, sentiment remained somewhat cautious as Tehran continued to assert administrative control over the Strait of Hormuz.
Gold fell below USD 4,000/oz and silver slipped below USD 58/oz on Wednesday, pressured by strong US economic data, elevated core inflation, and rising expectations that the Federal Reserve could raise interest rates later this year, possibly as early as September. Sentiment was further shaped by upcoming US jobs data and ongoing US-Iran peace talks in Qatar, where investors hoped for a lasting ceasefire despite no direct talks being expected.
Macro Updates
US Private Hiring Slows in June 2026
US private businesses added 98K jobs in June 2026, slowing from 122K in May and missing forecasts of 113K, signaling softer job creation amid mixed labor supply and demand conditions. Financial activities and information recorded gains, while leisure and hospitality remained weak for the sixth consecutive month.
US Mortgage Applications Remain Flat
US mortgage applications were unchanged in the last full week of June, as the 30-year fixed mortgage rate eased slightly by 2 bps to 6.57%. Refinance applications fell 0.6%, while home-purchase applications rose 0.5%, reflecting limited movement in borrowing activity despite softer Treasury yields.
US Layoffs Ease in June 2026
US employers announced 45,849 job cuts in June 2026, the lowest since December 2025 and down 53% from May, with technology leading the reductions at 15,503 cuts as AI continued to influence workforce planning. Year-to-date layoffs fell 40% YoY to 443,604, while hiring plans rose 10% YoY to 914,405 in the first half of 2026.
Dollar Rebounds on Fed Rate-Hike Bets
The dollar index rose to around 101.3 on Wednesday, supported by higher Treasury yields and resilient US job openings data, which strengthened expectations that the Federal Reserve could raise rates later this year, possibly as early as September. Investors also awaited the monthly jobs report and monitored US-Iran peace talks in Qatar.
Bonds Commentary
The 10-year US Treasury yield held near 4.46% on Wednesday after a sharp rise in the prior session, as strong job openings data reinforced expectations of a more hawkish Federal Reserve and the possibility of a rate hike as early as September. Investors awaited the monthly jobs report for further labor-market signals, while also tracking US-Iran peace talks in Qatar.
Futures Update
US stock futures were little changed on Wednesday after Tuesday’s tech-led rally, where the Nasdaq rose 1.52%, the S&P 500 gained 0.79%, and the Dow added 0.26%. AI and chip stocks drove gains, while investors awaited Kevin Warsh’s ECB Forum remarks for monetary-policy signals.
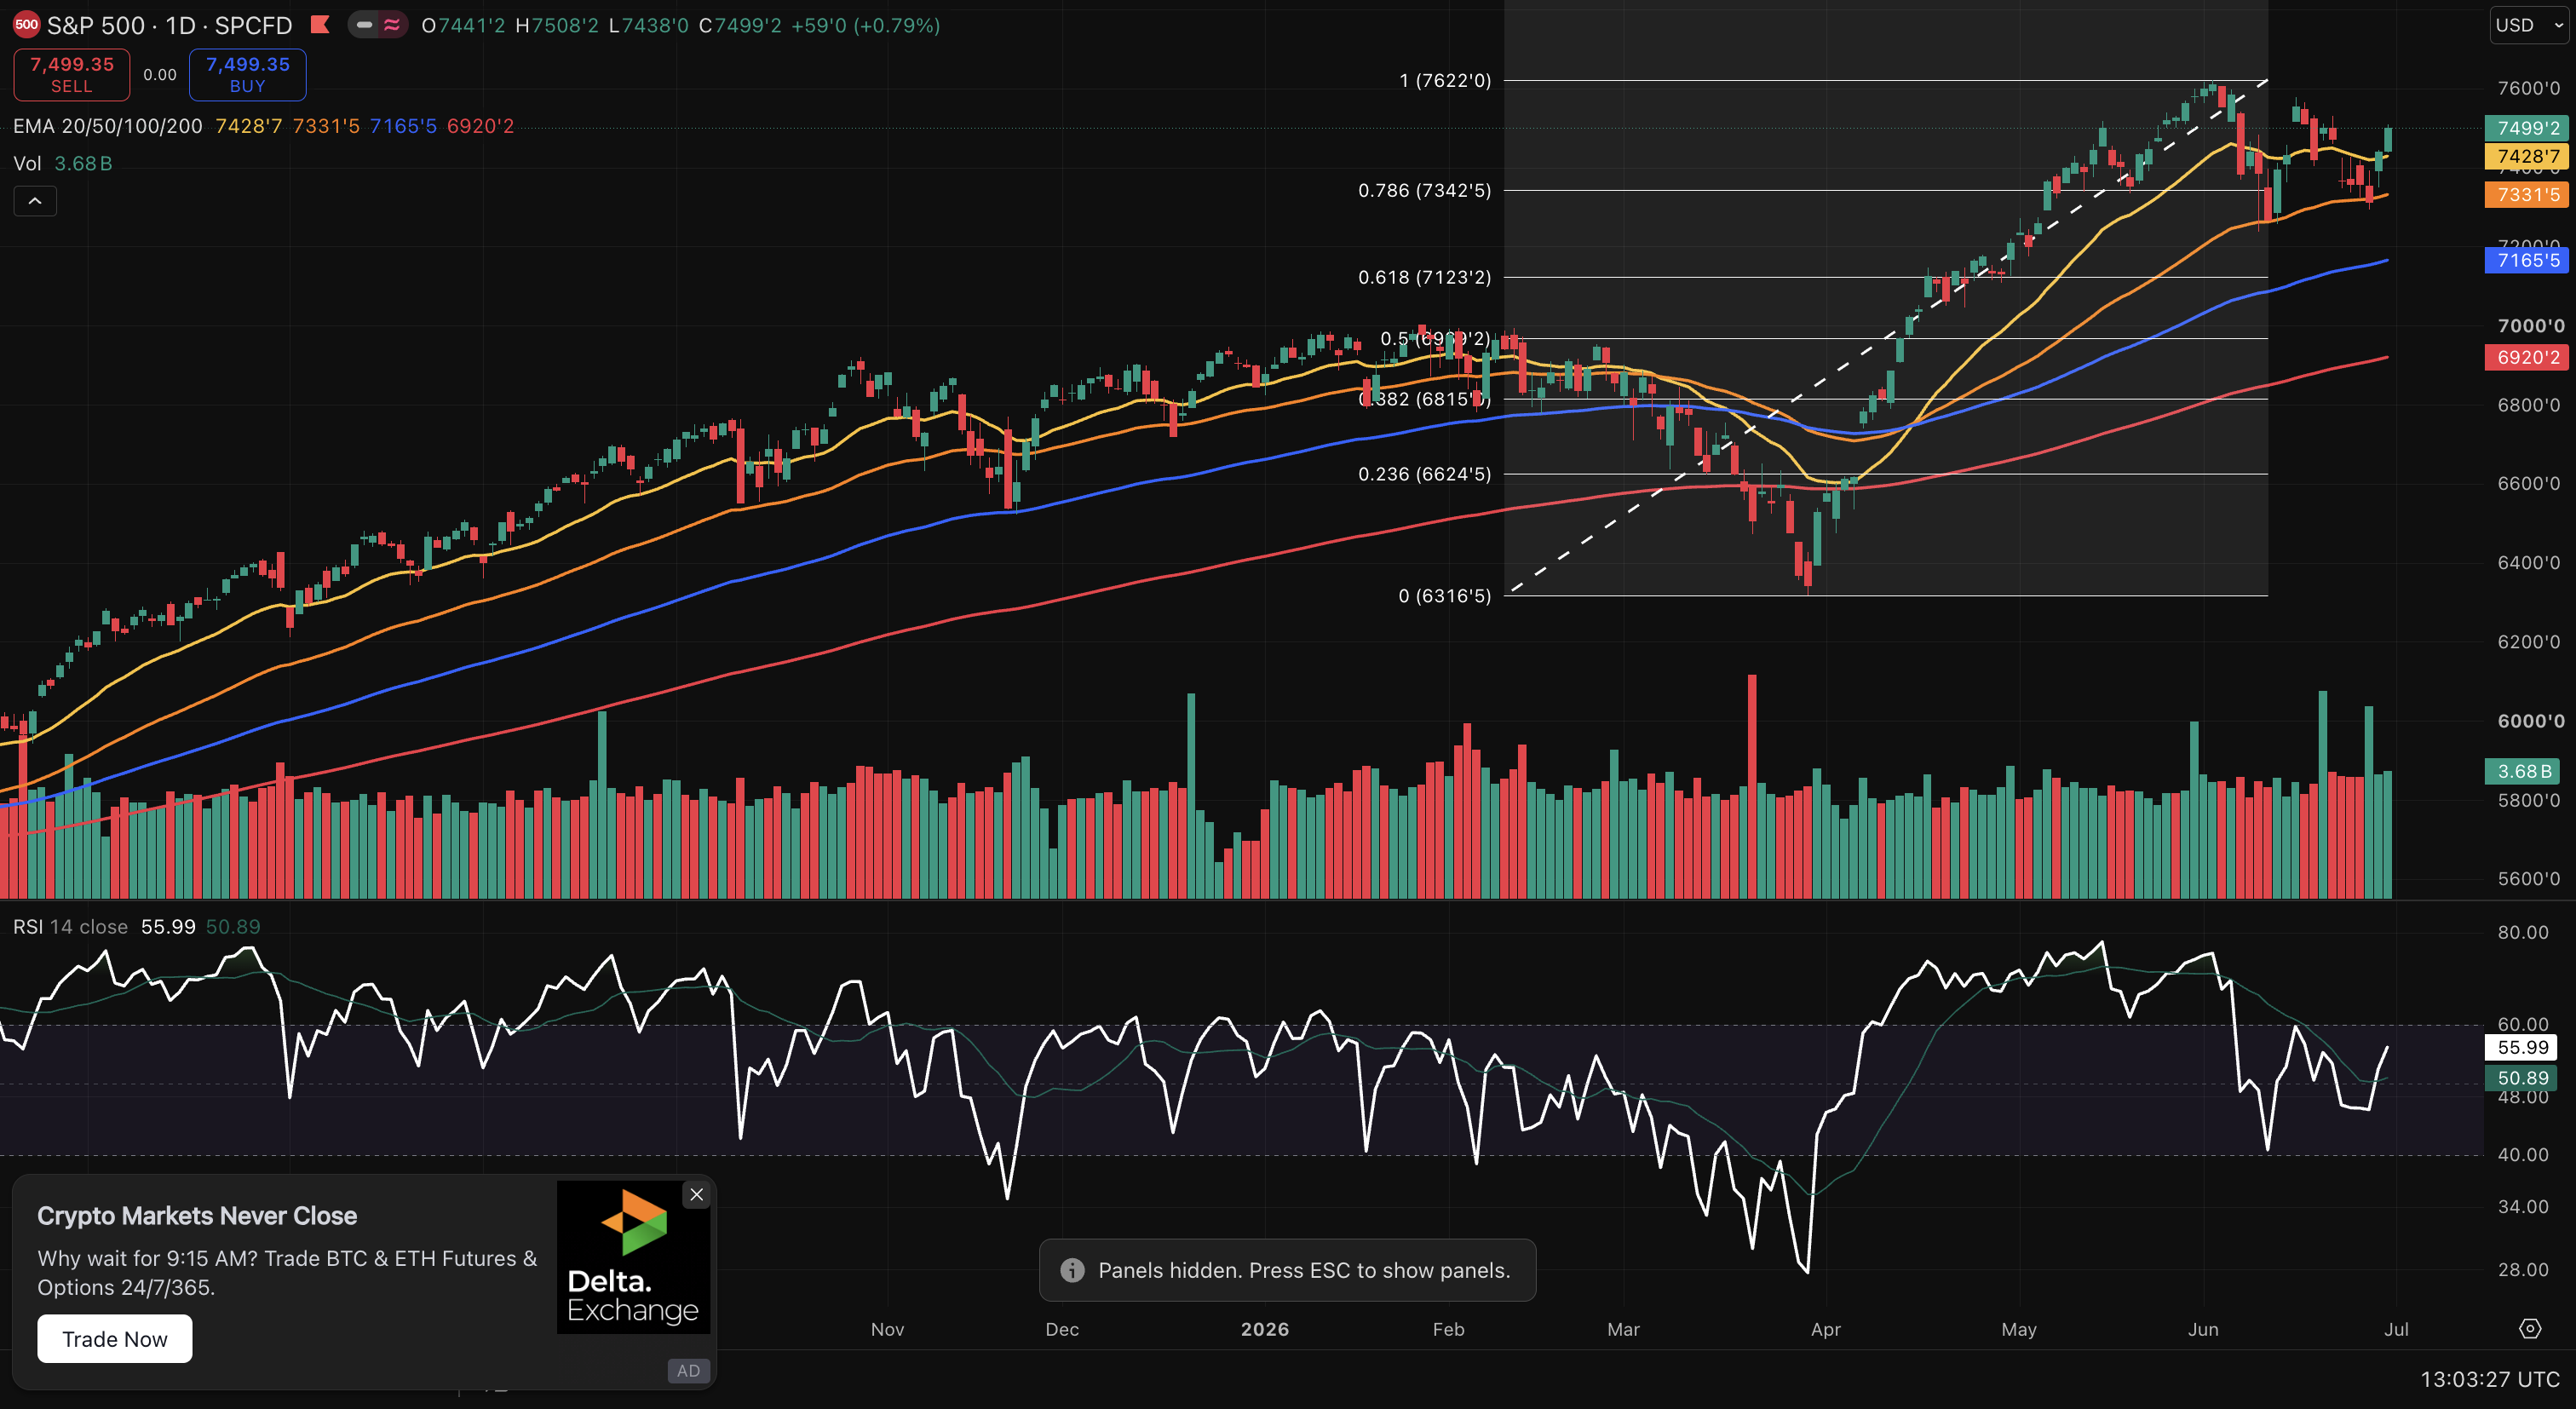
The index prints 7,499, up 0.79%, holding a constructive posture above the full EMA stack (20/50/100/200 at 7,429/7,332/7,166/6,920). The V-shaped April recovery off 6,316 has matured into a grind higher, with price reclaiming the 0.786 fib (7,343) and consolidating beneath the 7,622 swing high. June's shakeout tested the rising 20-EMA but found bids, preserving the uptrend. RSI at 56, back above its signal, signals restored momentum without froth. Tactically constructive: dips into 7,340–7,430 remain buyable while 7,166 holds. A daily close above 7,622 opens measured-move extension; failure risks a rotation toward the 50-EMA.

 Nov 05, 2026



 Please wait processing your request...