
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US equities closed mixed on Wednesday as softer inflation data and strong financial-sector earnings offset weakness in semiconductor stocks. The S&P 500 gained 0.4% and the Dow rose 150 points, while the Nasdaq 100 slipped 0.3%. Lower-than-expected producer inflation reduced expectations of a near-term Federal Reserve rate hike, supporting banks and hyperscalers, including JPMorgan, Goldman Sachs, Microsoft, Amazon, and Alphabet. However, declines in major memory-chip stocks, SpaceX, and Johnson & Johnson limited broader market gains.
Market Movers
Among the top-performing stocks of the session SOBR Safe, Inc. surged 76.92%, while Nuvve Holding Corp. rallied 36.46%. On the losing side, SANUWAVE Health, Inc. fell 39.21%, while Twin Vee PowerCats Co. declined 30.95%, making them the weakest performers during the trading day.
Commodities Update
WTI crude traded near USD 80 per barrel and Brent around USD 85 on Thursday, remaining close to one-month highs as intensified US military action against Iran raised concerns over disruptions through the Strait of Hormuz. Fresh US strikes targeted Iranian missile facilities, while reports of a possible expansion of operations, including the seizure of Kharg Island, heightened supply risks. Oil prices also found support from continued Ukrainian attacks on Russian fuel infrastructure and tankers, adding to fears of tighter global supplies.
Gold declined toward USD 4,000 per ounce and silver fell near USD 57 on Thursday as escalating Middle East tensions pushed oil prices higher, renewing inflation and interest-rate concerns. Although softer-than-expected US consumer and producer inflation data provided some support by reducing expectations of an immediate Federal Reserve rate hike, the figures did not capture the impact of the latest US-Iran escalation. Additional US strikes on Iranian targets kept geopolitical risks elevated, despite indications that Tehran may be willing to resume negotiations.
Macro Updates
Dollar Weakens as Softer Inflation Reduces Rate-Hike Expectations
The US dollar index traded near 100.5 on Thursday after two sessions of sharp declines, as weaker-than-expected consumer and producer inflation data reduced expectations of a near-term Federal Reserve rate hike. The implied probability of a September increase fell to around 44% from 50% a day earlier. However, escalating US-Iran tensions and rising oil prices kept inflation and interest-rate risks in focus, despite indications that Tehran may be willing to resume negotiations.
US Strategic Petroleum Reserve Falls to Four-Decade Low
US Strategic Petroleum Reserve inventories declined by 3 million barrels to 316.5 million in the week ended July 10, their lowest level since April 1983, as part of a planned 172-million-barrel release programme. The reserve has fallen by 98.9 million barrels since the US-Israeli conflict with Iran began in late February. Meanwhile, combined commercial and strategic crude inventories dropped to 730.8 million barrels as of July 3, the lowest level since 1984.
Bonds Commentary
The US 10-year Treasury yield held near 4.56% on Thursday after two sessions of declines, as softer consumer and producer inflation data reduced expectations of a near-term Federal Reserve rate hike. The implied probability of a September increase fell to around 44% from 50% a day earlier. However, renewed US-Iran tensions and rising oil prices kept inflation risks in focus, despite indications that Tehran may be willing to resume negotiations.
Futures Update
US stock futures were broadly flat on Thursday after Wall Street gained in the previous session, supported by softer-than-expected inflation data, lower Treasury yields, and strong financial-sector earnings. The Dow rose 0.29%, the S&P 500 gained 0.38%, and the Nasdaq advanced 0.62% on Wednesday. Investors are now focused on retail sales, weekly jobless claims, and earnings from Netflix, UnitedHealth, General Electric, and other major companies.
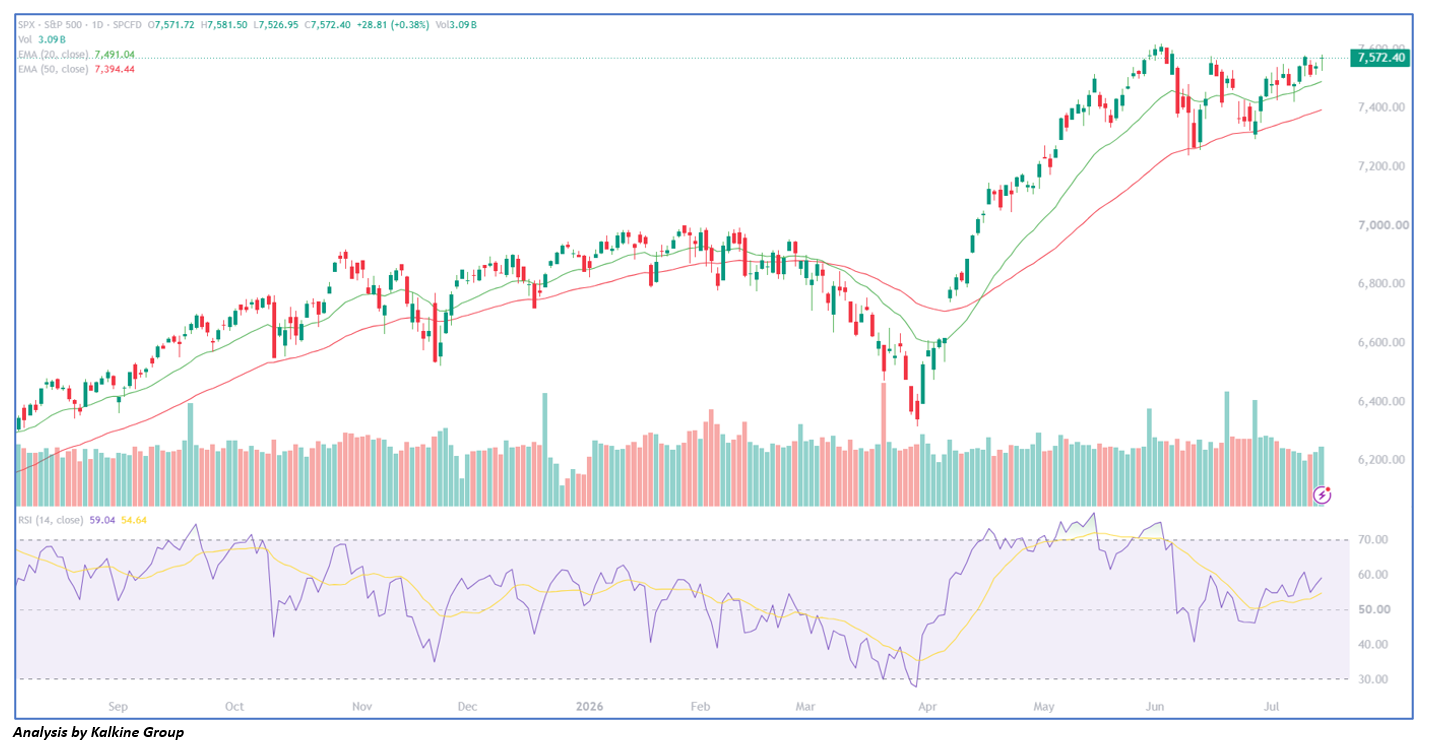 After failing to sustain an early advance, stocks traded in a choppy range on Wednesday before ending modestly higher, extending the previous session's gains. Despite the positive close, the S&P 500 is showing signs of slowing momentum as it struggles to break decisively above recent highs. While the index remains above its 20-day and 50-day EMAs, the prolonged consolidation near resistance raises the risk of a near-term pullback. The RSI around 59 suggests momentum is moderating rather than strengthening, and failure to clear resistance could invite profit-taking. A break below the 20-day EMA would weaken the short-term technical outlook and could trigger a deeper corrective move toward the 50-day EMA.

 Nov 05, 2026



 Please wait processing your request...