
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
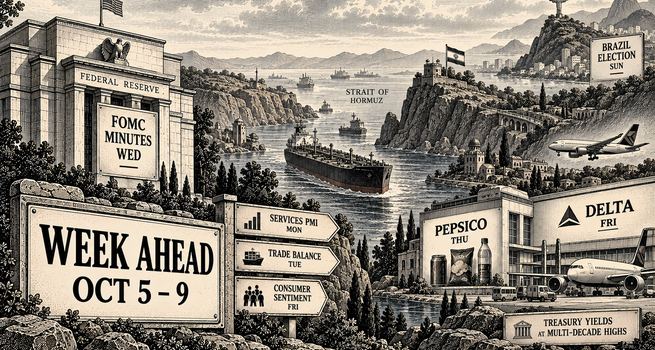
Markets enter the second week of October with bets on another near-term rate hike largely abandoned, a notable shift from the hawkish tone Chair Kevin Warsh struck following September's increase, the Fed's first since 2023. Softer-than-expected PCE Inflation and nonfarm payrolls, alongside more dovish remarks from several policymakers, have persuaded investors that the Central Bank is more likely to hold at its late-October meeting than extend the hiking cycle immediately. Wednesday's release of the FOMC minutes from that September meeting will be scrutinised for whether the committee's internal debate matches the more measured tone markets are now pricing in. The bond market, having pushed the 10-year Treasury Yield to multi-decade highs in recent weeks, remains the dominant backdrop against which every data point and Earnings report this week will be read. PepsiCo and Delta Air Lines open the third-quarter earnings season ahead of the major banks the following week, while the US-Iran standoff over the Strait of Hormuz and Brazil's presidential election on Sunday add two distinct sources of geopolitical uncertainty.
Major Ex-Dividend Dates This Week
|
Day |
Company |
Ticker |
Dividend |
Yield |
|---|---|---|---|---|
|
Monday, Oct 5 |
GE Aerospace |
$0.47 |
0.60% |
|
|
Tuesday, Oct 6 |
JPMorgan Chase |
$1.65 |
1.98% |
|
|
Tuesday, Oct 6 |
Dollar General |
$0.59 |
1.98% |
|
|
Wednesday, Oct 7 |
Comcast |
$0.33 |
6.08% |
|
|
Wednesday, Oct 7 |
Lennar |
$0.50 |
2.44% |
|
|
Thursday, Oct 8 |
Intuit |
$1.38 |
1.95% |
|
|
Thursday, Oct 8 |
Vail Resorts |
$2.22 |
6.39% |
|
|
Friday, Oct 9 |
American Express |
$0.95 |
1.26% |
|
|
Friday, Oct 9 |
Oracle |
$0.50 |
1.45% |
|
|
Friday, Oct 9 |
Mastercard |
$0.87 |
0.63% |
Monday, October 5
Economic Data
The US Services PMI for September, prior at 56.5, opens the week at 9:45 am ET, followed by the ISM Report on Business Services PMI, prior at 55.4 and forecast at 55, at 10:00 am ET. The reading is expected to show a stronger expansion in services activity, potentially the fastest pace since February, a signal that would reinforce the case for a Fed hold rather than a renewed tightening push.
Tuesday, October 6
Earnings
RPM International (NYSE:RPM) reports before the open, offering a specialty coatings and building materials read tied to construction activity. Lamb Weston Holdings (NYSE:LW) and Constellation Brands (NYSE:STZ) report later in the day, extending the consumer staples and beverage reads. Penguin Solutions (NASDAQ:PENG) reports in the afternoon, providing a data infrastructure and AI hardware Supply chain signal.
Economic Data
The US trade balance for August, prior at -$88.6 billion, is forecast to widen to -$102.1 billion at 8:30 am ET, with imports expected to have surged while exports rose at a slower pace. Dallas Fed President Lorie Logan participates in a Global Perspectives event at 6:00 pm ET.
Wednesday, October 7
Earnings
Levi Strauss (NYSE:LEVI) reports in the afternoon, providing a consumer apparel read that will be watched for evidence of how discretionary spending is holding up amid cost-of-living concerns still weighing on household sentiment. Applied Digital (NASDAQ:APLD) also reports in the afternoon, offering an AI data centre infrastructure signal.
Federal Reserve
The Federal Open Market Committee releases minutes from its September meeting at 2:00 pm ET, the week's most consequential event. The meeting produced the Fed's first rate hike since 2023, delivered alongside a hawkish tone from Chair Warsh that initially solidified expectations for further tightening. Since then, softer PCE inflation and nonfarm payrolls data, together with more dovish commentary from individual policymakers, have shifted market pricing meaningfully away from an October move. The minutes will be read for whether they reveal a committee already leaning toward patience at the time of the hike, or one that remains genuinely split on the need for additional increases before year-end. Consumer Credit for August, prior at $18.1 billion and forecast at $15 billion, is also released at 3:00 pm ET.
Thursday, October 8
Earnings
PepsiCo (NASDAQ:PEP) reports before the open as one of the week's two marquee results and the informal opening of third-quarter earnings season ahead of the major banks next week. Its organic Revenue growth, pricing power, and commentary on North American snack and beverage volumes will offer an early read on consumer resilience. Progressive Corporation (NYSE:PGR) also reports, providing an insurance Underwriting and claims trend signal, while Tilray Brands (NASDAQ:TLRY) and Helen of Troy (NASDAQ:HELE) round out the day's consumer-facing results.
Economic Data
Weekly jobless claims for the week ending October 3, prior at 197,000 and forecast at 200,000, provide the labour market read. Monthly Wholesale Trade for August, prior at 1.3%, closes the morning's releases.
Friday, October 9
Earnings
Delta Air Lines (NYSE:DAL) reports before the open as the week's second marquee result, offering the clearest available read on travel Demand and fuel cost management heading into the holiday travel season. Its results will carry additional weight given how closely airline earnings track broader consumer discretionary health.
Economic Data
The preliminary University of Michigan Consumer Sentiment index for October, prior at 47.8 and forecast at 48, is expected to show morale remaining near record lows amid persistent cost-of-living concerns, even as headline inflation data has softened. Kansas City Fed President Jeffrey Schmid speaks at a Kansas City Economic Outlook event at 9:30 am ET, closing out the week's limited Fed commentary.
Geopolitical Backdrop
The US-Iran standoff over the Strait of Hormuz remains the central geopolitical variable shaping energy markets and, by extension, the inflation outlook the Fed is weighing. Any credible move toward reopening the chokepoint or a broader de-escalation would likely ease the Bond Market pressure that has pushed yields to multi-decade highs in recent weeks, while a further hardening of positions would risk reviving the energy-driven inflation concerns that first prompted September's rate hike. The OPEC meeting this week adds a second supply-side variable that could move oil prices independently of the diplomatic track.
Brazil's presidential election on Sunday is the week's other major political event. Incumbent President Luiz Inácio Lula da Silva is expected to narrowly lead the first round, though polls suggest he may fall short of the majority needed to avoid a runoff. The outcome carries implications for Brazilian asset prices and, more broadly, for investor sentiment toward Latin American markets heading into year-end.
The Week in Context
Wednesday's FOMC minutes and the two marquee earnings reports from PepsiCo and Delta will together shape how investors read the final weeks before the late-October Fed meeting. If the minutes confirm that policymakers were already debating a pause even as they hiked in September, the market's current abandonment of October hike bets will look well-founded, and attention will shift decisively toward whether earnings growth, still running above 30% year-on-year for the S&P 500 in aggregate, can justify current valuations without additional rate support. PepsiCo's results will test consumer resilience directly, while Delta's will offer a read on discretionary travel spending. With bond yields still the dominant headwind, any further easing in Treasury yields this week, whether from the Fed minutes, the Strait of Hormuz standoff, or simply softer data, would matter more for equities than any single earnings beat.

 Oct 29, 2026
 Please wait processing your request...