
 CA
 NZ
 UK
 AU
 IND

 US
 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Consumer Discretionary (XLY) has entered the Lagging quadrant, signalling a deterioration in both relative strength and momentum.
- Energy (XLE) remains one of the strongest sectors in Improving and continues to display the market's most powerful momentum profile.
- Communication Services (XLC) remains firmly positioned in Improving and continues to advance toward the Leading quadrant.
- No sector currently occupies the Leading quadrant, highlighting an ongoing transition in market leadership.
- Financials (XLF), Health Care (XLV), Industrials (XLI), and Utilities (XLU) remain in Weakening, reflecting fading momentum despite maintaining positive relative strength.
- Technology (XLK), Materials (XLB), Consumer Staples (XLP), Real Estate (XLRE), and Consumer Discretionary (XLY) now occupy the Lagging quadrant.
- The rotation suggests investors continue to favour Energy and Communication Services while reducing exposure to several previously favoured sectors.
The latest Relative Rotation Graph (RRG) for July 15, 2026, highlights a further evolution in US sector leadership. Consumer Discretionary has rotated into the Lagging quadrant, joining Technology, Materials, Consumer Staples, and Real Estate among the market's underperformers. Meanwhile, Energy and Communication Services remain firmly positioned within Improving and continue to strengthen their cases as the most likely candidates to assume future leadership. With no sector currently occupying the Leading quadrant, the market remains in a transitional phase as investors search for the next sustainable source of relative strength.
US Sector Relative Momentum Chart
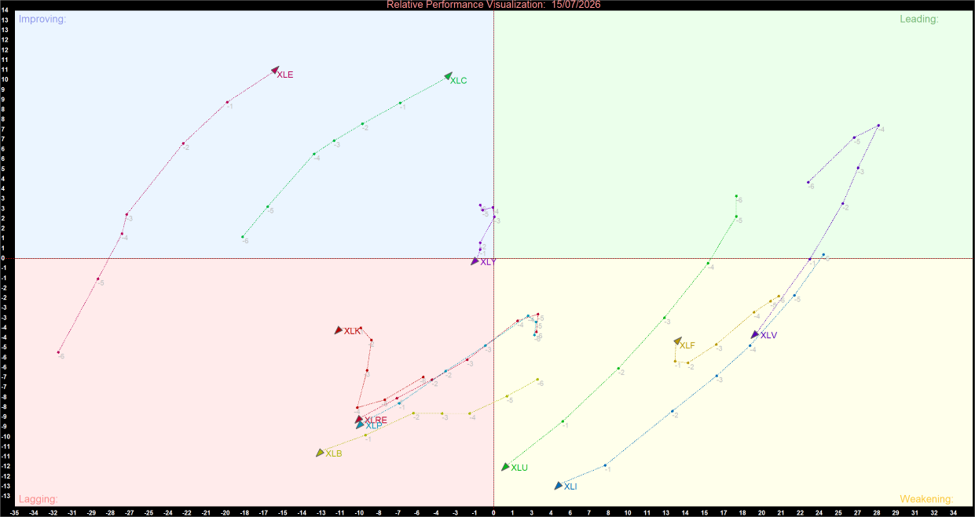
US Sector Relative Momentum Chart (at the closing price of 15/07/2026). Powered by: amibroker.com
Key Market Theme
The Leading Quadrant (The Market Leaders)
- No sector currently occupies the Leading quadrant. The absence of a leadership sector suggests the market remains in a period of transition, with investors increasingly focused on identifying sectors capable of establishing sustainable relative strength. Until a sector rotates into Leadership, market leadership is likely to remain fragmented.
The Improving Quadrant (Emerging Leaders)
- Energy (XLE) remains one of the strongest sectors on the chart and continues to exhibit an impressive north-east trajectory. The sector has staged a remarkable recovery from deep Lagging territory and now possesses the strongest momentum profile among all sectors. Continued strength in commodity-related assets and energy companies could pave the way for a future move into Leadership.
- Communication Services (XLC) remains firmly positioned within Improving and continues to strengthen its relative performance. The sector's persistent upward trajectory reflects growing investor confidence in media, internet, and communication-related businesses. If current trends persist, Communication Services appears well-positioned to challenge for leadership in the weeks ahead.
The Weakening Quadrant (Losing Momentum)
- Health Care (XLV) remains in Weakening after recently rotating out of Leadership. While relative strength remains positive, momentum continues to fade, suggesting investors are becoming more selective toward defensive growth opportunities.
- Financials (XLF) continue to reside in Weakening. Although the sector maintains respectable relative strength, momentum has softened noticeably over recent weeks. Renewed buying interest will be required before Financials can challenge for leadership once again.
- Industrials (XLI) remain in Weakening and continue to exhibit declining momentum. While relative performance remains above market averages, investor participation has become increasingly selective.
- Utilities (XLU) remain in Weakening despite gradual improvements in momentum. The sector's defensive characteristics continue to support relative strength, although momentum remains insufficient to support a return to Leadership.
The Lagging Quadrant (Underperformers)
- Consumer Discretionary (XLY) has entered Lagging, representing one of the most significant developments on the latest chart. The move suggests that both relative strength and momentum have deteriorated, reducing the sector's ability to participate in broader market leadership.
- Information Technology (XLK) remains in Lagging despite some recent signs of stabilisation. The sector continues to exhibit weak relative momentum compared with stronger market groups.
- Materials (XLB) remain firmly positioned within Lagging and continue to underperform the broader market. While downside momentum has moderated, meaningful relative strength improvement has yet to emerge.
- Consumer Staples (XLP) continue to reside in Lagging and remain one of the weaker defensive sectors on the chart.
- Real Estate (XLRE) remains in Lagging despite showing early signs of stabilisation. Sustained momentum improvement will be required before the sector can transition toward Weakening.
Strategic Summary
The latest RRG profile continues to highlight a market searching for its next leadership group. With no sector currently occupying the Leading quadrant, Energy (XLE) and Communication Services (XLC) remain the strongest candidates to assume leadership based on their powerful momentum profiles within Improving.
The most notable change is the rotation of Consumer Discretionary (XLY) into Lagging, indicating a meaningful deterioration in both momentum and relative strength. Meanwhile, Financials (XLF), Health Care (XLV), Industrials (XLI), and Utilities (XLU) continue to reside in Weakening, while Technology (XLK), Materials (XLB), Consumer Staples (XLP), and Real Estate (XLRE) remain in Lagging.
Overall, sector rotation continues to favour Energy and Communication Services, while a growing number of sectors struggle to establish sustainable momentum. This suggests investors remain highly selective and increasingly focused on areas demonstrating improving relative strength.

 Nov 16, 2026
 Please wait processing your request...