
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
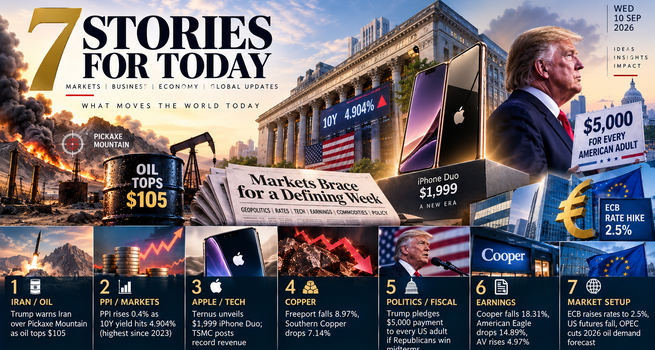
President Trump warned Iran "not to get cute" over suspicious activity at the Pickaxe Mountain nuclear site, sending Brent Crude above $105 as producer prices posted their biggest monthly gain in three months. Apple unveiled its first foldable iPhone under new CEO John Ternus, copper miners sank on a broad risk-off Reversal from record prices, and Trump pledged a $5,000 payment to every American adult if Republicans win November's midterms.
1. IRAN: Trump Warns Iran "Not to Get Cute" Over Pickaxe Mountain Activity as Oil Tops $105 a Barrel
President Trump warned Iran against activity at Pickaxe Mountain, a suspected nuclear site near the damaged Natanz facility, saying "I would advise Iran not to get cute because we will have to hit them very hard." An analysis found more road activity at the site "than at any point in the site's history," with construction shifting from excavation toward internal building, which the think tank called suspicious given the proximity to Natanz. The US struck three Iranian nuclear sites, including Natanz, in June 2025. Iran said Wednesday it fired missiles at a US base in Jordan and attacked 10 ships near Hormuz in retaliation for the destruction of five Iranian tankers earlier in the week. Trump said he does not expect the war to end before November's midterms, adding that short-term economic pain is worth preventing Iran from developing nuclear weapons. Brent crude reversed earlier losses to trade above $105 Thursday, while WTI topped $100. ING strategists said Chinese buying behavior will largely determine whether the rally has follow-through or fades.
- CSIS's assessment that construction has shifted from excavation to internal building suggests the Facility may be approaching operational readiness, raising the stakes of any US strike decision.
- Risk note: Trump's admission that the war will likely extend past the midterms means markets should price sustained elevated oil as a base case, particularly if Pickaxe Mountain provides a pretext for further escalation.
2. PPI: Wholesale Inflation Rises 0.4% as Treasury Yields Hit Highest Since 2023 on Disappointing Buyback
The producer price index rose 0.4% in August, the biggest monthly increase in three months and in line with expectations, driven by a 1.1% jump in goods prices as diesel surged 24.1%; core PPI rose a softer 0.2%, below the 0.3% forecast. Year over year, headline PPI accelerated to 5.4% from 4.8%, while core PPI rose 4.6%. The data was overshadowed by a fresh leg higher in Treasury yields after Wednesday's announcement that the Treasury would buy back up to $6 billion in longer-dated debt, triple the usual amount, disappointing investors expecting a larger program; the 10-year yield climbed as high as 4.904%, its highest since November 2023, while the 2-year hit 4.501% and the 30-year rose to 5.341%. The buyback remains far short of what would be needed to materially move long-end yields. Initial jobless claims eased to 206,000, near a roughly 60-year low reached in mid-July, while continuing claims fell to 1,774,000. Friday's consumer price index, with consensus at 0.4% monthly and 3.4% annually, is the last major inflation signal before the Fed's September 16 decision.
- Yields rising sharply despite an in-line PPI print shows the Treasury's own Debt management actions, not inflation data, are currently the dominant driver of borrowing costs.
- Risk note: with the 10-year above its November 2023 high and CPI still to come, an upside surprise could push yields into territory not seen since the depths of the 2023 rate cycle, compounding pressure on equities and housing.
3. APPLE: Ternus Unveils $1,999 iPhone Duo as TSMC Posts Record Revenue and Nasdaq Deepens Kraken Tie-Up
Apple (NASDAQ:AAPL) shares rose 1% Thursday premarket, a day after new CEO John Ternus unveiled the company's first foldable smartphone, the iPhone Duo, alongside the iPhone 18 Pro lineup in his first product event since succeeding Tim Cook. The Duo features a 7.6-inch inner display, 5.4-inch outer screen, and Apple's new A20 Pro chip on a 2-nanometer process, priced at $1,999, about $100 more than comparable Samsung and Google foldables, with preorders opening October 16. The iPhone 18 Pro and Pro Max received a $100 price increase to $1,199 and $1,299, attributed to rising memory chip costs. Ternus framed privacy as Apple's key AI-era differentiator, with Siri now working across more than 300,000 apps at launch. Investor response was muted Wednesday, shares closing slightly lower before Thursday's modest gain. Separately, TSMC (NYSE:TSM) reported record August revenue of $16.35 billion, up 53.3% year over year, maintaining a 72.5% global foundry Market Share on robust AI chip demand. Nasdaq (NASDAQ:NDAQ) said its venture arm will invest $100 million in Kraken parent Payward, deepening a tokenization Partnership for trading tokenized equities outside conventional market hours.
- The muted initial reaction to Apple's foldable launch, despite specs exceeding rival offerings on storage and chip technology, suggests the market is waiting for sales data rather than pricing in success from the unveiling alone.
- Risk note: with memory chip costs cited for the Pro line's price increase, and TSMC's capacity fully booked on AI demand, further component cost inflation could pressure Apple's margins even if the Duo sells well.
4. COPPER: Freeport-McMoRan and Southern Copper Sink as Miners Reverse From Record Highs on Broad Risk-Off
Freeport-McMoRan (NYSE:FCX) shares fell as much as 8.97% pre-market and Southern Copper (NYSE:SCCO) dropped as much as 7.14%, retreating after a multi-day rally driven by record copper prices that pushed LME futures above $14,694 per ton this week. The pullback is tied to broader risk-off sentiment as oil above $100 and rising yields pressure equities, even as copper fundamentals, including depleted LME inventories, tariff-driven Supply distortions, and Freeport's Grasberg recovery, remain supportive. Southern Copper's second-quarter results beat expectations, with EPS of $1.99 and Operating Cash Flow up 116.9% year over year to $3.68 billion, prompting a raised $1.10 quarterly dividend, though the consensus rating remains a Reduce with an average target of $146.84, well below current levels. Institutional holders including CalSTRS, BlackRock, and Wellington have continued adding positions despite the pullback.
- The divergence between Southern Copper's Reduce rating and continued institutional accumulation suggests professional investors are positioning for a longer-term supply squeeze Sell-Side targets have not caught up to.
- Risk note: with the pullback driven by macro risk-off rather than deteriorating fundamentals, a stabilization in oil or yields could just as quickly reverse today's losses.
5. POLITICS: Trump Pledges $5,000 Payment to Every American Adult if Republicans Win November Midterms
President Trump promised every adult American citizen a $5,000 payment if Republicans retain the House and win the Senate in November, telling a GOP convention crowd in Dallas to "pretend that I'm on the ballot." The proposed payout would cost more than $1 trillion, comparable to the $1.27 trillion already spent on debt interest this fiscal year and the $1.36 trillion committed to defense spending in 2026, with the Deficit nearing $1.8 trillion year to date and debt at 122.6% of GDP as of the first quarter. Federal law makes it a criminal offense to offer payments to induce voting, an issue that drew scrutiny after a bipartisan Wisconsin panel found Elon Musk likely broke state law with similar voter payments in 2025. The pledge follows two previous unfulfilled Trump payment promises: a $5,000 "DOGE dividend" and a $2,000 Tariff rebate that unraveled after the Supreme Court ruled against his tariff regime. Trump's net approval stands at negative 26, with Democrats currently projected to win the House.
- The proposal arriving after two previous unfulfilled payment pledges suggests markets and voters alike have reason to treat this as a campaign rhetoric device rather than a credible near-term fiscal commitment.
- Risk note: even if never implemented, the pledge's trillion-dollar scale, floated against an already-widening deficit, could reinforce Bond Market concerns about long-term US fiscal discipline already contributing to elevated Treasury yields.
6. EARNINGS: Cooper Companies Sinks 18% on Weak Guidance as American Eagle, Macy's, and AeroVironment Diverge
Cooper Companies (NASDAQ:COO) shares fell as much as 18.31% pre-market after fourth-quarter guidance of $1.057 billion to $1.08 billion revenue and $1.05 to $1.09 adjusted EPS fell short of estimates, even as third-quarter results beat for an eleventh straight quarter; the board decided to retain rather than divest CooperSurgical, disappointing investors hoping for a sale, prompting downgrades to neutral from BofA, Baird, Piper Sandler, JPMorgan, and Jefferies despite a $1 billion buyback increase. American Eagle Outfitters (NYSE:AEO) shares dropped as much as 14.89% despite beating on both lines, as investors focused on $161 million of Operating Income from tariff refunds while core Brand comps fell 1% and margins weakened, even as Aerie surged 19% to 25%. Macy's (NYSE:M) shares slipped as much as 3.88% despite beating estimates and raising full-year guidance, after third-quarter adjusted EPS guidance of a $0.19 to $0.23 loss came in wider than the Street's expected $0.06 loss. AeroVironment (NASDAQ:AVAV) shares jumped as much as 4.97% after first-quarter results crushed estimates, with adjusted EPS of $0.59 versus a $0.22 to $0.25 estimate and a record $1.5 billion funded backlog, driven by contract wins including a $465 million directed energy laser deal, the first-ever US military production contract for the technology. Enbridge (NYSE:ENB) shares fell nearly 3% after announcing a $2.55 billion Acquisition of Tallgrass Energy's crude transportation business, while Navan (NASDAQ:NAVN) sank 15.4% after second-quarter Earnings only narrowly beat estimates.
- The pattern across Cooper, American Eagle, and Macy's, all beating headline numbers yet selling off on guidance or Capital allocation, shows scrutiny this earnings season has shifted from trailing results to forward commitments.
- Risk note: AeroVironment's rally, resting on defense contracts tied to ongoing conflict, means momentum could prove sensitive to any de-escalation in the same tensions driving broader risk-off sentiment.
7. MARKET SETUP: ECB Raises Rates to 2.5% as Stock Futures Fall, OPEC Cuts Oil Demand Forecast Again
The ECB raised its key deposit rate by 25 basis points to 2.5%, fully priced in ahead of the decision, after eurozone inflation hit 3.3% in August with energy inflation surging to 14.3%; Deutsche Bank's client survey showed no consensus on where the hiking cycle ends, split between a 2.75% peak, a hold at 2.5%, and a 3% terminal rate. US stock futures fell Thursday, with Nasdaq 100 futures down 1.1%, S&P 500 futures off 0.4%, and Dow futures down 0.3%, as oil's climb above $100 pressured sentiment following Wednesday's roughly 400-point Dow decline. OPEC lowered its 2026 global oil demand growth forecast to 380,000 barrels per day, its fifth consecutive downward revision, while raising its 2027 forecast. Meta (NASDAQ:META) rose 1.4% on a JPMorgan upgrade citing AI rollout upside, and Novartis (NYSE:NVS) gained nearly 2% after Reuters reported a major Shareholder called for a board governance overhaul following the company's recent trial setbacks.
- The ECB hiking into a war-driven energy inflation shock it has limited ability to control illustrates the constrained position central banks face when the inflation source is geopolitical rather than domestic demand.
- Risk note: OPEC's fifth straight downward demand revision arriving even as oil climbs on supply disruption fears suggests current price strength is driven by geopolitical risk rather than consumption growth, a divergence that could reverse if diplomatic progress emerges.

 Nov 19, 2026
 Please wait processing your request...