
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
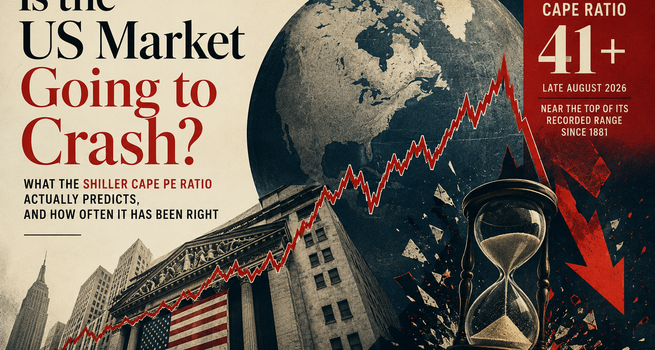
Key Highlights
- The Shiller CAPE Ratio has been reported above 41 in late August 2026, near the top of its recorded range since 1881.
- CAPE is not a crash indicator. Its underlying logic concerns the multiple change component of long horizon returns, not the timing or probability of a decline.
- Counted properly, there have been only three or four independent episodes of CAPE above 30 in nearly 150 years, which caps how much can be inferred from the historical record.
- The hit rate is mixed. Of the completed ten year windows starting from CAPE above 30, some produced deeply negative real returns and at least one produced positive real returns above 4% annualised.
- The Base Rate is the missing piece in most crash articles. A decline of 20% or more has occurred roughly every five to seven years regardless of valuation, so a high CAPE forecast must beat that baseline to carry information.
- Where CAPE does have a defensible hit rate is in predicting below average ten year real returns, not in predicting crashes. Those are different claims with different accuracy records.
The Short Answer
Nobody knows, and the Shiller CAPE ratio was never built to answer that question.
That is not evasion. It is the accurate description of what the metric is and what it can support. A CAPE reading above 41 does carry information, but the information concerns the shape of the ten year return distribution, not the probability of a decline in the next twelve months. Over one year horizons, the statistical relationship between CAPE and returns is close to nothing.
The rest of this article sets out the actual mechanism, then tests it against every high valuation episode on record.
The True Logic of CAPE, Stated Properly
Long horizon Equity return decomposes into three components:
Total return = Dividend Yield + real Earnings growth + change in the valuation multiple
That is an identity rather than a theory. Any return an investor earns over a decade comes from one of those three sources.
CAPE speaks to the third term only. A CAPE of 41 says that the multiple is high relative to its own history, which means the distribution of future multiple change is skewed to the downside. It says nothing about the first two terms and nothing about when the third term resolves.
This is the point almost every alarmist treatment of the metric misses. High CAPE is a statement about one of three return drivers over a ten year period. It is not a statement that a crash is imminent, because a compressing multiple does not require a crash.
The Three Ways a High CAPE Resolves
Multiple compression can happen through three different paths, and history contains all three.
Path one: the crash. Price falls sharply and the multiple compresses with it. September 1929 is the archetype. CAPE was 32.6 and the market fell roughly 86% over the following three years.
Path two: the grind. Price goes broadly sideways in nominal terms while Inflation erodes real value and earnings slowly grow into the multiple. January 1966 to August 1982 is the case study. CAPE fell from 24.1 to 6.6 over sixteen years. There was one severe Bear Market inside that stretch, 1973 to 1974, but the defining feature was not a crash. It was a very long period of real returns close to zero. An investor who spent those years waiting for a single dramatic crash to signal the bottom largely missed what was actually happening.
Path three: earnings catch up. Earnings grow faster than price, so the multiple compresses while returns stay positive. If earnings compound at 9% and the multiple contracts at 4% annually, an investor still earns a positive return. Portions of the 2021 to 2024 period worked this way.
Only one of those three paths is a crash. A high CAPE reading does not tell you which path you are on.
The Hit Rate: Every High Valuation Episode and What Followed
This is the section that decides the argument. The table below tracks episodes where CAPE crossed 30. Figures are approximate and require verification against the Shiller dataset before publication.
|
Episode start |
CAPE |
Next 12 months |
Next 3 years |
Subsequent 10 year real return |
Verdict |
|
September 1929 |
32.6 |
Steep decline |
Trough near negative 86% |
Negative, roughly minus 1% annualised |
Hit |
|
July 1997 |
About 30 |
Strongly positive |
Positive, near plus 45% |
Positive, roughly plus 4% to 5% annualised |
Miss |
|
January 2000 |
About 43 |
Negative |
Negative |
Negative, roughly minus 3% annualised |
Hit |
|
January 2018 |
About 33 |
Modestly negative |
Positive |
Window incomplete, running strongly positive |
Tracking as a miss |
|
January 2020 |
About 31 |
Decline of 34% then full recovery inside months |
Positive |
Window incomplete, positive |
Ambiguous |
|
November 2021 |
38.6 |
Negative, bear market of about 25% |
Recovered to new highs |
Window incomplete |
Ambiguous |
Read that table carefully, because it does not say what a crash article wants it to say.
Of the three completed ten year windows, two were hits and one was a clear miss. The July 1997 case is the one that deserves attention. CAPE crossed 30, which was extreme by all prior history, and the following decade delivered positive real returns of roughly 4% to 5% annualised. An investor who exited on that signal was wrong for ten years, and was also wrong through the intervening 1999 peak and the 2000 to 2002 collapse.
The 2018 case is more damaging still. CAPE was above 33, a level exceeded only during the dot com period, and the subsequent years produced some of the strongest returns in market history.
The Base Rate Problem
Here is the omission that runs through almost every valuation warning piece.
Declines of 20% or more are not rare events that require an explanation. Depending on how they are counted, whether by closing prices or intraday, on price or total return basis, the S&P 500 has entered a decline of 20% or more roughly every five to seven years since 1928.
That produces an unconditional probability. Before knowing anything about valuation, the chance of a 20% decline occurring within any given three year window is already somewhere near 40% to 50%.
So when someone points to a high CAPE reading and notes that a bear market followed, the relevant question is not whether a decline occurred. The question is whether the high reading raised the probability above the baseline that existed anyway. Conditioning on high CAPE plausibly moves that number to somewhere in the 55% to 60% range. That is a real edge and it is worth knowing. It is not a forecast, and it is nowhere close to the language of inevitability that these articles typically use.
A forecaster predicting rain in a city where it rains 45% of the time is right often. That does not mean the forecast contained information.
Where CAPE Does Have a Genuine Hit Rate
The metric earns its reputation on a narrower claim than crash prediction.
Sorted into deciles by starting valuation, the top CAPE decile has historically been followed by ten year real returns that were below the full sample average in the large majority of cases. The hit rate on that specific claim is high, somewhere in the region of 75% to 85% depending on period and return definition. The relationship explains perhaps 35% to 55% of the variation in subsequent ten year real returns across the full 1881 sample.
That is a legitimate and useful finding. Note precisely what it claims: below average returns, over ten years. It does not claim negative returns, and it does not claim a crash.
Two caveats limit even this.
Ten year windows sampled monthly overlap by 119 of 120 months, which inflates apparent statistical significance. Across nearly 150 years there are roughly 14 genuinely independent ten year windows, not thousands. Amit Goyal and Ivo Welch documented this problem across the return predictability literature.
The relationship also weakens substantially in the post 1990 sample, and the market has been above its full history average continuously since roughly 1991.
Scorecard
|
Claim |
Hit rate |
Verdict |
|
Predicts a crash within 12 months |
Close to zero predictive power |
Fails |
|
Predicts a crash within 3 years |
Modest edge over a 40% to 50% base rate |
Weak |
|
Predicts timing of a peak |
No record of success |
Fails |
|
Predicts below average 10 year real returns |
Roughly 75% to 85% from the top decile |
Works |
|
Predicts the magnitude of a decline |
Not designed for it, no record |
Fails |
|
Predicts negative 10 year real returns from above 40 |
One completed observation |
Insufficient data |
The last row is the honest answer to the question in the title. Above CAPE 40, the completed historical record contains one episode. One observation is an anecdote, not a base rate.
Key Risks
- Mean reversion risk. If the multiple compresses toward the post 1990 average near 27 without offsetting earnings growth, the arithmetic implies a substantial price decline.
- The grind scenario. The path that most investors underweight is not a crash but a long stretch of real returns near zero, as occurred from 1966 to 1982. It is harder to identify while it is happening and harder to hold through.
- Concentration risk. index level valuation currently reflects a small number of very large constituents, so index CAPE and median constituent CAPE can diverge.
- Rate risk. Rising real yields compress the equity earnings yield advantage and weaken the relative valuation argument.
- Opportunity cost risk. This is symmetrical and frequently ignored. Acting on a signal that has read expensive for over thirty years has its own documented cost.
Conclusion
The question in the title has no answer, and the metric in the subtitle was not built to provide one.
What CAPE above 41 supports is a narrow and useful conclusion: expected real returns from this starting point are probably below the long run average, and the distribution of ten year outcomes is skewed less favourably than it was at lower valuations. That conclusion is worth acting on through position sizing and return expectations rather than through prediction.
What it does not support is a crash call. The completed historical record above CAPE 30 contains two hits and one clear miss. Above CAPE 40 it contains one observation. Declines of 20% arrive every five to seven years regardless of what the ratio reads, which means the burden on any valuation based warning is to demonstrate an edge over that baseline, not merely to point at the baseline and call it a prediction.
The most likely resolution of a high CAPE, judged on the historical record, is disappointment rather than catastrophe. Those are not the same thing, and conflating them is how Valuation Analysis turns into forecasting.

 Nov 20, 2026
 Please wait processing your request...