
 CA
 NZ
 UK
 AU
 IND

 US
 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Health Care, Consumer Staples, and Communication Services Lead: XHJ, XSJ, and XPJ remain firmly positioned in the Leading quadrant, maintaining superior relative strength versus the broader market.
- Utilities Continue Improving: XUJ has advanced within the Improving quadrant and is emerging as a strong candidate to join the market leadership group.
- Technology and Financials Build Momentum: XTJ and XFJ continue strengthening within the Improving quadrant, reflecting growing investor interest in growth-oriented sectors.
- Energy Moves into Weakening: XNJ has slipped into the Weakening quadrant, indicating that momentum is deteriorating despite maintaining positive relative strength.
- Materials Remain the Weakest Sector: XEJ continues to occupy the deepest position within the Lagging quadrant despite recent signs of stabilisation.
The ASX sector rotation profile on June 29, 2026, reflects a market still led by defensive sectors, although momentum is gradually broadening across the market. Health Care, Consumer Staples, Communication Services, and Utilities continue attracting institutional capital, while Technology and Financials are showing encouraging signs of recovery. Meanwhile, Energy has started losing momentum, and Materials, Industrials, and Real Estate remain relative underperformers.
The latest Relative Rotation Graph suggests investors are maintaining exposure to quality and defensive sectors while selectively increasing allocations to areas showing improving momentum. This article follows the style and structure of the reference report.
ASX Sector Momentum Summary
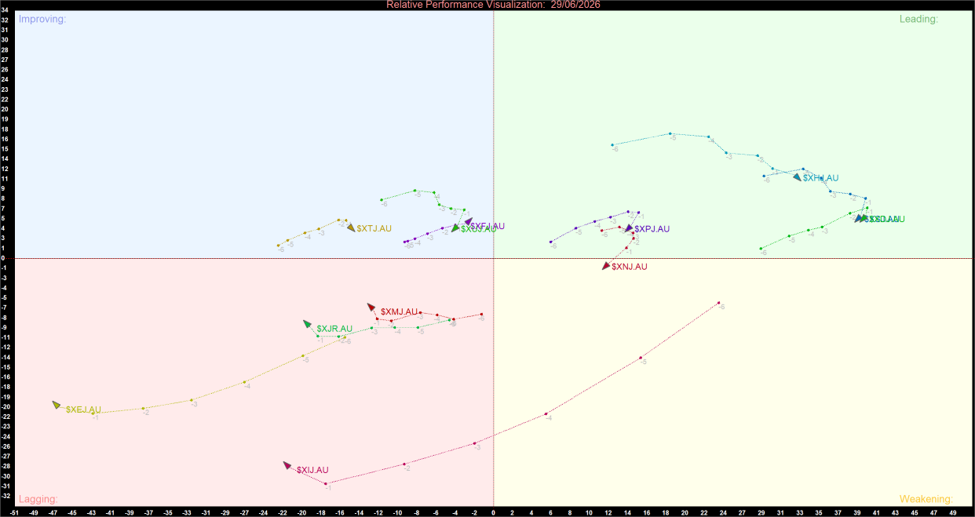
US Sector Relative Momentum Chart (at the closing price of 29/06/2026). Powered by: amibroker.com
The Leading Quadrant (The Market Leaders)
- Health Care (XHJ) remains firmly positioned within the Leading quadrant. Although momentum has moderated from previous highs, the sector continues to display strong relative strength as investors favour defensive growth opportunities and resilient earnings profiles.
- Consumer Staples (XSJ) continues to outperform the broader market. The sector's combination of earnings stability, reliable cash flows, and defensive characteristics has helped maintain its leadership position.
- Communication Services (XPJ) remains in the Leading quadrant after a successful rotation from Improving. Strength in digital media, telecommunications, and communication-related businesses continues to support relative outperformance.
- Consumer Discretionary (XDJ) also remains within the Leading quadrant. While the sector's trajectory suggests some moderation in momentum, relative strength remains firmly positive, supported by resilient consumer spending trends.
The Improving Quadrant (The Emerging Leadership Candidates)
- Utilities (XUJ) has established itself within the Improving quadrant and is moving steadily toward Leading territory. The sector's improving momentum suggests growing investor demand for stable earnings and defensive income streams.
- Information Technology (XTJ) continues strengthening within the Improving quadrant. Its north-easterly trajectory reflects improving relative performance as investors gradually return to growth-oriented opportunities.
- Financials (XFJ) remains firmly in the Improving quadrant. Continued momentum improvement suggests growing confidence in banking profitability and the broader economic outlook.
- Health Care's supporting momentum cluster continues to reinforce the improving breadth of the market, with several sectors displaying constructive rotational characteristics.
The Weakening Quadrant (Losing Momentum)
- Energy (XNJ) has moved into the Weakening quadrant. Although relative strength remains above average, momentum has deteriorated noticeably during recent periods. The sector's trajectory suggests investors are becoming more selective toward commodity-sensitive industries.
The Lagging Quadrant (Structural Underperformers)
- Materials (XEJ) remains the weakest sector on the Relative Rotation Graph. While recent rotations indicate momentum is stabilising, relative strength remains deeply negative compared with the broader market.
- Real Estate (XIJ) continues to occupy the Lagging quadrant despite showing one of the strongest momentum recoveries among underperforming sectors. Further improvement will be required before the sector can transition toward Improving territory.
- Industrials (XJR) remains in the Lagging quadrant but has demonstrated gradual stabilisation. Relative performance continues to improve from recent lows, suggesting selling pressure is beginning to ease.
- Materials and industrial-related sectors remain challenged by softer investor demand and a preference for sectors with stronger relative momentum.
Strategic Summary
The latest Relative Rotation Graph continues to favour Health Care (XHJ), Consumer Staples (XSJ), Communication Services (XPJ), and Consumer Discretionary (XDJ), all of which remain firmly positioned within the Leading quadrant.
Meanwhile, Utilities (XUJ), Information Technology (XTJ), and Financials (XFJ) continue building momentum within the Improving quadrant and represent the strongest candidates to emerge as future market leaders.
On the other hand, Energy (XNJ) has entered the Weakening quadrant, while Materials (XEJ), Real Estate (XIJ), and Industrials (XJR) remain structural laggards. Overall, sector rotation continues to support a market led by defensive and quality-oriented industries, although improving participation from Technology, Financials, and Utilities suggests market leadership may become increasingly broad-based in the weeks ahead.

 Nov 10, 2026
 Please wait processing your request...