
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
• Franco-Nevada pioneered and popularized the gold royalty and streaming business model.
• The asset-light structure means the company avoids direct mining and cost-overrun risk.
• A broad, diversified portfolio spreads exposure across many mines, operators, and commodities.
• FNV typically maintains a strong balance sheet and a track record of dividend growth.
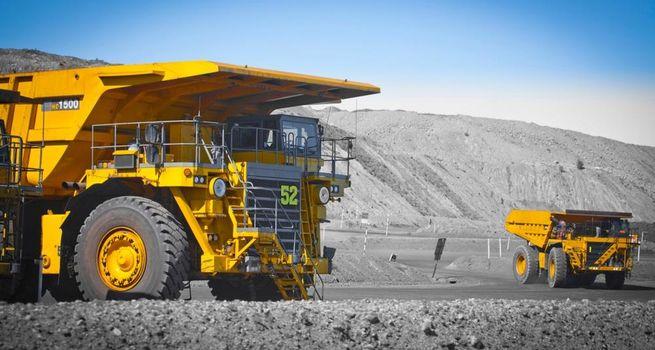
Franco-Nevada Corporation (NYSE:FNV) occupies a special place in the precious-metals landscape. Rather than digging ore and managing the unpredictable economics of operating mines, it collects revenue from royalties and streaming agreements tied to assets run by others. This model, which the company helped pioneer and refine, has made it a favorite among investors who want gold exposure without the operational headaches that plague traditional miners. Over the years, Franco-Nevada has built a reputation for steady growth, financial resilience, and a portfolio so diversified that no single mine dominates its fortunes. Yet no business is immune to challenges, and the company has faced its own tests, including disruptions at key assets. The enduring question is whether FNV remains one of the best vehicles for gaining exposure to gold, or whether changing circumstances have altered its appeal.
Understanding the answer requires examining how the royalty model works, what makes Franco-Nevada distinctive, and which forces shape its trajectory.
Company Overview
Franco-Nevada is a royalty and streaming company focused primarily on gold, though its portfolio extends to other precious metals and a range of additional commodities, including energy interests. Instead of operating mines, it provides upfront capital to mining companies in exchange for the right to receive a percentage of future production or revenue, or to purchase a portion of metal output at a predetermined price. This asset-light structure means Franco-Nevada does not bear the direct costs of mining, such as labor, fuel, and equipment, nor the capital expenditure required to build and sustain operations. Its revenue scales with production and metal prices at the underlying mines, while its costs remain comparatively fixed and modest. The company holds a large and diversified collection of interests across numerous assets, operators, and jurisdictions worldwide.
This breadth reduces reliance on any single mine and provides exposure to exploration upside, since new discoveries on royalty-covered ground can add value at no extra cost to Franco-Nevada.
Why the Stock Is in Focus
Franco-Nevada consistently attracts attention because its business model offers a distinctive risk-reward profile within the precious-metals sector. Investors are drawn to the idea of participating in gold's upside while sidestepping much of the operational and cost risk that burdens conventional miners. During periods of rising metal prices, the company's revenue can grow without a corresponding rise in costs, expanding margins in a way that operating miners struggle to match. The stock also features prominently in discussions about quality and resilience, given its diversified portfolio, strong balance sheet, and history of dividend increases. Periodic developments, such as new royalty and streaming acquisitions, production updates from key assets, and occasional disruptions at major mines, keep FNV in the spotlight. For income-oriented and quality-focused investors, the company's combination of growth optionality and financial strength is a recurring point of interest.
Its role as a benchmark for the royalty model ensures it remains a closely watched name whenever attention turns to gold.
Gold, Silver and Precious-Metals Market Backdrop
The backdrop for Franco-Nevada is anchored in the gold market, with additional sensitivity to silver and other commodities. Gold tends to respond to real interest rates, central-bank buying, currency movements, and geopolitical uncertainty, often serving as a store of value during periods of stress. Because Franco-Nevada earns revenue linked to production and prices at the mines underlying its royalties and streams, rising gold prices generally lift its top line while its costs stay relatively contained. Silver and other precious metals contribute additional exposure, and the company's energy interests introduce a further dimension tied to separate commodity dynamics. The royalty model's appeal often grows during volatile or uncertain markets, when investors seek gold exposure with reduced operational risk. At the same time, the company is not immune to weakness in metal prices, which can pressure revenue.
Watching the broad precious-metals cycle, alongside production trends at major underlying assets, is essential to understanding how the macro environment shapes Franco-Nevada's financial performance over time.
Key Catalysts Driving Investor Interest
Several catalysts can move Franco-Nevada and sustain interest in the stock. Metal prices are central, since higher gold and silver prices flow through to revenue with minimal cost offset, amplifying margins. Production trends at the mines underlying the company's royalties and streams are equally important, as ramp-ups, expansions, or disruptions directly affect revenue. New royalty and streaming acquisitions represent a key growth catalyst, allowing Franco-Nevada to deploy capital into fresh interests that expand and diversify its portfolio. Exploration success on royalty-covered ground can add value at no additional cost, providing optionality that operating miners cannot replicate as cheaply. The company's dividend policy and track record of increases attract income-focused investors and can support sentiment. Balance-sheet strength enables it to pursue opportunities even in difficult markets.
Conversely, disruptions at significant assets can serve as negative catalysts, reminding investors that the royalty model, while resilient, is not entirely insulated from the operational realities of the mines on which it depends.
Financial and Valuation Considerations
Valuing Franco-Nevada differs from valuing a traditional miner because of its asset-light structure and high margins. The company typically generates strong cash flow relative to revenue, since it avoids the heavy operating and capital costs of mining. Analysts often examine metrics such as price-to-cash-flow, the diversity and quality of the underlying asset base, and the durability of revenue streams across commodity cycles. Because the royalty model carries lower operational risk, the stock frequently commands a premium valuation compared with operating miners, reflecting its resilience, diversification, and growth optionality. Balance-sheet strength is a hallmark, with the company generally maintaining low debt and ample liquidity to fund acquisitions. Dividend growth adds to the appeal for income-oriented investors. Rather than focusing on a single multiple, it is more instructive to consider how Franco-Nevada's portfolio breadth, cost structure, and capital discipline position it across a range of precious-metals environments.
The premium it carries reflects perceived quality, though it also means expectations are elevated.
Growth Outlook and Project Pipeline
Franco-Nevada's growth outlook rests on two main pillars: the organic performance of its existing portfolio and the addition of new royalty and streaming interests. Organically, the company benefits as mines underlying its agreements ramp up production, expand, or extend their lives, and as exploration on royalty-covered ground yields new ounces at no extra cost. This embedded optionality is a defining feature of the model. On the acquisition side, Franco-Nevada deploys its capital and balance-sheet strength to secure new interests, often funding miners' development in exchange for long-term revenue rights. The pace and quality of these deals shape the company's growth trajectory. Its diversified approach spreads exposure across precious metals and other commodities, providing multiple avenues for expansion. The pipeline's success depends on disciplined capital allocation, sound deal selection, and the continued health of the operators and mines it relies upon.
Investors assessing the growth story typically focus on whether the company can keep adding high-quality interests while preserving its financial strength and diversification.
Major Risks Investors Should Watch
Despite its resilient model, Franco-Nevada is not without risks. Commodity-price risk remains fundamental, as falling gold, silver, or other commodity prices can reduce revenue even though the company's costs stay low. Counterparty and operational risk at the underlying mines is significant; because Franco-Nevada depends on operators it does not control, disruptions, suspensions, or closures at key assets can materially affect revenue, as the company's history has demonstrated. Concentration in any single large royalty or stream can amplify this exposure. Jurisdictional and political risk applies indirectly, since the mines underlying its interests span many countries with varying regulatory and political environments. Acquisition risk is also relevant, as overpaying for interests or misjudging an asset's prospects could erode value. The stock's premium valuation means it may be sensitive to shifts in sentiment or disappointments relative to high expectations.
Finally, broad market and macro forces affecting precious metals can pressure the shares. Monitoring both portfolio health and macro conditions is essential.
What Could Drive the Stock Next
The path ahead for Franco-Nevada is likely to be shaped by metal prices, portfolio performance, and capital deployment. A sustained rise in gold prices, fueled by monetary uncertainty, central-bank demand, or geopolitical tension, could lift revenue and reinforce the stock's appeal as a quality gold proxy. Strong production from the mines underlying its royalties and streams, along with the recovery or resolution of any disrupted assets, would support the fundamental case. New, well-priced royalty and streaming acquisitions could expand and diversify the portfolio, providing fresh growth. Continued dividend increases and balance-sheet strength may bolster sentiment among quality- and income-focused investors. Conversely, weaker commodity prices, disruptions at significant assets, or disappointments relative to the stock's premium valuation could weigh on the shares.
Because the royalty model is tied to the broader precious-metals cycle, Franco-Nevada's trajectory will reflect both macro tides and the granular health of its underlying interests. Investors should track both dimensions closely.
Conclusion
Franco-Nevada remains one of the most distinctive names in the precious-metals world, built on a royalty and streaming model that lets it participate in gold's upside while sidestepping much of the operational and cost risk that challenges traditional miners. Its diversified portfolio, financial strength, and track record of dividend growth have earned it a reputation for quality and resilience, while its asset-light structure delivers high margins and embedded growth optionality. Yet the model is not immune to challenges, as disruptions at key assets, commodity-price swings, and a premium valuation all carry implications for investors. Whether FNV is still one of the best ways to play gold depends on how these forces evolve and on each investor's own priorities. For those studying the sector, Franco-Nevada offers an illuminating lesson in how financial innovation reshaped gold investing.
The central takeaway is to appreciate both its enduring strengths and the risks that accompany its premium standing.

 Nov 02, 2026
 Please wait processing your request...