
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
• Meta Platforms (NASDAQ: META) is reportedly developing a commercial AI cloud business called "Meta Compute."
• The report raises concerns that hyperscalers could increasingly compete with independent AI cloud providers.
• Nebius Group (NASDAQ: NBIS) faces additional scrutiny because Meta is also its largest customer under a multi-year capacity agreement.
• CoreWeave (NASDAQ: CRWV) continues to face valuation pressure despite analysts arguing that GPU demand remains supply constrained.
• Investors are reassessing whether independent AI cloud providers can maintain their competitive edge as hyperscalers expand their offerings.
AI Cloud Stocks Sell Off on Meta Compute Report
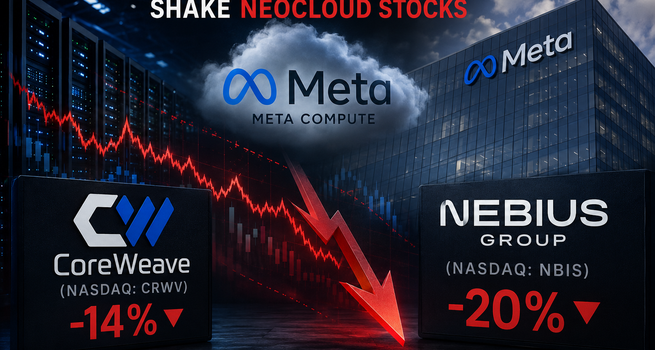
Shares of CoreWeave (NASDAQ: CRWV) and Nebius Group (NASDAQ: NBIS) came under heavy selling pressure after a Bloomberg report indicated that Meta Platforms (NASDAQ: META) is building a commercial AI cloud business aimed at monetizing excess graphics processing unit (GPU) capacity.
The reported initiative, internally referred to as "Meta Compute," would allow Meta to sell AI compute infrastructure directly to enterprise customers rather than using its massive GPU clusters exclusively for internal AI workloads.
Although the business remains in its early stages, investors immediately viewed the move as a potential shift in the competitive dynamics of the rapidly expanding AI infrastructure market.
For companies whose investment thesis centers on renting GPU capacity to AI developers and enterprises, the possibility of another hyperscale cloud provider entering the market represents a meaningful change in the long-term outlook.
Why Meta's AI Cloud Ambitions Matter
The AI infrastructure ecosystem has largely been built on the idea that hyperscalers invest enormous sums to support their own AI models while specialized "neocloud" providers supply GPU capacity to startups, enterprises, and AI developers.
Meta's reported strategy suggests that distinction may begin to disappear.
Instead of remaining solely a consumer of AI infrastructure, Meta could become a direct supplier of AI compute services.
If successful, the company would compete more directly with specialized providers such as CoreWeave (NASDAQ: CRWV) and Nebius Group (NASDAQ: NBIS), both of which have built businesses around offering high-performance GPU infrastructure optimized for generative AI workloads.
The concern is less about today's revenues and more about how investors value these businesses over the next several years.
Nebius Faces a Double Challenge
Nebius Group (NASDAQ: NBIS) experienced one of the sharpest declines because the Meta announcement introduces two separate concerns.
First, Meta could emerge as a powerful new competitor in the AI cloud market.
Second, Meta is also Nebius' largest customer through a reported multi-year infrastructure agreement worth up to $27 billion.
That creates a difficult scenario for investors to evaluate.
If Meta increasingly commercializes its own infrastructure, questions naturally arise over how much third-party AI compute capacity it may require in the future.
There is currently no indication that the existing agreement has changed. However, markets typically price in competitive risks well before they become visible in operating results.
The selloff therefore reflects uncertainty rather than evidence of deteriorating fundamentals.
Ironically, the weakness follows an exceptionally strong quarter in which Nebius reported approximately 684% year-over-year revenue growth, highlighting the robust demand environment for AI infrastructure.
CoreWeave's Premium Valuation Comes Under Pressure
CoreWeave (NASDAQ: CRWV) also extended its losses as investors reassessed the sustainability of premium valuations across the AI infrastructure sector.
The company has become one of Wall Street's most prominent AI infrastructure plays, benefiting from extraordinary demand for NVIDIA-powered GPU clusters.
However, its business model depends on maintaining pricing power in a market where supply shortages have historically favored specialized providers.
Meta's reported entry challenges that assumption.
A company capable of investing approximately $145 billion in capital expenditures during 2026 possesses financial resources that few independent cloud providers can match.
That does not necessarily mean CoreWeave will lose customers.
Instead, investors are questioning whether pricing power could become more competitive if another hyperscaler begins selling AI compute commercially.
The concerns also arrive as investors continue monitoring insider selling activity and the company's sizeable liability position, adding another layer of caution to an already richly valued stock.
Despite the selloff, some analysts remain constructive.
Rosenblatt analyst John McPeake recently reiterated a Buy rating and maintained a $250 price target, arguing that industry-wide GPU shortages remain significant enough for multiple AI cloud providers to coexist successfully.
What the Market Is Really Pricing In
The sharp declines in CoreWeave and Nebius do not necessarily imply that demand for AI computing is weakening.
Instead, investors are reassessing who ultimately captures the economic value created by that demand.
One of the biggest investment debates over the coming decade is whether specialized AI cloud providers will continue occupying an attractive niche or whether hyperscalers eventually internalize much of that opportunity.
Meta's reported initiative has brought that debate back into focus.
If every major technology company eventually commercializes excess GPU infrastructure, specialized providers may face greater pricing competition than investors had previously expected.
Conversely, if AI demand continues to outpace available compute capacity, there may still be sufficient room for both hyperscalers and independent operators to grow.
That uncertainty explains why valuation multiples can change dramatically even when company-specific fundamentals remain intact.
Outlook
The latest selloff appears to reflect a headline-driven reassessment of future competition rather than a deterioration in operating performance at either company.
CoreWeave (NASDAQ: CRWV) and Nebius Group (NASDAQ: NBIS) remain exposed to one of the fastest-growing segments of the technology industry, supported by unprecedented investment in AI infrastructure worldwide.
The key question for investors is whether Meta Compute evolves into a large-scale commercial cloud platform or remains a limited initiative designed primarily to monetize excess internal capacity.
Until there is greater clarity, competitive headlines are likely to remain a major driver of volatility across the AI cloud sector.

 Nov 06, 2026




 Please wait processing your request...