
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
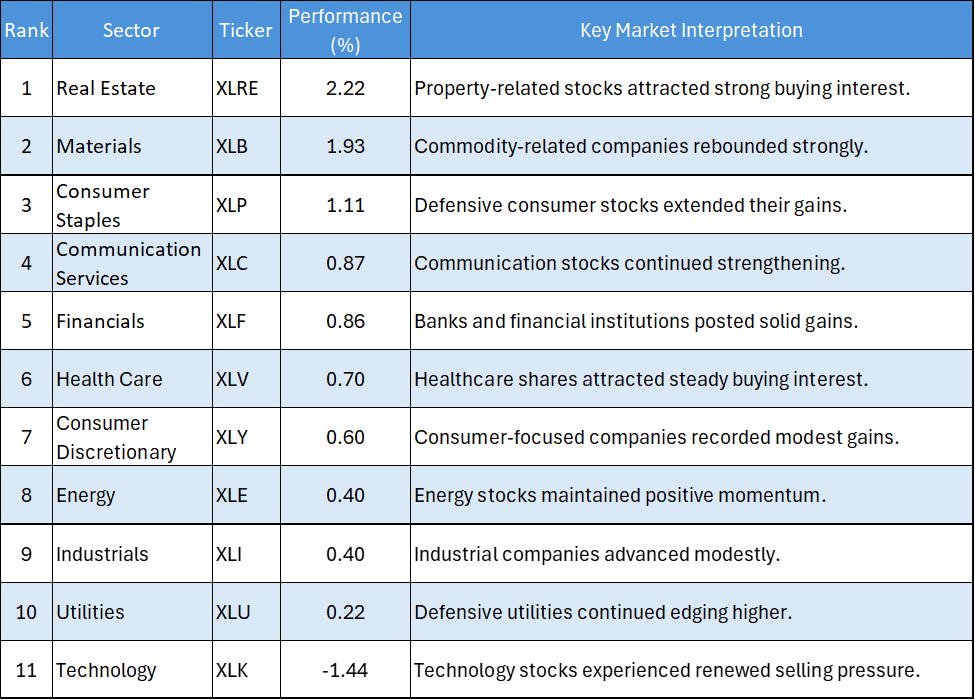
- Real Estate Leads the Market: Real Estate (XLRE) surged 2.22%, making it the strongest-performing sector as investors rotated into property-related companies.
- Materials Posts Strong Gains: Materials (XLB) climbed 1.93%, reflecting renewed buying interest in commodity-related stocks.
- Consumer Staples Extend Their Advance: Consumer Staples (XLP) gained 1.11%, highlighting continued demand for defensive sectors.
- Communication Services and Financials Finish Higher: Communication Services (XLC) and Financials (XLF) advanced 0.87% and 0.86%, respectively, indicating broad-based buying across several cyclical sectors.
- Technology Suffers Heavy Selling: Technology (XLK) declined 1.44%, making it the weakest-performing sector of the session.
- All Remaining Sectors End Higher: The remaining six sectors posted modest gains, reflecting a broad-based advance across the US equity market.
- Market Breadth Turns Decisively Positive: Ten of the eleven sectors finished higher, signalling widespread investor participation.
The US equity market delivered a broadly positive trading session on 24 July 2026, with investors favouring Real Estate, Materials, Consumer Staples, and Communication Services, while Technology was the only sector to finish in negative territory. The broad participation across cyclical and defensive sectors suggests improving investor sentiment, although continued weakness in Technology indicates that buying interest remains selective within growth-oriented industries. Overall, the session reflected healthy market breadth as capital flowed into most sectors across the market.
Daily US Sector Performance Summary
Key Market Themes
Real Estate and Materials Lead the Advance
- Real Estate (XLRE) delivered the strongest performance of the session, rising 2.22%. The strong advance suggests investors increased exposure to property-related companies, reinforcing confidence in interest rate-sensitive sectors.
- Materials (XLB) climbed 1.93%, marking a strong rebound following the previous session's weakness. The gain indicates renewed optimism towards mining and commodity-related companies as investors rotated back into cyclical sectors.
Defensive and Cyclical Sectors Broadly Strengthen
- Consumer Staples (XLP) gained 1.11%, reflecting continued demand for defensive consumer companies despite improving risk appetite across broader equity markets.
- Communication Services (XLC) advanced 0.87%, while Financials (XLF) added 0.86%, suggesting investors continued rebuilding exposure to communication and banking stocks.
- Health Care (XLV), Consumer Discretionary (XLY), Energy (XLE), Industrials (XLI), and Utilities (XLU) all recorded gains, highlighting the broad-based nature of the market advance.
Technology Remains the Market Laggard
- Technology (XLK) declined 1.44%, making it the only sector to finish lower. The weakness suggests investors continued taking profits in large-cap technology stocks despite the constructive tone across the broader market.
- The divergence between Technology and the remaining sectors indicates that market leadership broadened beyond growth stocks, with investors increasingly favouring value-oriented, cyclical, and defensive industries.
Bottom Line
The US equity market posted a strong and broad-based advance on 24 July 2026, with Real Estate, Materials, and Consumer Staples leading the gains while Technology remained the sole weak spot. The fact that ten of the eleven sectors finished higher suggests investor confidence improved significantly, with buying interest extending across both cyclical and defensive industries.
Looking ahead, continued leadership from Real Estate, Materials, and Financials would reinforce the market's constructive outlook. However, investors should monitor whether Technology stabilises, as renewed participation from the sector would likely provide additional support for a broader and more sustainable market rally.


 Nov 04, 2026





 Please wait processing your request...