
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
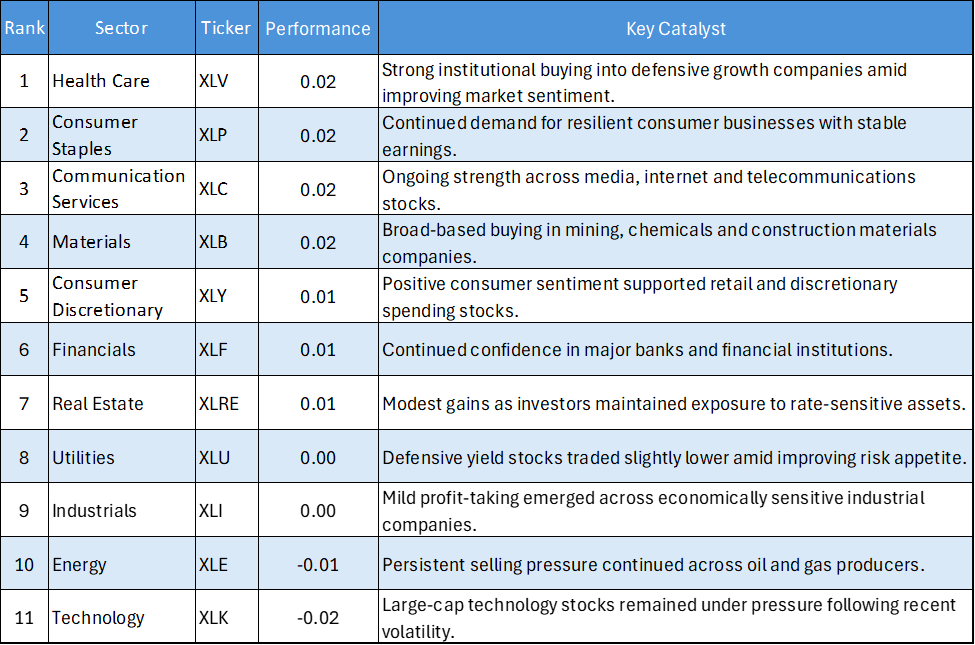
- Health Care Outperforms the Market: Health Care (XLV) surged 2.36%, making it the strongest-performing sector as investors increased exposure to defensive growth companies.
- Consumer Staples and Communication Services Advance: Consumer Staples (XLP) gained 1.99%, while Communication Services (XLC) rose 1.87%, reflecting continued demand for defensive and communication-related stocks.
- Materials and Consumer Discretionary Post Solid Gains: Materials (XLB) climbed 1.85%, while Consumer Discretionary (XLY) added 1.48%, signalling renewed buying across cyclical sectors.
- Financials Continue to Provide Support: Financials (XLF) advanced 1.27%, extending their recent strength as investors maintained confidence in major US banks.
- Technology Becomes the Weakest Sector: Technology (XLK) declined 1.84%, making it the poorest-performing sector as selling pressure persisted across large-cap technology stocks.
- Energy Also Remains Under Pressure: Energy (XLE) fell 1.35%, extending its recent weakness despite strength across most other sectors.
- Market Breadth Remains Constructive: Eight of the eleven major sectors finished higher, highlighting resilient investor sentiment despite continued weakness in Technology and Energy.
The US equity market delivered another constructive session on 28 July 2026, with defensive sectors leading the advance. Health Care recorded the strongest gain, while Consumer Staples, Communication Services, Materials and Consumer Discretionary also posted robust performances. Financials continued to provide support for the broader market, whereas Technology and Energy remained under pressure as investors rotated away from growth-oriented technology companies and energy stocks. Overall, the broad participation across most sectors suggests investor sentiment remains positive despite ongoing divergence in sector performance.
Daily US Sector Performance Summary
Key Market Themes
Health Care Leads Defensive Buying
- Health Care (XLV) surged 2.36%, making it the strongest-performing sector of the session. The strong advance suggests investors rotated into defensive growth companies as confidence improved across the broader market.
- Consumer Staples (XLP) gained 1.99%, reinforcing continued demand for businesses with resilient earnings and stable cash flows during an uncertain macroeconomic environment.
Communication Services and Financials Continue to Strengthen
- Communication Services (XLC) climbed 1.87%, extending its recent momentum as investors continued accumulating media, internet and telecommunications stocks.
- Financials (XLF) rose 1.27%, reinforcing the sector's role as an important pillar of market leadership. Continued buying interest suggests investors remain confident in the earnings outlook for major US financial institutions.
Cyclical Sectors Attract Selective Buying
- Materials (XLB) advanced 1.85%, while Consumer Discretionary (XLY) gained 1.48%, reflecting improving investor confidence in economically sensitive sectors.
- Real Estate (XLRE) also finished higher, indicating selective buying across interest rate-sensitive industries despite mixed market conditions.
Technology and Energy Remain the Market Laggards
- Technology (XLK) declined 1.84%, making it the weakest-performing sector of the session. The continued weakness suggests investors remain cautious towards high-growth technology companies following recent volatility.
- Energy (XLE) also underperformed, falling 1.35%, as persistent selling pressure across oil and gas companies continued to weigh on sector performance.
- Utilities (XLU) and Industrials (XLI) posted modest declines, suggesting investors rotated away from traditional defensive yield sectors while favouring Health Care, Consumer Staples and selected cyclical industries.
Bottom Line
The US equity market extended its constructive tone on 28 July 2026, with Health Care, Consumer Staples, Communication Services and Materials leading the gains, while Technology and Energy remained under pressure. The fact that eight of the eleven sectors finished higher indicates investor sentiment remains broadly positive, although sector leadership continues to rotate away from large-cap technology and energy stocks towards defensive and selectively cyclical industries.
Looking ahead, investors will be watching whether Health Care and Consumer Staples can maintain their leadership while monitoring whether Technology and Energy can stabilise. Renewed participation from these influential sectors would likely support a broader and more balanced advance across the US equity market.


 Nov 04, 2026





 Please wait processing your request...