
 CA
 NZ
 UK
 AU
 IND

 US
 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Momentum Shifts
- Industrials (XLI) and Materials (XLB) Remain in the Leading Quadrant: Both sectors continue to exhibit strong relative strength and positive momentum, maintaining their position at the forefront of the US market.
- Technology (XLK) and Consumer Discretionary (XLY) Strengthen in Improving: Both sectors are positioned in the Improving quadrant, suggesting their relative momentum is recovering and they could move toward leadership if the trend continues.
- Health Care (XLV) Has Entered Weakening: Despite its relatively defensive characteristics, Health Care has moved into the Weakening quadrant, indicating that its relative momentum is deteriorating.
- Energy (XLE) Remains Deep in Weakening: Energy continues to show fading relative momentum despite recording the strongest daily gain of 1.48%, highlighting the divergence between short-term price performance and broader relative momentum.
- Financials (XLF) and Real Estate (XLRE) Remain in Weakening: Both sectors continue to lose momentum, suggesting that their previous relative strength is fading.
- Communication Services (XLC) and Utilities (XLU) Remain in Lagging: These sectors continue to exhibit weak relative strength and negative momentum, although their future rotation will depend on whether momentum begins to recover.
The latest Relative Rotation Graph (RRG) for 7 August 2026 indicates a mixed but increasingly selective rotation across the US equity market. Industrials and Materials continue to establish leadership, while Technology and Consumer Discretionary are showing improving relative momentum. At the same time, Health Care has moved into Weakening alongside Energy, Financials, Real Estate and Consumer Staples. The divergence between daily price performance and RRG positioning is particularly notable for Energy, which gained strongly during the latest session but remains deep in the Weakening quadrant.
Momentum Breakdown by Quadrant
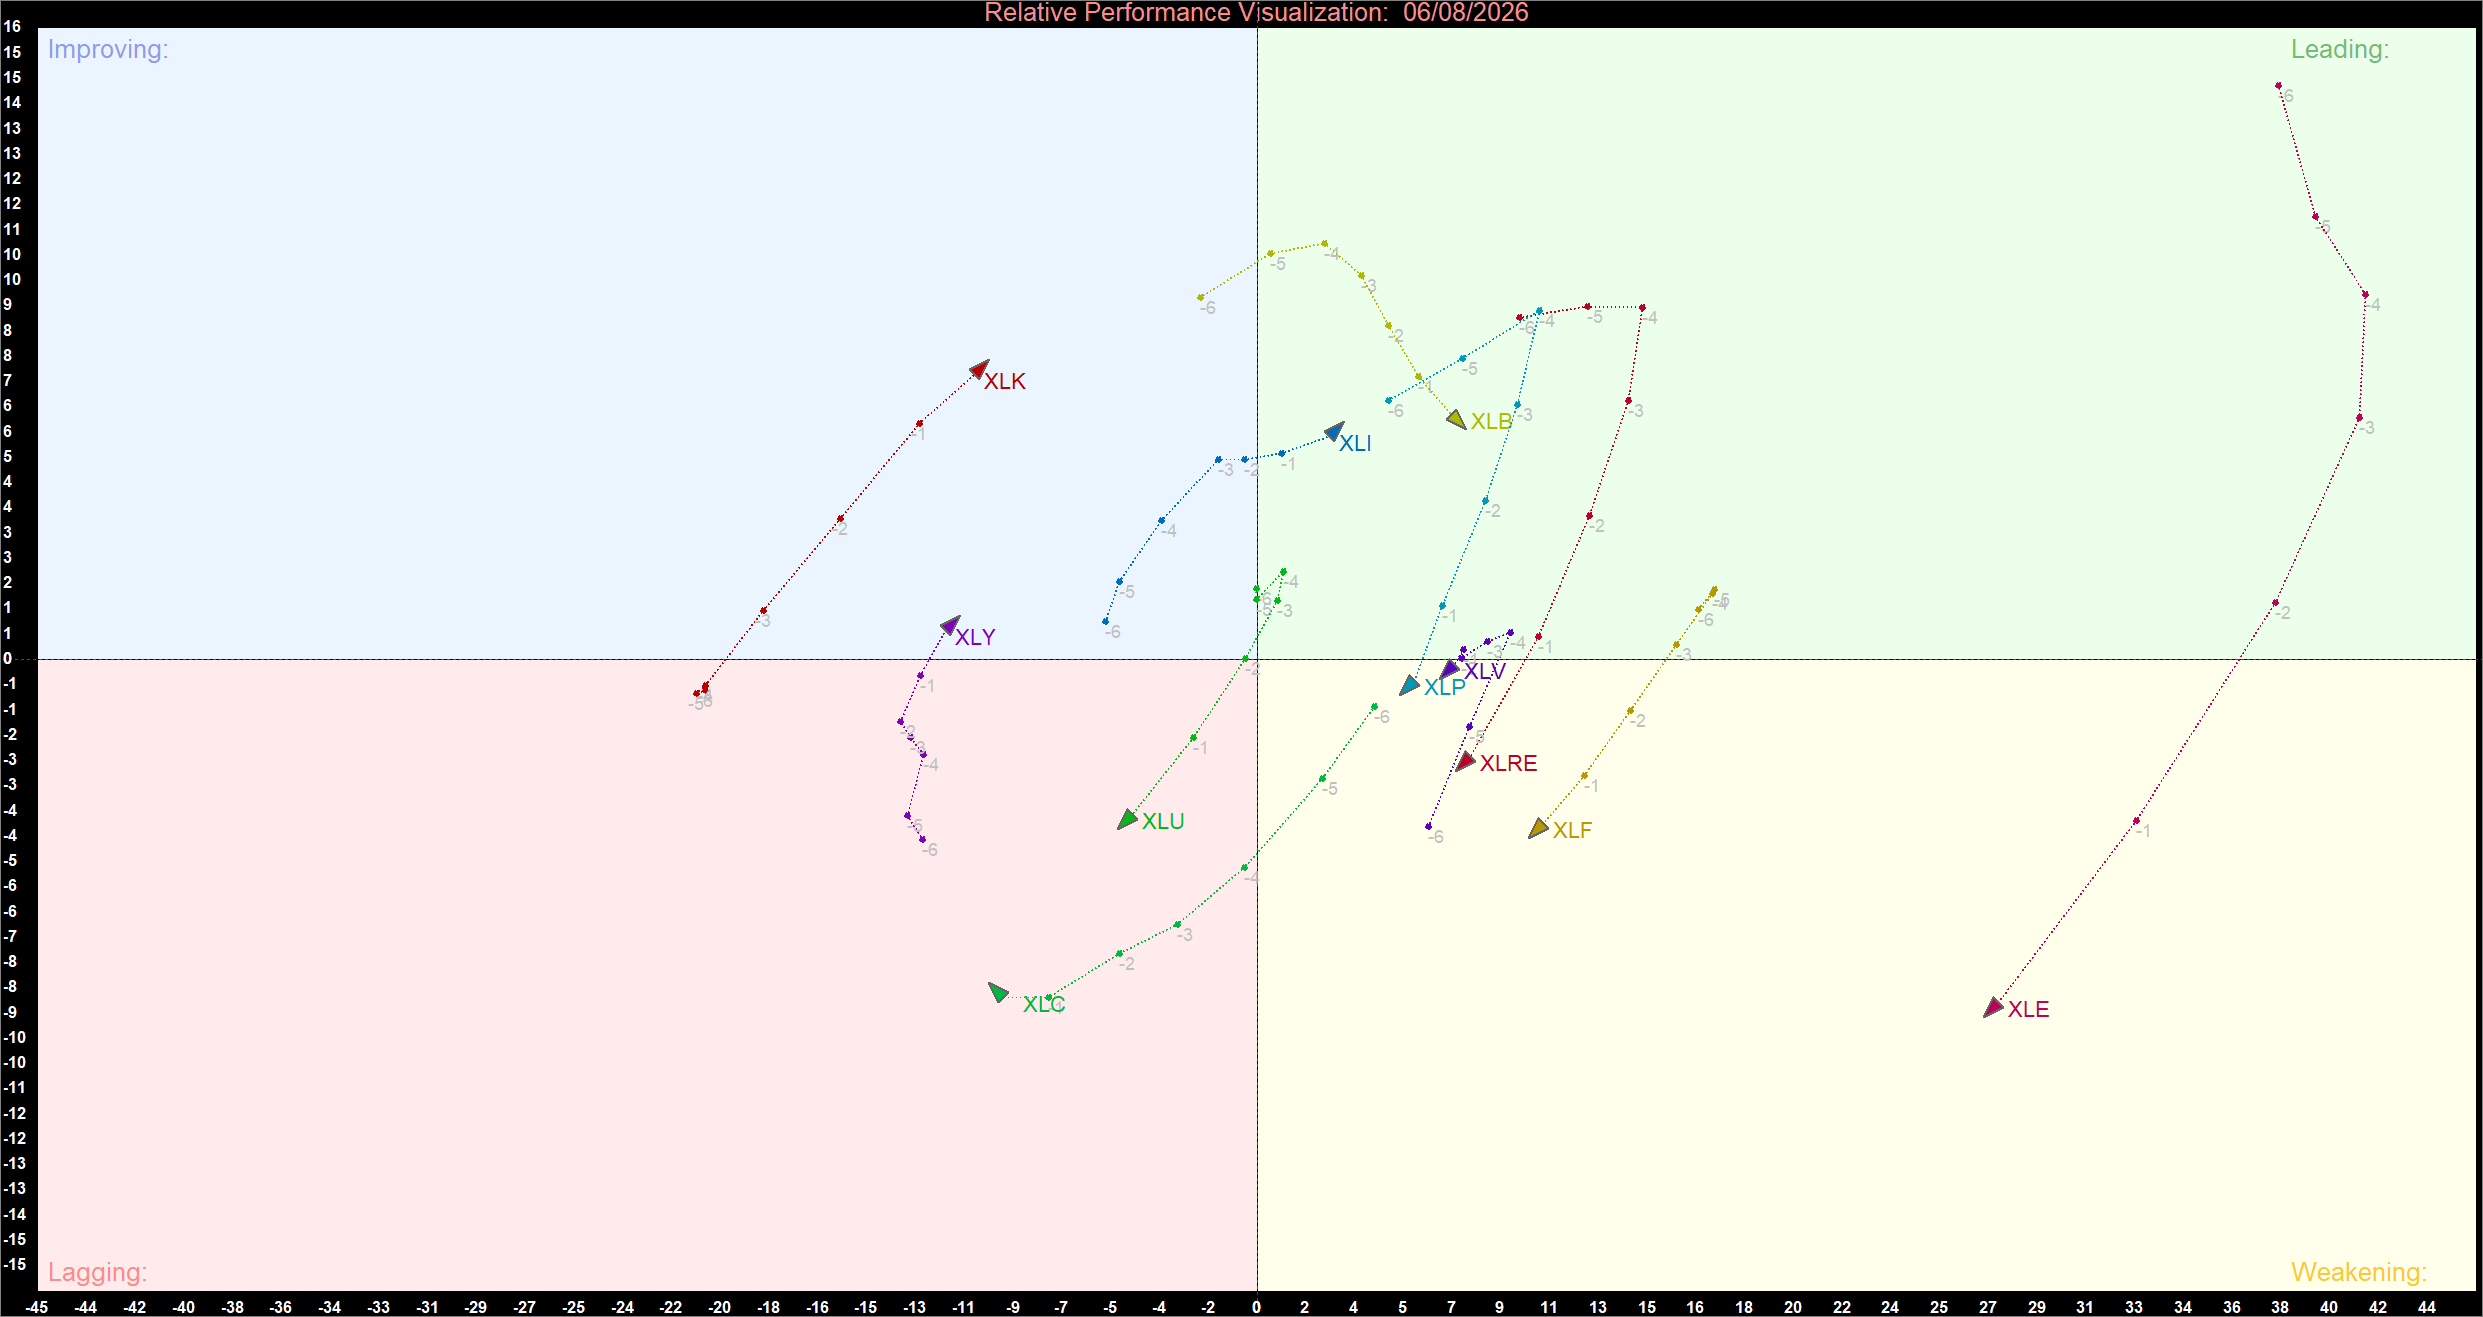
US Sector Relative Momentum Chart (at the closing price of 06/08/2026). Powered by: amibroker.com.
Leading Quadrant
- Industrials (XLI) remain firmly within the Leading quadrant, indicating strong relative strength and positive momentum. The sector's position suggests continued investor interest in economically sensitive companies despite its 0.85% decline in the latest session.
- Materials (XLB) also remain in Leading, supported by strong relative momentum. However, its 0.89% daily decline highlights the importance of distinguishing between short-term price movements and the sector's broader relative trend.
Improving Quadrant
- Information Technology (XLK) is positioned strongly within Improving, indicating that its relative momentum is recovering. Despite a modest 0.31% decline in the latest session, the sector's RRG trajectory suggests improving conditions relative to the broader market.
- Consumer Discretionary (XLY) also occupies the Improving quadrant, pointing to strengthening relative momentum. Its 0.46% decline during the latest session has not yet disrupted the broader improvement in its relative position.
Weakening Quadrant
- Health Care (XLV) has recently entered the Weakening quadrant, signalling that its relative momentum has deteriorated after previously showing stronger performance. Its modest 0.18% gain in the latest session has therefore not yet translated into improving relative momentum.
- Energy (XLE) remains deep within Weakening despite being the strongest-performing US sector in the latest session, gaining 1.48%. This divergence suggests the recent price strength has not yet been sufficient to reverse its broader deterioration in relative momentum.
- Financials (XLF) remain in Weakening, with the sector declining 0.33% in the latest session. Its position indicates fading relative momentum and reduced leadership potential.
- Real Estate (XLRE) also remains in Weakening after falling 0.86%, reflecting continued pressure on the rate-sensitive sector.
- Consumer Staples (XLP) sits in Weakening as well, although its relatively small 0.26% decline indicates greater resilience than several other sectors within this quadrant.
Lagging Quadrant
- Communication Services (XLC) remains in the Lagging quadrant despite gaining 0.28% during the latest session. The sector continues to exhibit weak relative momentum compared with the broader US market.
- Utilities (XLU) also remain in Lagging, with a 0.64% decline reinforcing its weak short-term performance. A sustained improvement in relative momentum would be required before the sector can rotate toward Improving.
Strategic Summary
The latest Relative Rotation Graph highlights a selective rotation within the US equity market, with Industrials (XLI) and Materials (XLB) maintaining their positions in the Leading quadrant. Meanwhile, Information Technology (XLK) and Consumer Discretionary (XLY) are strengthening within Improving, suggesting that growth and cyclical sectors could provide additional leadership if their relative momentum continues to improve.
At the same time, Health Care (XLV) has entered Weakening, joining Energy (XLE), Financials (XLF), Real Estate (XLRE) and Consumer Staples (XLP) in the quadrant where relative momentum is deteriorating. Communication Services (XLC) and Utilities (XLU) remain in Lagging, indicating continued relative weakness.
Overall, the latest sector rotation suggests that Industrials and Materials currently provide the strongest relative leadership, while Technology and Consumer Discretionary are the key sectors to watch for potential upward rotation. The sharp divergence between Energy's strong daily performance and its Weakening RRG position also suggests that investors should assess both short-term price action and broader relative momentum when evaluating the sustainability of sector leadership.

 Nov 09, 2026
 Please wait processing your request...