
 CA
 NZ
 UK
 AU
 IND

 US
 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Momentum Shifts
- Energy (XLE) remains the strongest leader, although its momentum continues to moderate.
- Financials (XLF) have re-entered the Leading quadrant, signalling renewed relative strength and momentum.
- Materials (XLB) remain the strongest Improving sector, while Industrials (XLI) and Utilities (XLU) have also rotated into the Improving quadrant.
- Health Care (XLV) and Communication Services (XLC) remain in Weakening, reflecting fading momentum.
- Technology (XLK) and Consumer Discretionary (XLY) continue to lag the broader market.
- Overall, sector rotation continues to favour established leaders while capital gradually shifts towards improving cyclical sectors.
The latest Relative Rotation Graph (RRG) for 29 July 2026 indicates that US market leadership remains well diversified despite continued moderation in Energy's momentum. Financials have re-entered the Leading quadrant alongside Real Estate, Consumer Staples and Energy, while Materials and Industrials continue strengthening within the Improving quadrant. Conversely, Health Care and Communication Services continue to lose momentum despite maintaining above-average relative strength, whereas Technology and Consumer Discretionary remain the weakest relative performers. Overall, sector rotation suggests institutional capital continues favouring high-quality leadership sectors while selectively accumulating industries displaying improving momentum characteristics.
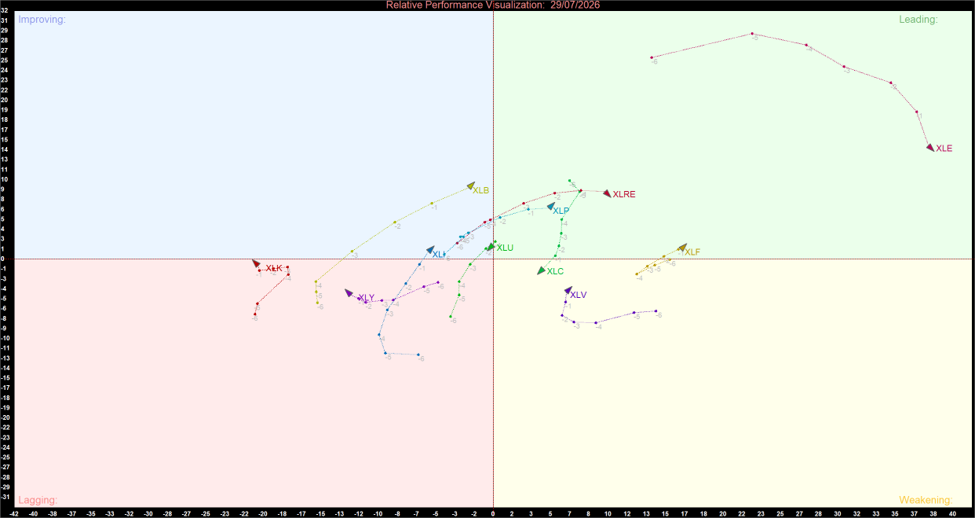
US Sector Relative Momentum Chart (at the closing price of 29/07/2026). Powered by: amibroker.com.
Momentum Breakdown by Quadrant
Leading Quadrant
- Energy (XLE) remains the market's strongest leadership sector. Although its south-easterly trajectory indicates that relative momentum continues to moderate, the sector still maintains the highest level of relative strength versus the broader market.
- Financials (XLF) have rotated back into the Leading quadrant, reflecting renewed improvements in both relative strength and momentum. The move reinforces growing institutional demand for banking and diversified financial companies.
- Real Estate (XLRE) continues to occupy the Leading quadrant, maintaining above-average relative strength despite a gradual moderation in momentum.
- Consumer Staples (XLP) remain firmly positioned in Leadership, highlighting persistent investor preference for defensive companies offering resilient earnings and stable cash flows during an uncertain macroeconomic environment.
Improving Quadrant
- Materials (XLB) remain the strongest sector within the Improving quadrant. Its steep north-easterly trajectory indicates accelerating relative momentum, positioning the sector as the leading candidate to rotate into the Leading quadrant should current momentum persist.
- Industrials (XLI) have crossed into the Improving quadrant after previously residing in Lagging. The rotation suggests relative momentum is strengthening, potentially signalling the early stages of renewed institutional accumulation in industrial and capital goods companies.
- Utilities (XLU) have also entered the Improving quadrant after recovering from recent weakness. While relative strength remains below average, improving momentum suggests the sector may continue attracting defensive capital flows.
Weakening Quadrant
- Health Care (XLV) remains within the Weakening quadrant. Although the sector continues to outperform the benchmark on a relative basis, its south-westerly rotation indicates momentum continues to deteriorate, suggesting leadership characteristics are gradually fading.
- Communication Services (XLC) has also rotated into the Weakening quadrant, reflecting moderating momentum after an extended period of relative outperformance. Continued deterioration may eventually result in a transition towards the Lagging quadrant if momentum fails to recover.
Lagging Quadrant
- Technology (XLK) remains within the Lagging quadrant despite beginning to curl higher. The improving trajectory suggests downside momentum is easing, although further improvement in both relative strength and momentum will be required before the sector can rotate into Improving.
- Consumer Discretionary (XLY) continues to occupy the Lagging quadrant, highlighting persistent relative underperformance compared with the broader market despite showing tentative signs of stabilisation.
Strategic Summary
The latest Relative Rotation Graph shows Energy (XLE) remains the market's strongest leadership sector, while Financials (XLF) have rejoined the Leading quadrant alongside Real Estate (XLRE) and Consumer Staples (XLP). Materials (XLB), Industrials (XLI) and Utilities (XLU) continue strengthening in the Improving quadrant, indicating expanding market leadership. Meanwhile, Health Care (XLV) and Communication Services (XLC) continue losing momentum, while Technology (XLK) and Consumer Discretionary (XLY) remain the weakest relative performers.

 Nov 06, 2026
 Please wait processing your request...