
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- One Sector in Leading: Technology (XLK) remains in the Leading quadrant.
- Utilities Remains Improving: XLU is the only sector in the Improving quadrant, indicating recovering relative momentum despite weak daily performance.
- Four Sectors in Weakening: Communication Services (XLC), Financials (XLF), Energy (XLE) and Health Care (XLV) are positioned in Weakening.
- Five Sectors in Lagging: Industrials (XLI), Real Estate (XLRE), Consumer Discretionary (XLY), Consumer Staples (XLP) and Materials (XLB) remain in Lagging.
- Technology Leads Daily Performance: XLK gained 1.32%, the strongest daily performance among the 11 sectors.
- Financials and Communication Services Lose Momentum: XLF gained 0.67% and XLC gained 0.99%, but both have moved into Weakening on the RRG chart.
- Market Breadth Improves: Nine of the 11 sectors recorded positive daily returns, although the RRG configuration continues to show concentrated relative leadership.
The latest US sector momentum visualization for 11 September 2026 shows one sector in Leading, one in Improving, four in Weakening and five in Lagging. The RRG configuration indicates a significant shift in sector rotation, with Technology remaining in Leading while Financials and Communication Services have moved into Weakening. Utilities remains in Improving, while Energy and Health Care also occupy the Weakening quadrant. Industrials, Real Estate, Consumer Discretionary, Consumer Staples and Materials remain in Lagging. The latest positioning highlights a market in which daily performance has improved broadly, but relative momentum remains concentrated.
Momentum Breakdown by Quadrant
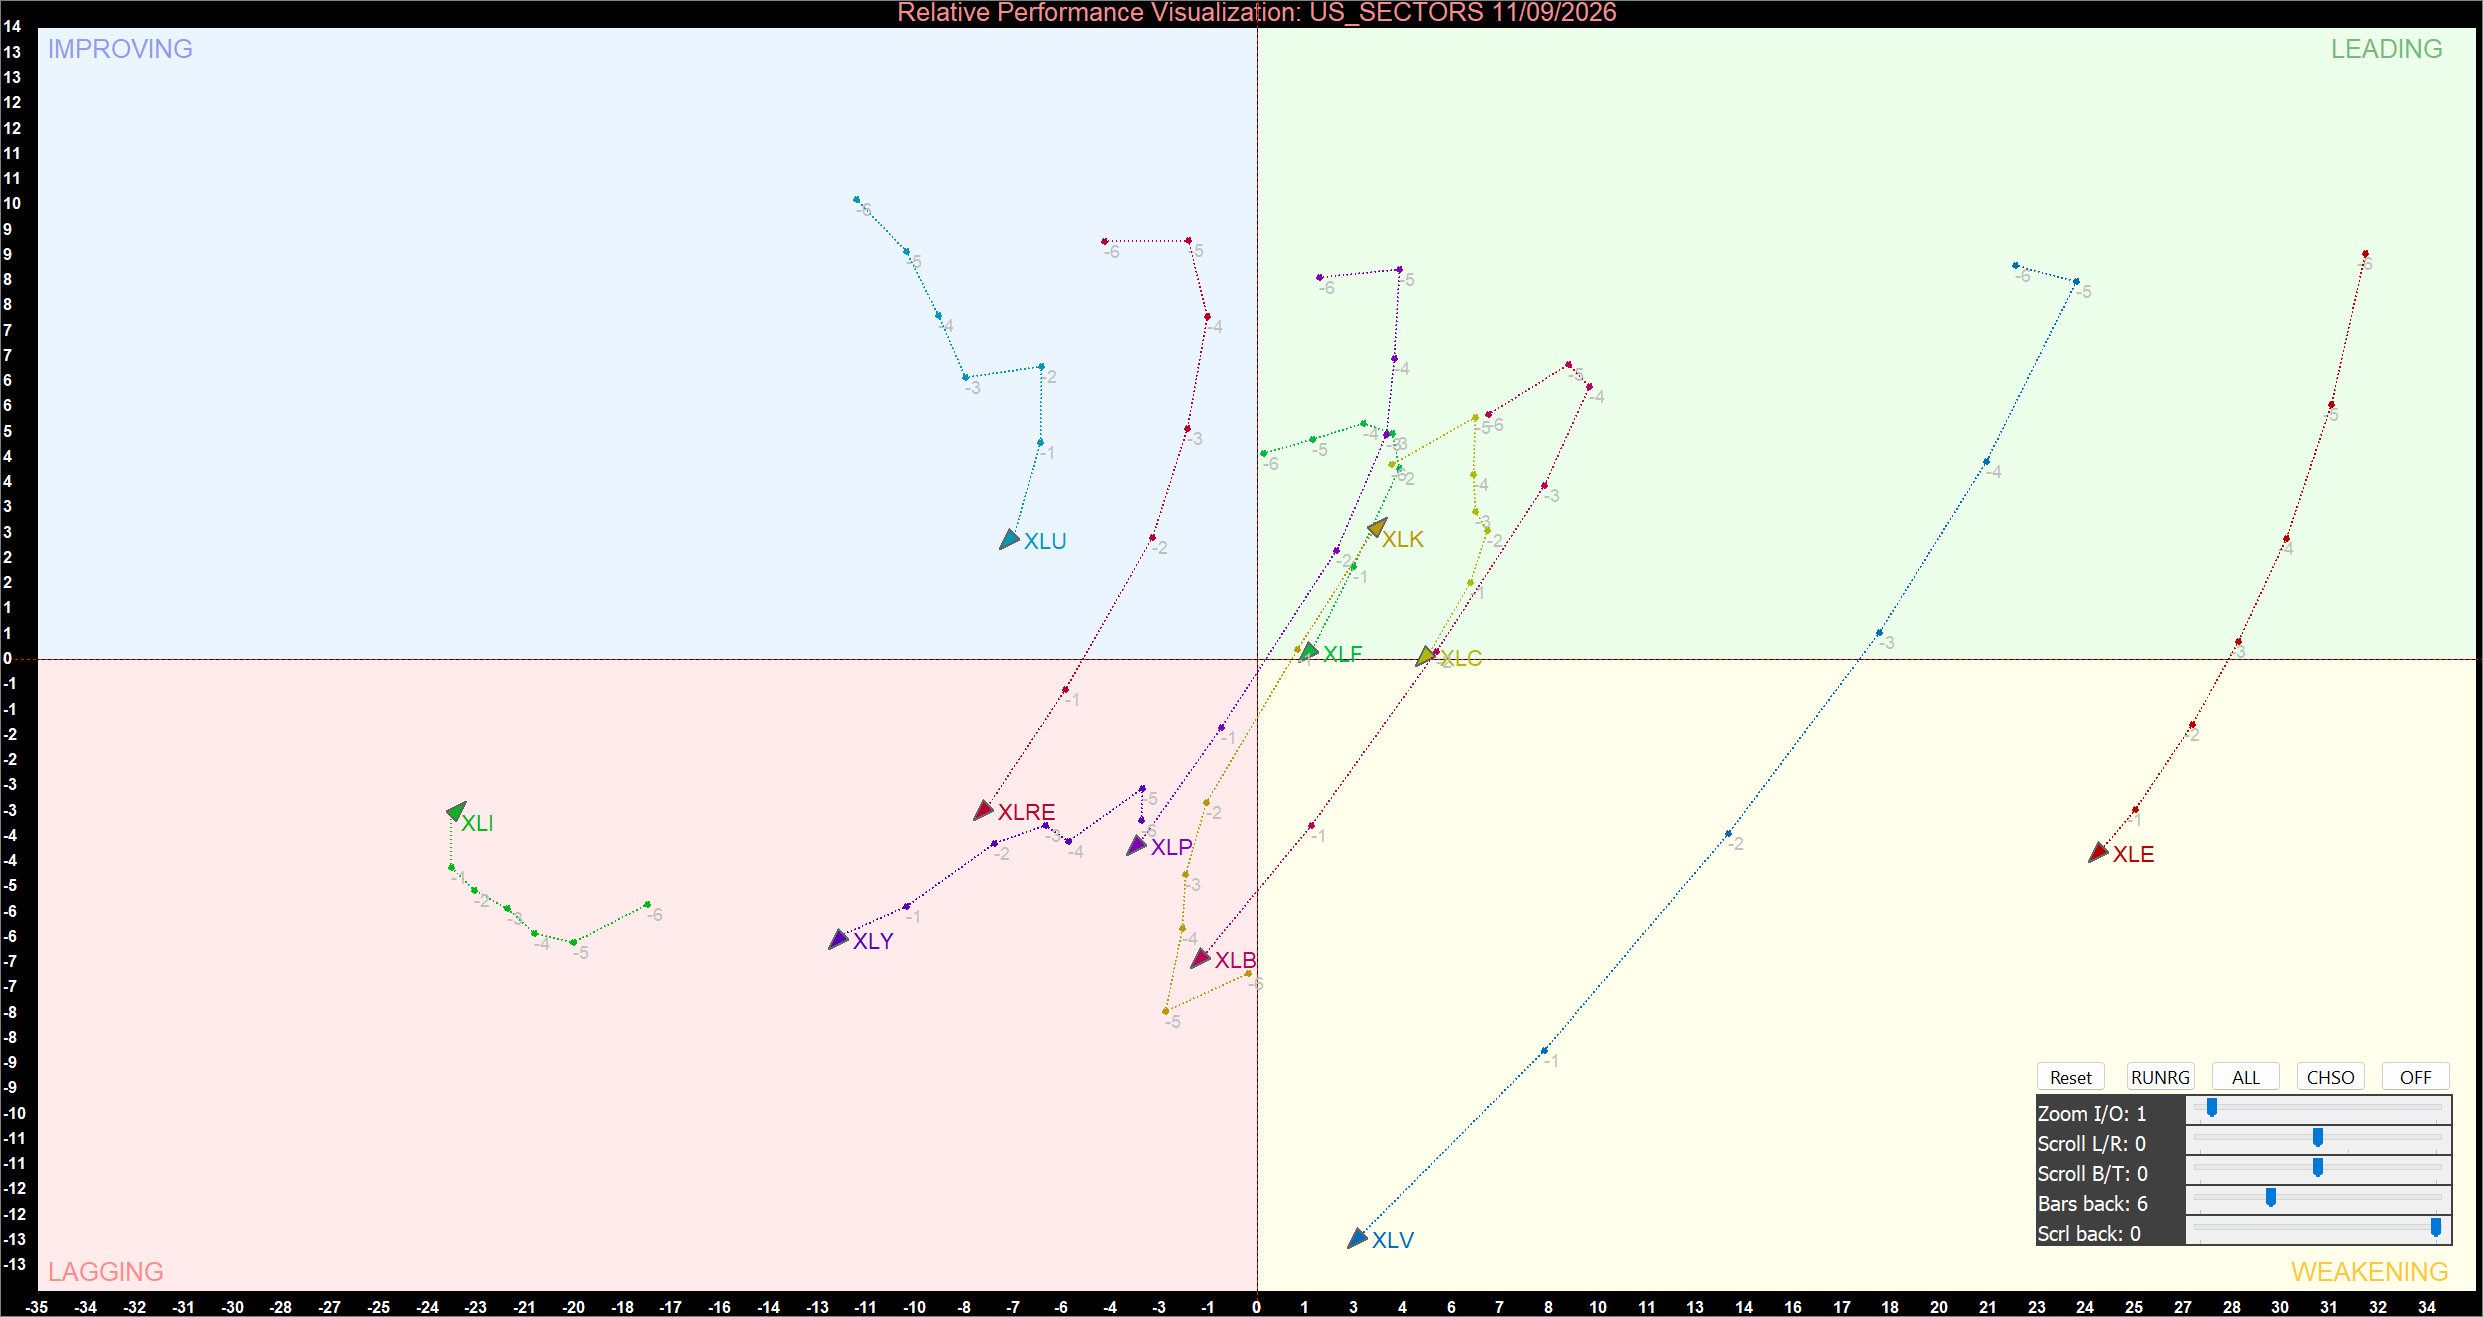
US Sector Relative Momentum Chart at the closing price of 11/09/2026. Powered by: amibroker.com.
Leading: Technology
Technology (XLK) is the only sector positioned in the Leading quadrant, indicating that it continues to demonstrate comparatively strong relative strength and momentum. The chart places XLK above the horizontal axis and to the right of the vertical axis, confirming its position within the strongest RRG classification.
Technology was also the strongest daily performer on 11 September, gaining 1.32%. The combination of positive daily performance and a Leading RRG position provides a stronger confirmation of its current market leadership.
The continued position of XLK in the upper-right quadrant is particularly important because the sector is now clearly separated from the other sectors in terms of RRG classification. If XLK continues moving further toward the upper-right, it would strengthen the evidence of sustained relative leadership. Conversely, a move back toward the horizontal axis would indicate that its momentum is beginning to moderate.
Improving: Utilities
Utilities (XLU) is the only sector positioned in the Improving quadrant. The chart places XLU to the left of the vertical axis but above the horizontal axis, indicating that its relative momentum is recovering even though its relative strength remains below the level required for Leading.
Utilities declined 0.31% during the latest session, making it the weakest daily performer among the 11 sectors. This highlights the distinction between short-term price performance and broader relative momentum. Its Improving classification reflects the direction of its relative momentum rather than its one-day return.
A continued movement toward the upper-right would increase the probability of XLU transitioning into Leading. Conversely, a move back toward the lower-left would weaken the current recovery signal and increase the possibility of a return to Lagging.
Weakening: Communication Services, Financials, Energy and Health Care
Four sectors are currently positioned in the Weakening quadrant: Communication Services (XLC), Financials (XLF), Energy (XLE) and Health Care (XLV). These sectors remain to the right of the vertical axis but below the horizontal axis, indicating relatively stronger positioning combined with deteriorating momentum.
Communication Services gained 0.99% on 11 September, making it the third-strongest daily performer among the 11 sectors. Financials also advanced 0.67%. Despite these positive daily returns, both sectors have moved into Weakening, demonstrating that RRG positioning reflects broader relative momentum rather than a single trading session.
The move of XLC and XLF into Weakening is an important development in the latest chart. Both sectors had previously been positioned in Leading, meaning their transition below the horizontal axis represents a deterioration in momentum. A continued move toward the lower-left would increase the risk of these sectors eventually entering Lagging.
Energy (XLE) gained 0.32%, while Health Care (XLV) declined 0.18%. Both remain in Weakening. Energy continues to have strong longer-term relative performance, but its current RRG position indicates that its momentum is no longer strengthening at the same pace.
The positioning of these four sectors suggests that some of the market's previously stronger areas are experiencing a loss of relative momentum. This makes their future direction particularly important for determining whether the current rotation develops into a broader change in sector leadership.
Lagging: Industrials, Real Estate, Consumer Discretionary, Consumer Staples and Materials
Five sectors are currently positioned in Lagging: Industrials (XLI), Real Estate (XLRE), Consumer Discretionary (XLY), Consumer Staples (XLP) and Materials (XLB). These sectors are located below the horizontal axis and to the left of the vertical axis, indicating weaker relative strength and momentum.
The classification is notable because all five sectors recorded positive daily returns on 11 September. Industrials gained 1.07%, Real Estate rose 0.86%, Consumer Discretionary advanced 0.89%, Consumer Staples increased 0.35%, and Materials gained 0.37%. This provides another clear example of why daily performance should not be confused with broader relative momentum.
Industrials was the second-strongest sector on a daily basis, yet it remains in Lagging. This suggests that its recent improvement in price performance has not yet been sufficient to generate a corresponding improvement in its relative momentum.
A sustained movement toward the upper-right would be required before these sectors could provide evidence of a meaningful recovery. Until then, their Lagging classification indicates that they remain relatively weaker areas of the US Equity market.
Financials and Communication Services Lose Their Leading Positions
The most important change in the latest RRG chart is the movement of Financials and Communication Services from Leading into Weakening. This represents a meaningful deterioration in their relative momentum despite both sectors recording positive returns on 11 September.
Financials gained 0.67%, while Communication Services advanced 0.99%. However, their movement below the horizontal axis indicates that their momentum relative to the broader sector group has weakened.
This change leaves Technology as the only sector in Leading. The development therefore represents a narrowing of market Leadership rather than a broad expansion of strength. Investors monitoring sector rotation should pay particular attention to whether XLF and XLC stabilize and turn higher again or continue moving toward Lagging.
Leadership Becomes More Concentrated
The overall RRG configuration shows a market with improving daily breadth but increasingly concentrated relative leadership. Nine of the 11 sectors gained during the latest session, yet only Technology remains in Leading. Meanwhile, five sectors remain in Lagging and four are in Weakening.
This divergence is important. Strong daily gains in sectors such as Industrials and Consumer Discretionary have not yet translated into a change in their RRG classifications. At the same time, Financials and Communication Services have lost momentum despite recording positive daily returns.
The structure therefore suggests that the current market rotation is still developing. Technology remains the principal source of relative leadership, while Utilities is attempting to improve and several formerly stronger sectors are losing momentum.
Strategic Summary
The latest US sector RRG presents a mixed momentum environment, with Technology positioned in Leading, Utilities in Improving, Communication Services, Financials, Energy and Health Care in Weakening, and Real Estate, Consumer Staples, Industrials, Consumer Discretionary and Materials in Lagging.
The most significant development is the movement of Financials and Communication Services from Leading into Weakening. Their positive daily returns demonstrate that RRG positioning reflects broader relative momentum rather than one-day price movements. Technology remains the only sector in Leading and also recorded the strongest daily gain of 1.32%, reinforcing its current leadership.
At the same time, Utilities remains the only Improving sector, while Energy and Health Care continue to lose momentum within Weakening. Industrials, Real Estate, Consumer Discretionary, Consumer Staples and Materials remain in Lagging despite all recording positive returns during the latest session.
Overall, the latest configuration points to increasingly concentrated sector leadership. The key developments to monitor in the next sessions are whether Technology can maintain its Leading position, whether Utilities can advance toward Leading, and whether Financials and Communication Services can recover or continue moving toward Lagging. The direction of these rotations will help determine whether the current sector momentum structure develops into a broader shift in US equity leadership.


 Nov 03, 2026
 Please wait processing your request...