
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
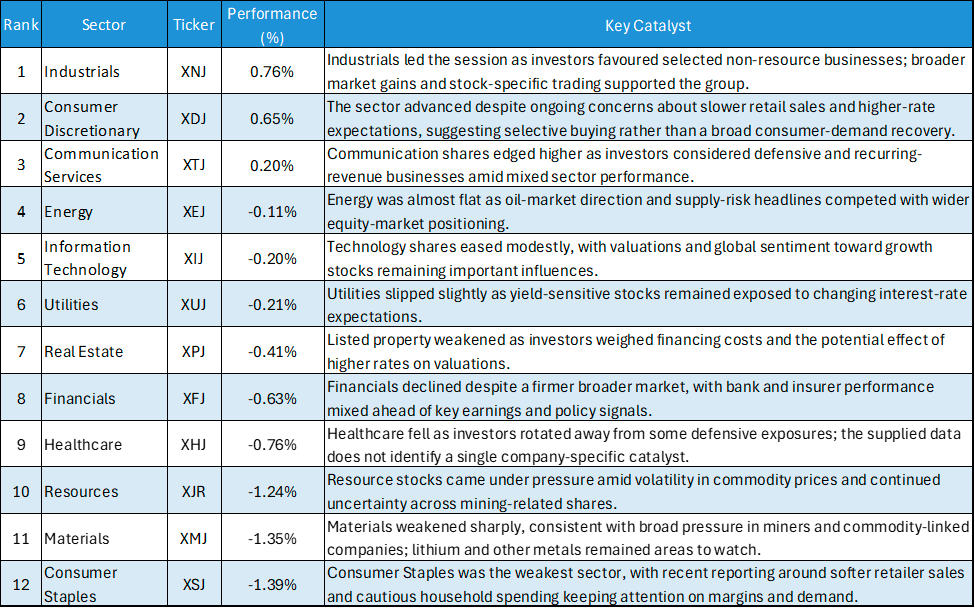
- Industrials (ASX:XNJ) led the supplied sector indices, rising 0.76%, followed by Consumer Discretionary (ASX:XDJ), up 0.65%.
- Communication Services (ASX:XTJ) advanced 0.20%, while Energy (ASX:XEJ) edged down 0.11% and Information Technology (ASX:XIJ) slipped 0.20%.
- Utilities (ASX:XUJ), Real Estate (ASX:XPJ) and Financials (ASX:XFJ) fell 0.21%, 0.41% and 0.63%, respectively.
- Healthcare (ASX:XHJ) declined 0.76%, while Resources (ASX:XJR) lost 1.24% and Materials (ASX:XMJ) dropped 1.35%.
- Consumer Staples (ASX:XSJ) was the weakest supplied sector, falling 1.39%, highlighting pressure across defensive consumer and commodity-linked shares.
Australian equities recorded a mixed sector session on Monday, 2 November, with the supplied data showing a narrow Leadership group and broader weakness across the lower-ranked sectors. Industrials and Consumer Discretionary outperformed, while Communication Services also finished higher. Losses across Resources, Materials and Consumer Staples were more pronounced, indicating that strength was selective rather than market-wide. The 2.15-percentage-point gap between the best and weakest sectors underlines the uneven distribution of investor demand.
Daily ASX Sector Performance Summary
Industrials and Consumer Discretionary Lead
Industrials was the strongest sector in the supplied figures, gaining 0.76%. The advance points to relative resilience in selected industrial businesses, although a single session cannot establish a durable improvement in Earnings expectations. Company-specific developments and Demand trends across transport, infrastructure and services remain important to the sector’s outlook.
Consumer Discretionary followed with a 0.65% gain. The positive result came against a backdrop of concern about slowing retail sales and expectations that interest rates could remain restrictive. Recent market commentary has highlighted pressure on consumer-facing stocks, including weakness following cautious trading updates. The sector’s gain therefore suggests selective buying, but not necessarily a broad recovery in household spending. Communication Services rose 0.20%, while Energy was nearly unchanged at -0.11%.
Resources, Materials and Staples Weigh on Performance
The largest declines were concentrated in Consumer Staples, Materials and Resources. Consumer Staples fell 1.39%, the weakest supplied sector, as investors continued to assess the outlook for household budgets, supermarket competition and retailer margins. Recent reporting on softer sales and cautious consumer demand has reinforced scrutiny of earnings quality across consumer-facing businesses.
Materials dropped 1.35%, while Resources declined 1.24%. The two sectors’ weakness points to pressure across commodity-linked shares, although the supplied daily data does not identify a single event responsible for the moves. Commodity prices, demand expectations from major markets, currency movements and company-specific production updates can all influence these groups. The split between Energy, which was only modestly lower, and mining-related sectors also shows that commodity exposures did not move uniformly.
Sector Rotation Remains Selective
Financials fell 0.63%, Real Estate lost 0.41%, and Utilities declined 0.21%. These moves are consistent with a cautious approach to rate-sensitive assets, where financing costs, bond yields and policy expectations can affect valuations. Healthcare dropped 0.76%, while Information Technology eased 0.20%, leaving only three of the twelve supplied indices in positive territory alongside Industrials and Consumer Discretionary.
The key distinction for investors is between daily price movements and a sustained change in fundamentals. Follow-through in Industrials and Consumer Discretionary would require confirmation from company updates and demand indicators. For Materials and Resources, commodity-price direction and producer guidance remain central. Consumer Staples will be sensitive to sales volumes, pricing power and margins, while rate expectations may continue to shape Real Estate, Utilities and Financials.
Bottom Line
Industrials led ASX sector performance on 2 November 2026, rising 0.76%, followed by Consumer Discretionary at 0.65% and Communication Services at 0.20%. Consumer Staples was weakest at -1.39%, with Materials down 1.35% and Resources falling 1.24%. The session reflected selective strength rather than a broad-based advance. Investors will be watching upcoming company updates, consumer-demand signals, commodity prices and interest-rate expectations to determine whether the leaders can sustain their relative strength.


 Nov 03, 2026

 Please wait processing your request...