
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Two Sectors in Leading: Communication Services (XLC) and Technology (XLK) remain positioned in the Leading quadrant.
- One Sector in Improving: Industrials (XLI) has moved into the Improving quadrant.
- One Sector in Weakening: Energy (XLE) remains positioned in Weakening.
- Seven Sectors in Lagging: Financials, Health Care, Consumer Discretionary, Consumer Staples, Real Estate, Materials and Utilities remain in Lagging.
- Technology Maintains Leadership: XLK remains firmly positioned in the Leading quadrant with a strong relative momentum profile.
- Industrials Show Improvement: XLI is now above the horizontal axis, indicating improving relative momentum.
- Energy Requires Monitoring: XLE remains in Weakening, retaining relatively stronger positioning but losing momentum.
- Broad Lagging Group: Seven of the 11 US sectors remain in Lagging, showing that momentum improvement has not yet become broad-based.
The latest US sector momentum visualization for 18 September 2026 shows a concentrated but gradually changing momentum structure. Communication Services (XLC) and Technology (XLK) remain in the Leading quadrant, while Industrials (XLI) has moved into Improving. Energy (XLE) remains in Weakening, and seven sectors are positioned in Lagging. Compared with the previous configuration, the emergence of XLI in Improving represents an important change, suggesting that relative momentum is beginning to strengthen in at least one part of the broader market.
Momentum Breakdown by Quadrant
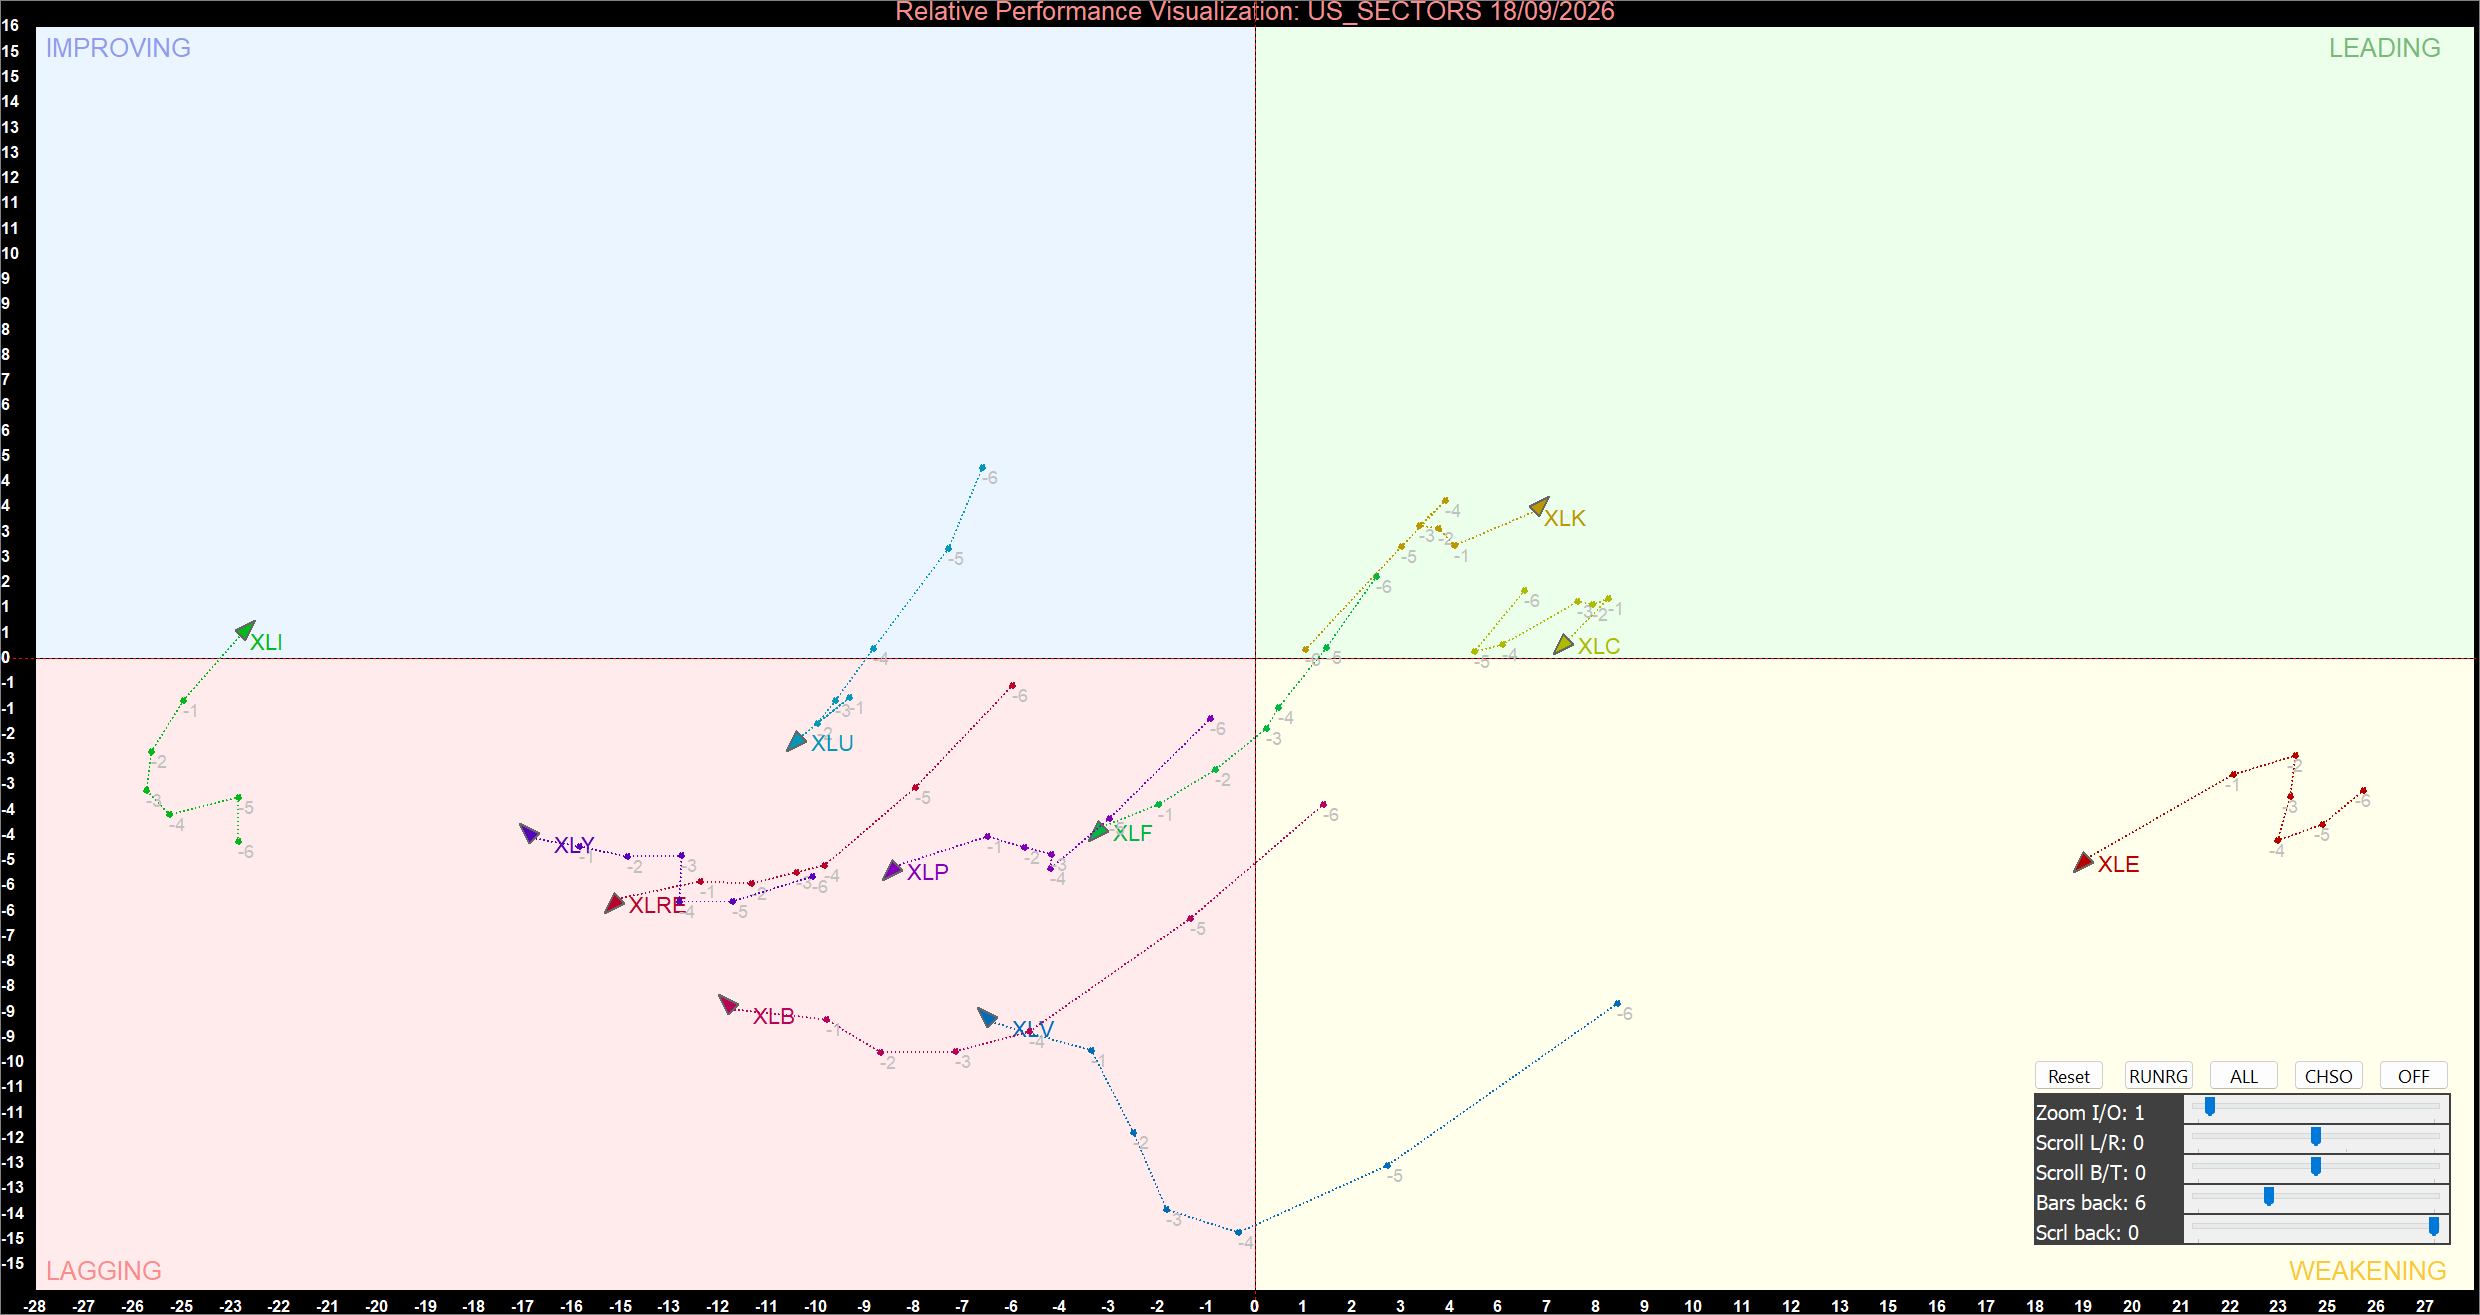
US Sector Relative Momentum Chart (at the closing price of 21/09/2026). Powered by: amibroker.com.
Leading: Communication Services and Technology
Communication Services (XLC) and Information Technology (XLK) remain the two sectors positioned in the Leading quadrant. Their locations above and to the right of the central axes indicate comparatively stronger relative strength and momentum than the majority of sectors in the universe.
Technology, represented by XLK, remains particularly well positioned in the upper-right portion of the chart. Its trajectory indicates that relative momentum remains stronger than most other sectors. Communication Services is also firmly above the horizontal axis, although its position is closer to the centre than XLK.
The continued Leading classification does not necessarily imply that these sectors must record the strongest daily performance. Rather, the RRG measures relative strength and momentum over the broader observation period. A sector can experience short-term fluctuations while remaining in Leading if its relative momentum continues to outperform the broader sector universe.
Improving: Industrials
Industrials (XLI) is now positioned in the Improving quadrant. Its location above the horizontal axis but to the left of the vertical axis indicates that relative momentum is improving, although the sector has not yet entered Leading.
The transition into Improving is significant because the previous configuration had no sector in this quadrant. XLI's trajectory will therefore be important to monitor. Continued movement toward the upper-right would indicate strengthening relative momentum and could eventually lead to a transition into Leading. Conversely, a Reversal toward the lower-left would weaken the improvement signal.
The emergence of XLI also suggests that momentum conditions are beginning to broaden beyond the two established leaders.
Weakening: Energy
Energy (XLE) remains the only sector positioned in the Weakening quadrant. Its location indicates that Energy continues to maintain relatively stronger positioning than the sectors in Lagging, but its momentum has deteriorated.
The sector remains clearly separated from the large Lagging group, making its future trajectory important. A move back toward the upper-right would indicate renewed momentum, while continued movement toward the lower-left could eventually result in a transition into Lagging.
XLE therefore remains a key transition sector within the current RRG structure.
Lagging: Seven Sectors
Seven sectors remain in Lagging: Financials (XLF), Health Care (XLV), Consumer Discretionary (XLY), Real Estate (XLRE), Consumer Staples (XLP), Materials (XLB) and Utilities (XLU).
The large Lagging group continues to demonstrate that weaker relative momentum remains widespread across the US sector universe. Although XLI has moved into Improving, most sectors remain below the horizontal axis and have yet to establish a sustained improvement in relative momentum.
The individual trajectories differ considerably. Some sectors are positioned relatively close to the centre, while others remain substantially deeper inside the Lagging quadrant. A sustained movement toward the upper-right would be required to demonstrate a meaningful improvement in their relative momentum.
Leadership Remains Concentrated
The latest RRG configuration continues to show relatively narrow leadership. Technology and Communication Services are the only sectors in Leading, while Industrials has emerged as the sole sector in Improving. Energy remains in Weakening, and seven sectors remain in Lagging.
The appearance of XLI in Improving is the key structural change from the previous configuration. It indicates that momentum improvement is beginning to appear outside the two established leaders, although the broader sector universe remains dominated by Lagging classifications.
The trajectories of XLK and XLC remain important for assessing whether current Leadership persists. At the same time, XLI's movement toward or away from Leading will provide an indication of whether sector momentum is beginning to broaden.
Strategic Summary
The latest US sector RRG presents a concentrated momentum environment, with Communication Services and Technology in Leading, Industrials in Improving, Energy in Weakening and seven sectors in Lagging.
XLK and XLC continue to occupy the Leading quadrant, while XLI represents the first clear sign of improving momentum among the previously weaker sectors. XLE remains the principal sector to monitor within Weakening, while Financials, Health Care, Consumer Discretionary, Real Estate, Consumer Staples, Materials and Utilities remain in Lagging.
Overall, the chart indicates that broad sector momentum improvement has begun to emerge but remains limited. The key developments to monitor are whether XLK and XLC maintain their Leading positions, whether XLI continues moving toward the upper-right, whether XLE regains momentum, and whether the large Lagging group begins a sustained transition toward Improving.

 Nov 02, 2026
 Please wait processing your request...