
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Three Sectors in Leading: Energy (XLE), Health Care (XLV) and Communication Services (XLC) are positioned in Leading.
- Communication Services Enters Leading: XLC has moved into Leading, signalling strengthening relative momentum.
- Materials Reverses into Improving: Materials (XLB) has moved back from Leading into Improving.
- Five Sectors in Improving: Utilities (XLU), Real Estate (XLRE), Consumer Staples (XLP), Materials (XLB) and Financials (XLF) are in Improving.
- Technology and Consumer Discretionary Remain Weakening: Technology (XLK) and Consumer Discretionary (XLY) remain in Weakening despite Technology gaining 0.61%.
- Industrials Remains Lagging: Industrials (XLI) continues to show weaker relative momentum despite recording the strongest daily gain of 1.09%.
- Active Sector Rotation: The RRG shows three sectors in Leading, five in Improving, two in Weakening and one in Lagging, highlighting continued rotation across the US Equity market.
The latest US sector momentum visualization for 26 August 2026 shows three sectors in Leading, five in Improving, two in Weakening and one in Lagging. The chart indicates an active rotation environment, with Communication Services strengthening into Leading while Materials has reversed back into Improving.
The daily performance data also shows a clear divergence between price performance and relative momentum. Industrials gained 1.09% and Technology advanced 0.61%, yet both remain outside the Leading quadrant. Conversely, Communication Services entered Leading despite declining 0.50% during the latest session.
Momentum Breakdown by Quadrant
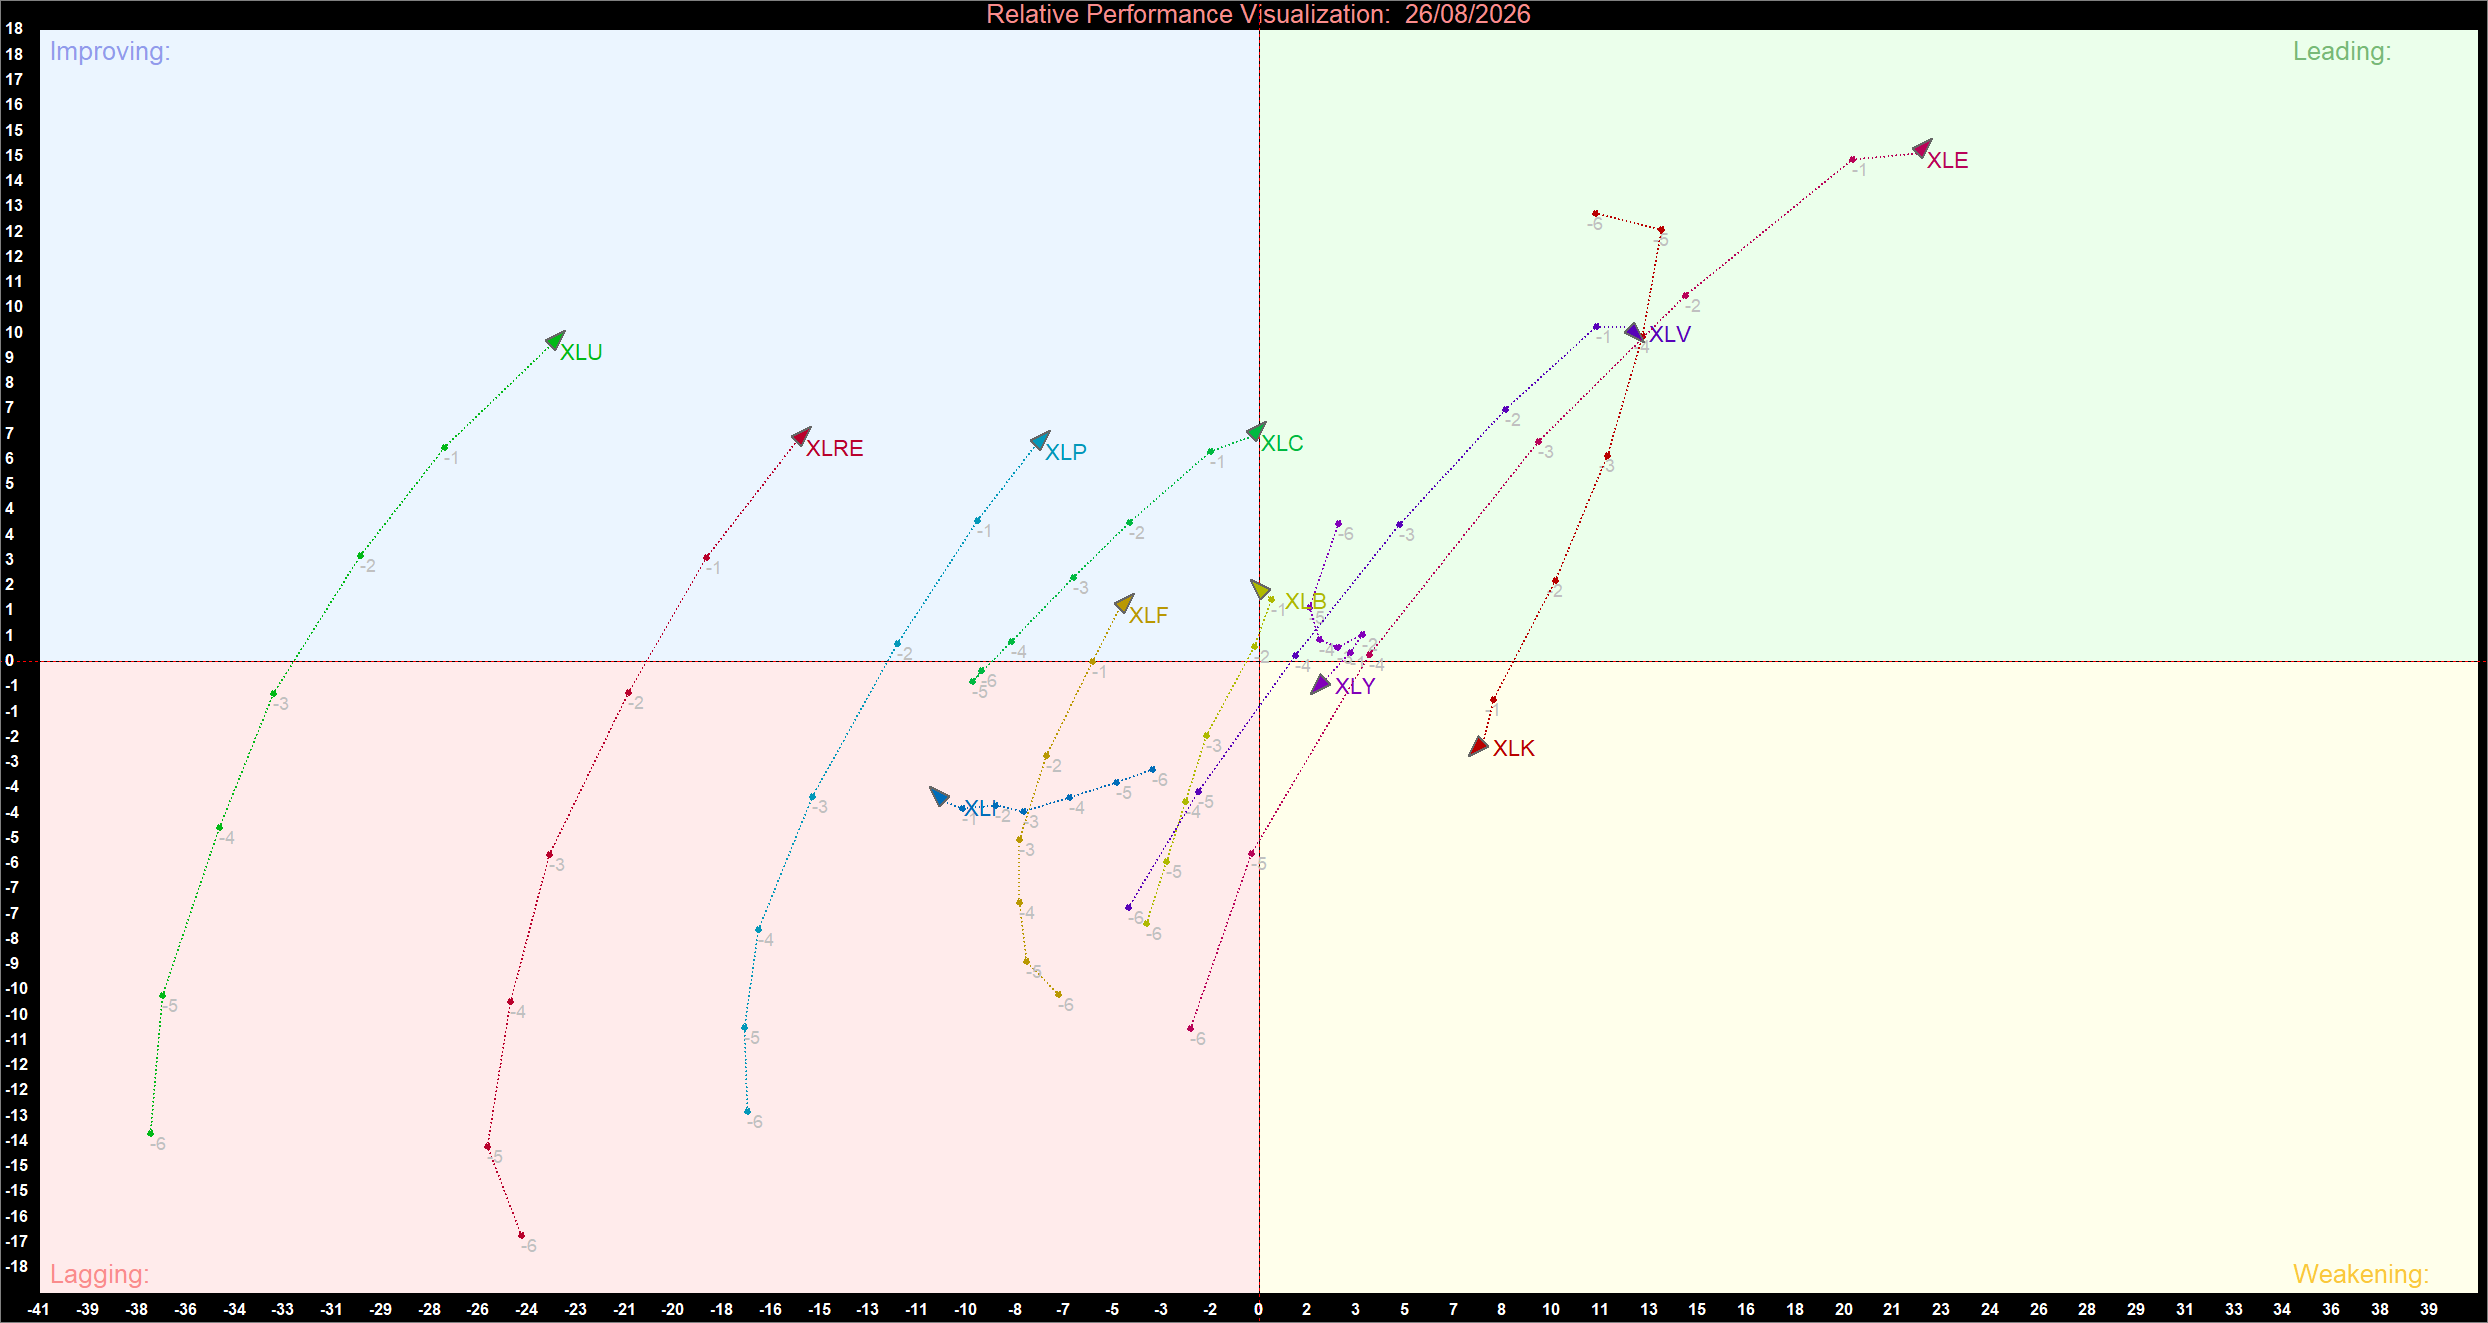
ASX Sector Relative Momentum Chart (at the closing price of 26/08/2026). Powered by: amibroker.com.
Leading: Energy, Health Care and Communication Services
Energy (XLE), Health Care (XLV) and Communication Services (XLC) are positioned in Leading.
Energy continues to occupy a strong Leading position and remains one of the market's strongest sectors from a relative momentum perspective. Health Care also maintains a solid Leading position, indicating continued relative strength.
The most notable change is Communication Services, which has entered Leading. Although XLC declined 0.50% during the latest session, its RRG position indicates that its relative momentum has strengthened sufficiently to move into the Leading quadrant.
Together, Energy, Health Care and Communication Services form the current core of US sector momentum leadership. Continued movement within the Leading quadrant would reinforce their relative strength.
Improving: Utilities, Real Estate, Consumer Staples, Materials and Financials
Utilities (XLU), Real Estate (XLRE), Consumer Staples (XLP), Materials (XLB) and Financials (XLF) are positioned in Improving.
Utilities continues to show improving relative momentum and gained 0.46% during the latest session. Real Estate is also in Improving despite declining 0.60%, indicating that its relative momentum remains stronger than its short-term price performance suggests.
Consumer Staples remains in Improving after falling 0.29%, while Financials is also positioned in this quadrant following a modest 0.09% decline.
Materials (XLB) has made an important change, reversing back from Leading into Improving. The sector gained 0.17% during the latest session, but its latest RRG positioning indicates that its relative momentum has moderated.
Further movement toward the upper-right of the RRG would strengthen the case for these Improving sectors to transition into Leading. Conversely, continued deterioration in Materials could signal a more sustained loss of relative momentum.
Weakening: Technology and Consumer Discretionary
Technology (XLK) and Consumer Discretionary (XLY) remain in Weakening.
Technology gained 0.61% during the latest session, yet remains in the Weakening quadrant. This divergence demonstrates that strong daily price performance does not necessarily translate into improving relative momentum.
Consumer Discretionary also remains in Weakening after declining 0.67%. Its current position indicates that relative strength continues to deteriorate, with further movement toward Lagging potentially confirming a more sustained loss of momentum.
The positioning of both sectors highlights the importance of relative momentum analysis rather than relying solely on daily performance figures.
Lagging: Industrials
Industrials (XLI) remains in Lagging, indicating weaker relative momentum despite being the strongest-performing sector on the day, with a 1.09% gain.
This is a notable divergence between short-term price performance and broader relative momentum. A sustained move toward the centre of the RRG would provide the first indication of a potential recovery in Industrials.
The current position suggests that the recent daily strength has not yet been sufficient to reverse the sector's weaker relative momentum profile.
Strategic Summary
The latest US sector momentum analysis shows three sectors in Leading, five in Improving, two in Weakening and one in Lagging. Energy, Health Care and Communication Services form the current Leadership group, with XLC making the most notable positive transition by entering Leading.
Meanwhile, Materials has reversed back into Improving, while Utilities, Real Estate, Consumer Staples and Financials continue to show improving relative momentum. Technology and Consumer Discretionary remain in Weakening, while Industrials continues to occupy the Lagging quadrant.
Overall, the RRG indicates an active sector rotation environment. The transition of Communication Services into Leading is a positive development, while Materials' Reversal back into Improving warrants monitoring. Continued strength among the Improving sectors would be needed to confirm a broader shift toward market leadership.

 Nov 06, 2026




 Please wait processing your request...