
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
• Southern Copper (SCCO) closed at $171.26, down 1.99% on June 26, 2026, drawing attention among large-cap mining stocks.
• Southern Copper Corporation carries a market capitalization of approximately $145.78 billion, qualifying it firmly among large-cap US stocks.
• The stock trades at a trailing P/E of 29.60 with diluted EPS of $5.90, placing it at a valuation investors weigh against spot copper prices.
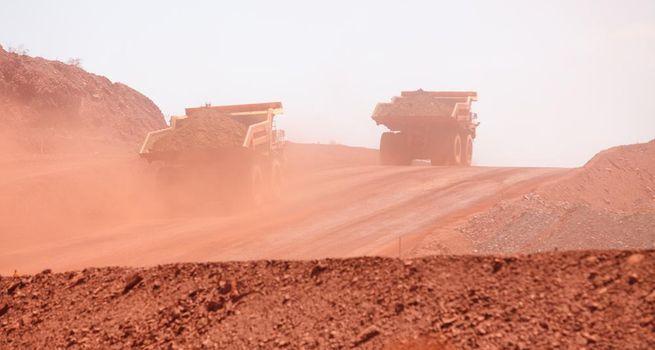
• SCCO is one of the most vertically integrated copper miners globally, with operations spanning mining, smelting, and refining.
Introduction
Few corners of the large-cap US stock universe invite as much macro debate as the metals and mining sector, and Southern Copper Corporation (NYSE:SCCO) sits squarely at its center. On June 26, 2026, shares of SCCO fell 1.99% to $171.26 according to a market screener snapshot of large-cap US companies taken at 16:18 that afternoon. The pullback may look modest in isolation, but for a stock representing a market capitalization of roughly $145.78 billion, each percentage point carries significant weight across institutional portfolios.
Southern Copper earned its place on the large-cap screener by sheer market value: at nearly $146 billion, SCCO ranks among the highest US-listed companies by market cap, drawing attention from index funds, pension allocators, and macro-focused hedge funds alike. The company is not merely a passive commodity play, it is one of the most fully integrated copper producers on the planet, controlling assets from ore extraction through final refined metal.
The June 26 session came against a backdrop of ongoing investor debate about whether copper has entered a structural supercycle driven by the green-energy transition and digital infrastructure build-out. SCCO's tick higher on that day added a fresh data point to that running argument, prompting traders and analysts to revisit the stock's fundamentals with renewed interest.
Why Investors Are Watching This Large-Cap Stock
Southern Copper Corporation commands institutional attention for reasons that extend well beyond its day-to-day price moves. As one of the largest copper producers in the world by output capacity, SCCO functions as a liquid, exchange-listed proxy for investors seeking exposure to the industrial metal without the logistical complexities of holding physical copper or less-liquid junior miners. That combination of scale, liquidity, and commodity leverage makes it a recurring name on Wall Street watchlists.
The company's vertical integration is a structural competitive advantage that many investors highlight when assessing SCCO's resilience through commodity cycles. By controlling the full production chain, from open-pit and underground mines in Mexico and Peru through smelting facilities and refinery operations, Southern Copper can manage cost structures in ways that pure-play miners often cannot. This integration provides more predictable cash-flow visibility relative to spot copper volatility, an attribute that appeals to large institutional allocators.
Beyond the operational story, SCCO occupies a unique position as a large-cap US stock in a sector, copper mining, that is geographically concentrated in South America and politically sensitive. Investors monitoring the company are therefore watching not only copper price charts but also regulatory environments in Peru and Mexico, labor relations, and water-use agreements that can affect production volumes in ways Wall Street must price in.
Dividend-oriented investors also keep SCCO on their radar. The company has historically returned a meaningful share of earnings to shareholders through distributions, and with diluted EPS of $5.90 as of the screener snapshot, the earnings base available for future payouts remains substantial, even if exact payout levels depend on copper prices no analyst can reliably forecast.
What the Market Data May Be Signalling
A 1.99% decline for a nearly $146 billion market-cap stock is not the kind of move that typically signals short-term speculation. Instead, it may reflect a deliberate repositioning by institutional investors who view copper-linked equities as undervalued relative to the long-term demand narrative around electrification, grid upgrades, and AI data-center construction, though whether that read is correct remains to be seen.
The trailing P/E ratio of 29.60 places SCCO at a valuation that is neither cheap nor aggressively expensive for a large-cap miner. Copper bulls argue that a multiple near 30 may prove reasonable if earnings grow alongside commodity prices over a multi-year horizon. Copper bears counter that cyclical commodity companies rarely deserve sustained premium multiples and that any demand disappointment could compress the ratio quickly.
From a screener standpoint, the June 26 snapshot caught SCCO in positive territory on a day when many large-cap US stocks faced mixed-to-negative pressure. A stock holding pullbacks while broader indices wobble can indicate sector-specific selling pressure or a rotation toward hard-asset names. Investors will be watching whether SCCO's positive momentum is accompanied by volume confirmation in subsequent sessions, as sustained moves on above-average volume tend to carry more analytical weight.
Sector Context
SCCO operates within the Materials sector, specifically in copper mining, a niche that sits at an unusual intersection of traditional industrial cycles and emerging green-economy themes. Copper has long been a bellwether for global economic health, earning it the informal title of "Doctor Copper" among traders who believe the metal's price movements can forecast broader economic trends. That historic role has taken on new dimensions as the metal's importance to electric vehicles, renewable energy infrastructure, and high-capacity electrical grids has sharpened.
Within the large-cap US stock universe, pure-play copper miners are a relatively rare breed. Most broad-market indices contain limited direct copper exposure, meaning investors seeking a meaningful allocation to the metal often find themselves turning to names like SCCO. This scarcity premium, the idea that high-quality, liquid copper exposure in a large-cap wrapper is finite, may help explain why the stock maintains investor interest even during periods of sideways copper prices.
Southern Copper's primary global competitors often treat copper as one revenue stream among many within diversified mining conglomerates. SCCO's relative concentration in copper gives it higher correlation to copper-price movements, which some investors prize as a purer hedge or speculative vehicle, while others see it as a source of earnings volatility risk.
Macro variables weighing on the entire sector include the pace of Chinese manufacturing and construction activity, US infrastructure spending programs, and global EV adoption timelines. Each of these forces can shift copper demand in ways that ripple directly into SCCO's revenue and earnings, making the stock highly sensitive to macro data releases and policy announcements.
Valuation and Sentiment
At the June 26, 2026 screener snapshot, SCCO carried a trailing price-to-earnings ratio of 29.60, with diluted EPS of $5.90 and a price of $171.26. These figures put the stock's market capitalization at approximately $145.78 billion, large enough to qualify it as a major component of any broad large-cap US stock index that includes the Materials sector.
Investor sentiment toward SCCO tends to bifurcate along macro lines. Copper bulls, those who believe the green-energy transition will sustain elevated copper demand for years, often see a P/E near 30 as justifiable or even conservative if earnings can grow with commodity prices. Copper bears point to the cyclical nature of mining earnings and argue that a multiple above 25 for a resource company leaves little margin for safety if demand disappoints.
Wall Street's interest in SCCO is also colored by the company's ownership structure. Grupo Mexico controls a substantial stake, meaning institutional investors are evaluating both copper fundamentals and the governance dynamics of operating under a controlling shareholder. Some large allocators view such structures as a risk factor, while others argue they provide operational continuity absent in companies with more dispersed ownership.
It is worth noting that analyst sentiment across the sector can shift quickly as copper spot prices and futures curves move. Investors should treat the June 26 screener data as a point-in-time reference, not a forecast of future earnings or share-price trajectory.
Key Risks to Watch
No investment in a commodity-linked company like Southern Copper Corporation is without meaningful risk, and several factors deserve careful consideration by anyone monitoring SCCO.
Commodity price risk is the most direct concern. Copper prices are set in global markets and are sensitive to Chinese GDP growth, US manufacturing activity, currency fluctuations, and speculative futures positioning. A sustained decline in copper prices would compress SCCO's margins and earnings, potentially making its current P/E ratio look expensive in hindsight.
Geopolitical and regulatory risk also looms large. Southern Copper's mining operations are concentrated in Mexico and Peru, countries where mining regulation, royalty structures, and political attitudes toward resource extraction can shift with election cycles or social movements. Permitting delays, royalty increases, or water-use restrictions could affect production volumes and costs in ways that are difficult to model from a Wall Street analyst's desk.
Labor relations represent another potential disruption source. Large-scale mining operations rely on substantial workforces, and disputes or strikes can interrupt production and generate negative headlines that weigh on investor sentiment.
Finally, currency risk deserves mention. While SCCO trades in dollars, its operational costs are incurred partly in Mexican pesos and Peruvian soles. Movements in these currencies relative to the dollar can affect reported earnings in ways that are partially hedged but not entirely eliminated.
What Could Move the Stock Next
Several themes could meaningfully influence SCCO's trajectory going forward, though it is important to emphasize that these are potential catalysts, not predictions, and actual outcomes may differ substantially.
Copper price trends will remain the single most important near-term driver. If spot copper prices move higher, driven by weaker-than-expected Chinese industrial demand, US infrastructure contract awards, or supply disruptions at major mines, SCCO could see upward earnings revisions attracting fresh institutional buying. Conversely, a notable drop in copper prices could quickly erase recent pullbacks.
Quarterly earnings releases are another key watchpoint. Investors will be examining production volumes, cash-cost figures, and management commentary on the demand environment and capital allocation plans. Any indication that Southern Copper is expanding capacity or returning additional capital to shareholders could shift sentiment in either direction.
Macro policy announcements, particularly from the US Federal Reserve and the People's Bank of China, could also move SCCO indirectly. Interest rate decisions affect the cost of capital for capital-intensive miners and the pressure of the US dollar, which influences commodity prices denominated in dollars. Investors watching SCCO will likely keep one eye on monetary policy calendars alongside copper's daily price action.
Bottom Line
Southern Copper Corporation's 1.99% decline on June 26, 2026, as captured in the large-cap US market snapshot, offers a useful window into how investor sentiment around copper and the green-energy transition is playing out in real time. With a market capitalization of roughly $145.78 billion, SCCO stands as one of the largest copper-linked equities accessible to US investors, and its moves carry weight for both index trackers and active managers monitoring the Materials sector.
The stock's trailing P/E of 29.60 and EPS of $5.90 provide a valuation baseline from which investors can form their own views, though those views should be held with appropriate humility given how quickly commodity fundamentals can shift.
What the June 26 session affirms is that SCCO continues to attract investor interest as a distinctive large-cap play on copper's growing role in the modern economy. For those monitoring the large-cap US stock landscape, it remains a name worth understanding, whatever one's ultimate view on the copper supercycle debate proves to be.

 Nov 02, 2026
 Please wait processing your request...