
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
• Equinox Gold operates a multi-mine gold portfolio spread across North and South America.
• The company has pursued rapid growth through acquisitions and the development of new projects.
• A major flagship development project has been central to lifting Equinox Gold's production profile.
• EQX offers leverage to gold prices, with scale intended to translate into stronger cash flow.
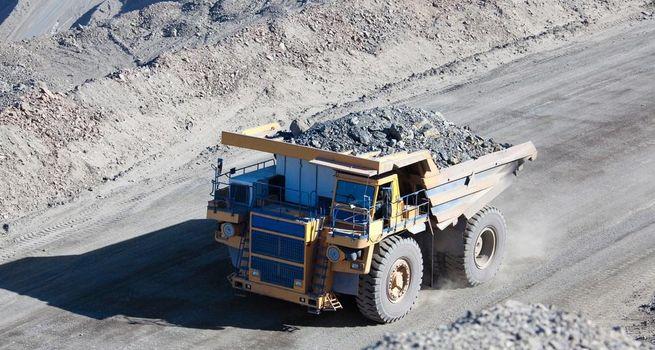
Equinox Gold Corp. (NYSEAMERICAN:EQX) is a company built for growth, assembled in a relatively short time into a multi-mine gold producer with operations stretching across the Americas. Where some miners grow cautiously over decades, Equinox pursued scale aggressively through a series of acquisitions and an ambitious project-development agenda, aiming to rank among the more significant gold producers in the western hemisphere. That strategy gives the stock a clear and compelling thesis: as production rises and major new projects come online, the company should generate substantially more gold and, ideally, more cash flow per share. But growth by acquisition and construction is rarely smooth, and the central question for investors is whether Equinox can convert its impressive scale into genuine shareholder value. Building mines is capital-intensive and operationally demanding, and the market wants to see ambitious plans translate into reliable production and improving margins.
Company Overview
Equinox Gold is a gold-mining company with a portfolio of producing assets located across the Americas, spanning both North and South America. The company was constructed primarily through a strategy of growth, combining acquisitions of existing mines and development-stage projects with the construction of new operations. This has given it a diversified production base across multiple jurisdictions, reducing reliance on any single mine while also introducing the complexity of managing geographically dispersed assets. Equinox operates open-pit and other mining operations and sells its gold into global markets at prevailing prices. A defining feature of the company's recent history has been its flagship development project, a large-scale mine intended to materially increase total production and reshape the company's cost and output profile once fully operational. Equinox has positioned itself as a growth-focused intermediate producer, aiming to climb the ranks of the gold sector.
As such, EQX is best understood as a company in transition, working to consolidate a rapidly built portfolio into a cohesive, cash-generative operation.
Why the Stock Is in Focus
Equinox Gold is in focus largely because of its growth trajectory and the leverage that trajectory creates. The company's strategy of expanding production through acquisitions and new project development means that, in a strong gold-price environment, rising output can amplify revenue and cash flow, offering investors significant upside if execution goes well. The flagship development project has been a particular point of attention, as its successful ramp-up would meaningfully lift total production and could transform the company's scale and cost structure. This kind of step-change story naturally attracts investors looking for growth within the gold space. At the same time, the market scrutinizes Equinox closely because rapid growth brings execution risk; building and ramping major mines can encounter delays, cost overruns and operational challenges. The balance sheet also draws attention, since acquisitions and construction require substantial capital, often funded partly through debt.
The interplay between ambitious growth, leverage to gold and the risks of execution keeps EQX squarely in investors' sights.
Gold, Silver and Precious-Metals Market Backdrop
As a gold producer, Equinox Gold is directly tied to the dynamics of the gold market. Gold's role as a store of value and a hedge against inflation, currency weakness and geopolitical uncertainty drives its demand, and its price responds to real interest rates, central-bank buying, safe-haven flows and broader investor sentiment. For a growth-focused producer with rising output, a strong gold price is doubly powerful: it lifts margins on existing production and improves the economics of new projects coming online, magnifying the benefit of scale. Conversely, a weakening gold price would compress margins and could strain a company carrying construction-related debt. While silver and other precious metals shape the wider sector narrative, Equinox is fundamentally a gold story, with output centered on the yellow metal.
The company's leverage means that gold-price movements can have an outsized effect on its earnings and cash flow, especially as production grows. The prevailing and expected direction of gold therefore forms the most important external backdrop against which Equinox's growth ambitions will be judged by the market.
Key Catalysts Driving Investor Interest
Several catalysts can drive the Equinox Gold story. The most prominent is the ramp-up of its flagship development project; as this large operation moves toward full production, investors look for evidence of rising output, declining unit costs and stronger cash flow, which would validate the growth strategy. Overall production growth across the portfolio is a second catalyst, as the company works to lift total gold output. Cost performance is a third and critical lever, since all-in sustaining costs determine how much of any gold-price gain reaches the bottom line; demonstrating cost discipline would reassure a market wary of growth that erodes margins. Debt reduction and balance-sheet strengthening form another catalyst, as deleveraging would lower financial risk and could re-rate the stock. The gold price itself acts as a continuous catalyst given Equinox's leverage.
Finally, operational milestones, reserve updates and any portfolio optimization, such as divestitures of non-core assets, can shape sentiment. For EQX, the convergence of project execution, cost control and a supportive gold backdrop would be the most powerful combination.
Financial and Valuation Considerations
Valuing a growth-focused gold producer like Equinox Gold requires emphasis on cash flow, costs and the balance sheet rather than headline earnings alone. The company's high operating leverage means margins can expand quickly when gold prices rise and production grows, but the same leverage works in reverse during downturns. A central financial consideration is the capital intensity of Equinox's growth, since building and acquiring mines requires substantial investment, often involving debt that the market watches closely. Free cash flow is a key metric: investors want to see the company transition from heavy spending on construction toward generating sustainable cash once major projects are operating. All-in sustaining costs are scrutinized as a measure of competitiveness and margin quality. Valuation discussions around EQX often weigh the promise of rising production and potential cash generation against the execution and balance-sheet risks of its growth strategy.
Because the company is in transition, its valuation can be sensitive to both operational news and gold-price expectations. The ability to turn scale into durable free cash flow is the crux of the financial case.
Growth Outlook and Project Pipeline
Equinox Gold's growth outlook is one of the most prominent features of its investment case. The company's pipeline is anchored by its flagship development project, a large-scale operation designed to substantially increase total production and reshape the company's output and cost profile once fully ramped. Beyond that centerpiece, Equinox maintains a portfolio of producing mines that contribute ongoing output and offer opportunities for optimization, expansion and exploration to extend mine lives. The growth strategy has historically combined building new operations with acquiring and improving existing ones, reflecting an ambition to climb the ranks of gold producers. The key question for investors is whether this pipeline can be executed on time and on budget, and whether the resulting production growth translates into lower per-ounce costs and stronger cash flow rather than simply more gold at thin margins.
Successful delivery would mark a transition from a capital-hungry growth phase to a more self-funding, cash-generative model. The outlook, therefore, hinges on execution as much as on the inherent quality of the projects themselves.
Major Risks Investors Should Watch
Equinox Gold carries substantial risks befitting an ambitious, growth-oriented producer. Execution risk is paramount; building and ramping major mines can encounter delays, technical difficulties and cost overruns, and a flagship project that underperforms expectations could weigh heavily on the company. Gold-price risk is significant given the company's leverage, as weaker prices would compress margins and strain finances. Balance-sheet risk is notable because growth through acquisition and construction often relies on debt, which can become burdensome in a downturn. Operational risk spans the usual mining challenges of grade variability, recovery shortfalls, equipment issues and cost inflation in labor, energy and consumables, compounded by the complexity of managing a geographically dispersed portfolio. Jurisdictional risk arises across the multiple countries in which Equinox operates, introducing permitting, tax, political and regulatory considerations. Reserve and resource risk, currency movements and shifting sentiment toward intermediate gold producers add further variables.
Investors weighing EQX should recognize that these risks are interlinked and that the same leverage powering upside also magnifies downside.
What Could Drive the Stock Next
Looking ahead, the Equinox Gold story is likely to be driven by execution on its growth pipeline and the broader gold environment. The performance of its flagship development project will be pivotal; a smooth ramp toward full production, accompanied by falling unit costs, would validate the strategy and could re-rate the stock, while delays or cost overruns would do the opposite. Production and cost trends across the wider portfolio will signal whether scale is translating into improving margins. Progress on debt reduction would lower financial risk and could shift sentiment positively, especially given the capital intensity of the company's growth. Portfolio optimization, including any divestitures of non-core assets, could sharpen the investment case. Externally, the direction of the gold price remains decisive, amplifying or eroding the benefits of rising production given Equinox's leverage.
Investor appetite for growth-oriented gold equities and broader risk sentiment will also matter. For EQX, the central narrative ahead is whether disciplined execution can finally convert hard-won scale into tangible shareholder upside.
Conclusion
Equinox Gold embodies the promise and the peril of building a gold producer at speed. Through acquisitions and ambitious development, the company assembled a multi-mine portfolio across the Americas and set itself on a path of rising production, anchored by a flagship project capable of reshaping its scale and cost profile. For investors, the appeal lies in the leverage this growth creates: more gold, in a supportive price environment, could translate into substantially stronger cash flow and shareholder value. The challenge is that growth by construction and acquisition is demanding, exposing the company to execution risk, cost pressures and the debt that often accompanies rapid expansion. The decisive question, whether Equinox can turn scale into genuine upside, will be answered through operational delivery rather than ambition alone.
For those following the gold sector, EQX offers a compelling case study in growth and execution, rewarding close attention to project ramp-ups, cost trends and balance-sheet progress against an ever-influential gold backdrop.

 Nov 02, 2026
 Please wait processing your request...