
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
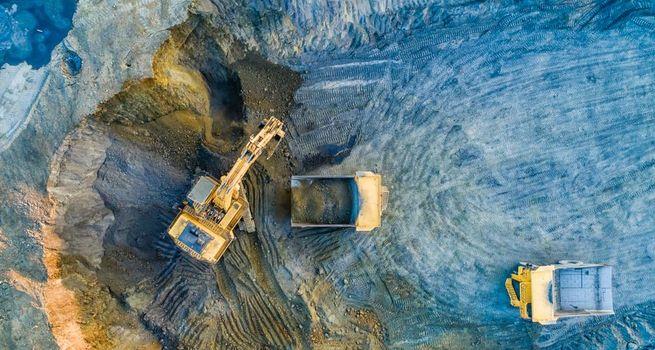
Key Highlights
• Coeur Mining is a diversified gold and silver producer with assets spread across the United States, Mexico and South America.
• The company offers unusually high silver exposure compared with many mid-tier peers, sharpening its sensitivity to that metal.
• A multi-year expansion of its flagship Rochester operation has been central to the CDE investment narrative.
• Coeur's earnings and cash flow are highly geared to precious-metals price swings, cutting both ways.
Few precious-metals producers wear their dual-metal identity as openly as Coeur Mining Inc. (NYSE:CDE). While many gold miners treat silver as a minor by-product, Coeur has long positioned silver alongside gold as a core part of its revenue mix, giving the stock a distinctive personality within the sector. That positioning matters enormously in periods when silver moves sharply, because the metal's higher volatility can amplify both the upside and the downside for a company like CDE. After years of heavy capital spending to modernize and expand its asset base, Coeur Mining has reached a stage where investors are asking whether the groundwork is finally translating into stronger, more consistent cash generation. The question driving renewed attention is straightforward: is Coeur Mining gearing up for a genuine operational and financial inflection, or is the market simply responding to a friendly precious-metals backdrop?
Company Overview
Coeur Mining is a long-established precious-metals mining company headquartered in the United States, with a history stretching back more than a century. Its operating portfolio centers on a handful of mines that produce a blend of gold and silver, located in jurisdictions including the United States, Mexico and South America. The company's flagship silver-gold operation in Nevada has historically been one of the largest silver mines in the country, while its gold-focused assets help balance the overall production profile. Coeur runs both open-pit and underground operations, and it has invested in processing infrastructure designed to lift recovery rates and throughput over time. The company sells its output into global precious-metals markets, meaning its realized prices track international benchmarks rather than any fixed contract. Coeur also retains exploration ground around its existing mines, giving it the option to extend mine lives organically.
Overall, CDE sits in the mid-tier producer category, large enough to matter yet small enough to move sharply on operational news.
Why the Stock Is in Focus
Coeur Mining tends to attract heightened attention whenever silver and gold prices are in motion, and that is a recurring theme for the stock. Because the company carries above-average silver exposure, CDE often behaves like a higher-beta vehicle for investors who want amplified participation in precious-metals rallies. Beyond price sensitivity, the spotlight has fallen on Coeur's operational execution. The years-long effort to expand and optimize its key Nevada operation represented one of the largest single investments in the company's modern history, and the market has watched closely to see whether ramped-up volumes and improved efficiency materialize as planned. Successful execution would mark a transition from heavy capital outlay toward harvesting cash flow. There is also a balance-sheet dimension: investors have scrutinized how quickly Coeur can reduce debt taken on during its build-out phase.
When operational momentum, a supportive metals tape and deleveraging progress align, CDE can become a focal point for sector-watchers looking for leveraged exposure.
Gold, Silver and Precious-Metals Market Backdrop
The broader precious-metals environment is the single largest external force shaping Coeur Mining. Gold has historically functioned as a store of value and a hedge against currency debasement, geopolitical stress and shifting real interest rates, while silver carries a dual identity as both a monetary metal and an industrial input used in electronics, solar panels and other applications. That industrial dimension can make silver more volatile than gold, responding to manufacturing demand as well as investment flows. For a producer with meaningful silver weighting like Coeur, this means the company's fortunes are tied not only to safe-haven demand but also to the health of industrial cycles. Periods of monetary uncertainty, inflation concerns or weakening confidence in fiat currencies have historically supported precious-metals interest. Conversely, rising real yields and a strong US dollar can pressure the complex.
Because Coeur is essentially a price-taker, the prevailing direction and volatility of gold and silver markets often overshadow company-specific factors in the short term, framing the entire CDE narrative.
Key Catalysts Driving Investor Interest
Several catalysts can move the Coeur Mining story. The most prominent has been the completion and ramp-up of its expanded Rochester silver-gold operation in Nevada; as throughput climbs toward designed capacity, investors look for evidence of rising production, lower unit costs and stronger margins. A second catalyst is overall cost control across the portfolio, since all-in sustaining costs determine how much of any metal-price gain reaches the bottom line. Debt reduction is a third: progress in paying down borrowings can re-rate the stock by reducing financial risk and freeing up cash. Exploration success around existing mines offers a fourth lever, potentially extending mine lives and supporting reserves. Finally, the metals themselves act as an ever-present catalyst; a sustained move higher in silver in particular can disproportionately benefit Coeur given its mix.
Quarterly operating updates, production guidance and reserve revisions are the moments when these catalysts typically crystallize for the market, making CDE an event-driven name as much as a macro one.
Financial and Valuation Considerations
Valuing a leveraged precious-metals producer like Coeur Mining requires looking beyond simple snapshots. Investors commonly assess miners on cash flow, all-in sustaining costs, production growth and balance-sheet strength rather than on conventional earnings multiples alone, because reported profits can swing wildly with metal prices and non-cash items. Coeur's financial profile has historically been characterized by high operating leverage: when prices rise, margins can expand quickly, and when they fall, the reverse holds. The capital intensity of its expansion phase weighed on free cash flow for a period, so the market focuses on the transition toward positive and sustained cash generation. Debt levels and the pace of deleveraging are central to how investors gauge risk. Because of its silver tilt, CDE may trade differently from pure gold names, sometimes commanding attention during silver rallies and lagging when gold leads.
Ultimately, valuation discussions around Coeur tend to revolve around its sensitivity to metal prices and its ability to convert production into durable free cash flow.
Growth Outlook and Project Pipeline
Coeur Mining's growth thesis rests largely on extracting full value from assets it has already built and acquired rather than chasing distant greenfield projects. The expanded Nevada silver-gold operation is the centerpiece, designed to deliver higher long-term production once fully ramped. Beyond that flagship, the company maintains gold-producing mines that contribute steady output and exploration ground that could extend reserves and mine lives. Coeur has at times pursued acquisitions to strengthen its portfolio, reflecting a strategy of consolidating quality assets in stable jurisdictions. Brownfield exploration near existing infrastructure is generally lower-risk and lower-cost than building from scratch, and success there can quietly compound value. The growth question for investors is whether Coeur can lift production while holding or reducing costs, thereby widening margins independent of metal prices.
If the company demonstrates that operational discipline alongside a healthy reserve base, the pipeline could underpin a more self-funding growth model. Execution, as always in mining, will determine whether the outlook is realized.
Major Risks Investors Should Watch
The risks surrounding Coeur Mining are substantial and characteristic of the sector. The foremost is price risk: as a price-taker on both gold and silver, Coeur's revenue and margins can deteriorate rapidly if metals weaken, with the silver exposure adding extra volatility. Operational risk is ever-present, encompassing lower-than-expected grades, recovery shortfalls, equipment issues and the challenges of ramping a major expansion to nameplate capacity. Cost inflation in labor, energy, reagents and equipment can erode margins even in a stable price environment. Balance-sheet risk matters given the debt incurred during expansion; a downturn could make deleveraging harder. Jurisdictional and regulatory factors across its operating regions introduce permitting, tax and political considerations. Reserve and resource risk means estimates can be revised down. Finally, currency movements and broader equity-market sentiment toward small- and mid-cap miners can amplify swings.
Investors weighing CDE should recognize that these risks interact, and that the same leverage that powers upside also magnifies downside.
What Could Drive the Stock Next
Looking ahead, the near-term trajectory of Coeur Mining is likely to hinge on a familiar mix of operational and macro signals. On the operational side, the market will watch whether the expanded Nevada operation continues to lift volumes while costs trend lower, and whether quarterly results confirm the transition toward sustained free cash flow. Tangible progress on debt reduction could meaningfully shift sentiment, as a cleaner balance sheet lowers perceived risk. Reserve and resource updates, along with any exploration breakthroughs, may extend the company's runway and support the longer-term story. On the macro side, the direction of silver and gold remains decisive; a durable upswing, particularly in silver, would amplify Coeur's earnings power given its mix. Conversely, a weaker metals tape or operational stumbles could quickly cool enthusiasm. Investor positioning toward leveraged precious-metals equities and broader risk appetite will also play a role.
In short, CDE's path forward is a blend of self-help execution and forces well beyond the company's control.
Conclusion
Coeur Mining occupies an unusual niche as a mid-tier producer with genuine dual exposure to silver and gold, layered on top of high operating leverage. The bull case rests on a freshly expanded asset base, the prospect of rising production at lower unit costs, and a pivot toward generating and deploying free cash flow to strengthen the balance sheet. The bear case centers on the company's vulnerability to volatile metal prices, the execution risk inherent in ramping a major operation, and the financial obligations carried into this stage. Whether CDE is truly gearing up for a breakout will depend on the interplay between disciplined operational delivery and a precious-metals market that no company can control. For those tracking the sector, Coeur remains a compelling case study in leverage, execution and timing, rewarding close attention to operating data and metal-price trends rather than headline narratives alone.

 Nov 02, 2026
 Please wait processing your request...