
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
• China Gold International Resources produces both gold and copper from large-scale operations centered in China.
• The company is affiliated with a major state-linked Chinese gold group, giving it a distinctive backing.
• Its dual-commodity profile blends precious-metals leverage with copper exposure tied to industrial demand.
• Scale and long-life assets are central to the JINFF investment narrative.
China Gold International Resources Corp. Ltd. (OTCMKTS:JINFF) offers investors a route into large-scale gold and copper mining anchored in China and backed by one of the country's most significant precious-metals enterprises. As a producer with substantial operations and a connection to a major state-linked gold group, the company occupies a distinctive position among gold equities accessible to international investors. Its appeal rests on production scale, a dual-commodity profile spanning gold and copper, and the institutional weight of its affiliation. At the same time, its concentration in a single country and its exposure to two volatile commodities shape a particular risk-and-reward equation. As gold sentiment strengthens and copper remains central to industrial and energy-transition demand, JINFF draws renewed attention.
Company Overview
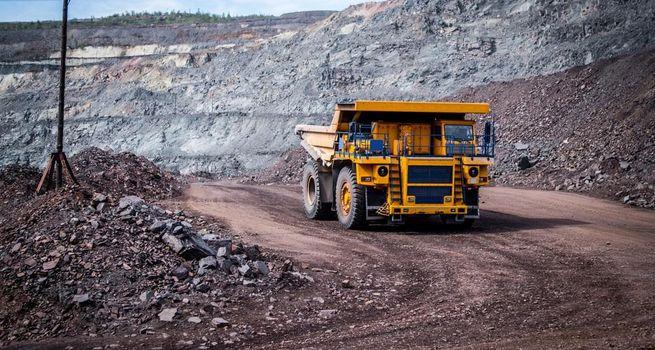
China Gold International Resources is a mining company that produces both gold and copper, with flagship operations located in China. Its asset base has historically centered on large-scale mines, including a major gold operation and a significant copper-gold operation, giving the company a meaningful production footprint and a dual-commodity character. A defining feature of the company is its affiliation with a leading state-linked Chinese gold group, one of the country's foremost players in the precious-metals industry. This connection provides institutional backing and links the company to a broader enterprise with deep roots in the sector. The dual-commodity profile means China Gold International derives value from both gold, a precious metal driven by safe-haven and monetary dynamics, and copper, an industrial metal tied to economic activity and electrification.
For investors, JINFF represents exposure to substantial, long-life mining operations within a single jurisdiction, supported by a major parent organization and spanning two of the most closely watched metals in global markets.
Why the Stock Is in Focus
China Gold International Resources draws attention for a combination of scale, backing and commodity exposure. Its production base in gold and copper gives it leverage to two important metals, broadening its appeal across investors interested in either precious metals or industrial commodities. The company's affiliation with a major state-linked Chinese gold group lends it a distinctive institutional dimension that few peers can claim. As gold sentiment strengthens during periods of macroeconomic uncertainty, producers with real output and cash flow attract interest, and China Gold International's scale positions it within that group. Meanwhile, copper's central role in electrification and infrastructure keeps the company relevant to the energy-transition narrative. Its single-country focus also generates discussion, since concentration in China shapes both its opportunity set and its risk profile.
The blend of dual-commodity production, significant scale and a notable parent affiliation keeps JINFF a recurring subject among investors tracking the global gold and copper space.
Gold, Silver and Precious-Metals Market Backdrop
China Gold International operates against a backdrop shaped by both precious-metals and industrial-metal dynamics. Gold prices respond to real interest rates, inflation expectations, currency movements, central-bank purchasing and safe-haven demand, with central-bank buying in particular being a notable feature of the modern gold market. Silver and other precious metals often move alongside gold. Copper, by contrast, follows industrial drivers tied to construction, manufacturing and the accelerating demand from electrification and clean-energy infrastructure. For a dual-commodity producer like China Gold International, both sets of dynamics matter: gold provides exposure to monetary and safe-haven themes, while copper offers leverage to global growth and the energy transition. A supportive environment for either metal can enhance the company's economics, and strength in both can be especially beneficial. Conversely, weakness in gold or copper would weigh on results.
Understanding JINFF therefore requires attention to the macro forces shaping both the precious-metals and industrial-metal markets, since each contributes materially to the company's overall performance.
Key Catalysts Driving Investor Interest
Several catalysts shape the investment case for China Gold International Resources. Production and cost updates from its flagship gold and copper operations are central, since they determine cash generation and margin performance across both commodities. Movements in the gold price act as catalysts given producer leverage, while copper-price trends, closely linked to global growth and electrification demand, influence the industrial side of the business. Operational developments, including grade trends, throughput and mine-life extensions, can shift sentiment. The company's relationship with its major parent group can be a catalyst, since corporate support, asset opportunities or strategic initiatives tied to the broader enterprise may influence its trajectory. Capital-allocation decisions, including investment in growth and any returns to shareholders, also draw attention. On the macro side, broad themes around precious metals and the energy transition can move the stock.
Together, these factors create a multidimensional catalyst landscape reflecting the company's dual-commodity nature and its distinctive institutional backing.
Financial and Valuation Considerations
China Gold International is evaluated using metrics common to mining rather than standard industrial measures. Investors typically focus on production costs as a gauge of efficiency, cash flow relative to capital spending and the strength of the balance sheet, particularly given the capital intensity of large-scale operations. Because the company produces both gold and copper, its margins reflect the interplay of two commodity prices against its cost base, and copper by-product or co-product credits can influence reported gold costs. Valuation approaches include price-to-cash-flow comparisons against peers, net-asset-value estimates that discount future production and sum-of-the-parts analyses accounting for the dual-commodity structure. The company's scale and long-life assets factor into how the market assesses its durability. Any specific figures should be treated as cyclical and variable, since mining results swing with commodity prices and operational factors.
For JINFF, the interaction between large-scale gold and copper production, two volatile commodity prices and its cost structure forms the core of its financial and valuation story.
Growth Outlook and Project Pipeline
China Gold International's growth outlook rests on sustaining and optimizing its large-scale operations while pursuing opportunities to extend mine life and expand production. At its flagship gold and copper-gold mines, the company seeks to maintain output through operational improvements, exploration around existing infrastructure and pit or underground expansions that can add metal at relatively attractive incremental cost. The company's affiliation with a major parent group introduces the possibility of access to additional assets or strategic opportunities tied to the broader enterprise, a feature that distinguishes it from many independent peers. As with all miners, reserve replacement is a structural necessity, since production continually depletes resources; the ability to discover, develop or acquire new metal will shape the long-term trajectory. Copper's growing importance in the energy transition adds a thematic dimension to any expansion of the company's copper output.
The credibility of its production sustainability and growth initiatives, supported by its institutional backing, sits at the heart of the JINFF growth thesis.
Major Risks Investors Should Watch
The risks facing China Gold International Resources blend sector-wide and company-specific elements. Commodity-price risk is foremost and dual: a sustained decline in either gold or copper would pressure margins and cash flow. Jurisdictional concentration is a defining risk, since the company's operations are centered in a single country, exposing it to local regulatory, policy and economic conditions. Operational risk attaches to running large-scale mines, where grade variability, equipment issues and processing challenges affect output. Cost inflation in energy, labor or consumables can erode margins even when commodity prices hold. Reserve depletion is a structural risk requiring continual replacement. Governance and transparency considerations, common when evaluating companies with significant state-linked affiliations, may factor into how some international investors view the stock. Currency dynamics can affect costs and reported results. Liquidity considerations may also apply for investors accessing the shares through certain market channels.
Investors weighing JINFF typically balance its scale and backing against this layered risk profile.
What Could Drive the Stock Next
The next phase for China Gold International Resources is likely to hinge on the interplay between gold and copper prices, operational performance and developments tied to its parent affiliation. A constructive gold environment would amplify the value of its precious-metals output, while firm copper prices, supported by electrification demand, would benefit the industrial side. The market will watch production and cost trends at flagship operations, any mine-life extensions and the company's ability to sustain output amid natural depletion. Strategic developments connected to its major parent group, including potential asset opportunities, could influence the trajectory. Capital-allocation signals, including investment priorities and any shareholder returns, will also be monitored. Broader sentiment toward gold equities and toward copper as an energy-transition metal can move the stock independent of fundamentals.
In short, the path forward for JINFF depends on a combination of dual-commodity price trends, operational execution and how effectively the company leverages its distinctive institutional position.
Conclusion
China Gold International Resources stands as a distinctive name in the global mining landscape, combining large-scale gold and copper production in China with the backing of a major state-linked precious-metals group. That blend of scale, dual-commodity leverage and institutional support explains why the stock draws market attention, particularly as gold sentiment strengthens and copper remains central to the energy-transition story. Yet the same concentration that defines its footprint also frames its principal risks, tying the company to a single jurisdiction and to two volatile commodities, alongside governance considerations that some international investors weigh. As the gold and copper cycles evolve, China Gold International's ability to sustain output, extend mine life and leverage its institutional position will shape its trajectory. For those following the precious-metals and copper space, JINFF remains an instructive case study in scale, backing and concentrated exposure.

 Nov 02, 2026
 Please wait processing your request...