
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
• Alamos Gold operates producing gold mines concentrated in politically stable North American jurisdictions.
• The company emphasizes long-life assets, organic growth, and cost discipline rather than debt-heavy expansion.
• AGI's earnings leverage to the gold price gives it meaningful upside in strong bullion markets.
• A multi-year project pipeline aims to lift production while reducing per-ounce costs over time.
Few sectors swing as hard on sentiment as gold mining, where a single shift in bullion prices can reshape an entire quarter. Within that volatile universe, Alamos Gold Inc. (NYSE:AGI) has built a reputation as a name investors reach for when they want exposure to gold without the headline risk that haunts frontier-market operators. The company's pitch is straightforward but compelling: own quality ounces in jurisdictions where the rule of law is predictable, keep costs low enough to stay profitable across the cycle, and grow from the assets you already control. That combination has made Alamos Gold a recurring talking point whenever gold pushes toward record territory.
Company Overview
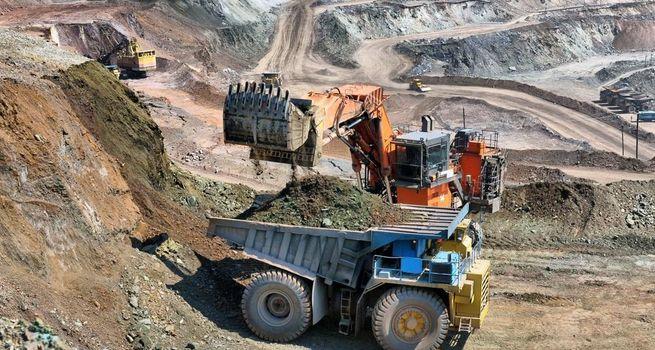
Alamos Gold is an intermediate gold producer whose operating footprint centers on Canada and Mexico, two regions generally regarded as mining-friendly. The company's portfolio typically includes flagship Canadian operations alongside Mexican production, giving it a blend of established cash-generating mines and assets positioned for incremental expansion. Alamos has historically distinguished itself through an "organic growth" philosophy: rather than chasing large, expensive takeovers, management tends to invest in expanding throughput, extending mine lives, and unlocking nearby deposits within its existing land packages. This approach is meant to compound value while limiting the integration and balance-sheet strain that can accompany aggressive M&A. The firm also maintains a focus on operational efficiency, aiming for all-in sustaining costs that sit toward the lower end of the producer spectrum.
For investors, the headline identity of Alamos Gold is that of a disciplined, North America-weighted miner trying to deliver steady ounces and improving margins through the gold cycle.
Why the Stock Is in Focus
Alamos Gold tends to attract attention for reasons that go beyond a rising gold price. First, its jurisdictional profile resonates in an era when investors are increasingly wary of resource nationalism, permitting delays, and political instability in some mining regions. Producing gold primarily in Canada and Mexico positions AGI as a comparatively "clean" exposure. Second, the company's growth narrative, built on expanding existing operations and advancing development projects, offers a path to higher production without the dilution risk of constant equity raises. Third, Alamos has cultivated a reputation for relatively conservative financial management, which appeals to investors burned by over-leveraged miners in past downturns. When gold rallies, AGI's profile makes it a natural candidate for capital seeking quality rather than speculation.
The result is a stock that frequently appears in conversations about which gold names might offer durability if the precious-metals bull case continues to play out across coming years.
Gold, Silver and Precious-Metals Market Backdrop
The broader backdrop matters enormously for any miner, and Alamos Gold is no exception. Gold has long served as a hedge against inflation, currency debasement, and geopolitical uncertainty, and demand from central banks, institutional investors, and retail buyers can swing the metal's price meaningfully. Periods of monetary easing, fiscal expansion, or financial-market stress have historically supported bullion, while rising real interest rates can pressure it. Silver, often produced as a byproduct at some operations, carries its own dual identity as both a precious and industrial metal, adding a different demand dynamic tied to manufacturing and technology. For a producer like AGI, the level and stability of the gold price is the single most important external variable: it drives revenue, margins, and the economics of every development decision.
A constructive environment for precious metals tends to lift the entire sector, and well-run producers can amplify those gains through operating leverage.
Key Catalysts Driving Investor Interest
Several potential catalysts keep Alamos Gold on watchlists. Chief among them are project milestones, permitting approvals, construction progress, and the ramp-up of expansion initiatives that could raise production and lower unit costs. Each successful step tends to de-risk the growth story and can re-rate the shares. Exploration success is another lever: because Alamos focuses on extending and expanding its existing assets, drilling results that add resources or extend mine life can be impactful. Cost performance is equally important; demonstrating that all-in sustaining costs are trending lower can shift investor perception of the company's quality. Capital-return decisions, including any dividends or buybacks, can also draw income-oriented investors. Finally, the macro catalyst of a sustained gold rally remains the most powerful driver, since it lifts cash flow across the portfolio simultaneously.
For AGI, the most durable catalysts are those that prove the organic-growth thesis is translating into real, repeatable margin expansion.
Financial and Valuation Considerations
When investors evaluate Alamos Gold, they typically weigh production growth against cost discipline and balance-sheet strength. Gold miners are often assessed on metrics such as all-in sustaining costs per ounce, free cash flow generation, and the relationship between enterprise value and reserves or production. A producer that can keep costs contained while growing output tends to command a premium valuation, because its margins expand faster than the gold price alone. Alamos has generally aimed to maintain a healthy balance sheet, which reduces the financial risk that can crush over-leveraged miners in downturns. Valuation in the sector is inherently sensitive to gold-price assumptions: a modest change in the metal's price can swing projected cash flows dramatically. Readers should treat any single multiple cautiously and instead focus on the qualitative picture, whether AGI is converting its growth investments into sustainable cash flow.
These are concepts to study, not precise figures to anchor to, given how quickly market conditions shift.
Growth Outlook and Project Pipeline
The growth outlook is central to the Alamos Gold story. The company's strategy revolves around squeezing more value from assets it already owns: expanding processing capacity, accessing higher-grade or larger deposits adjacent to existing mines, and advancing development projects toward production. This organic approach is designed to lift overall output while simultaneously driving down per-ounce costs through economies of scale and improved ore quality. A credible multi-year pipeline gives investors a roadmap for how production could climb over time, which is attractive in a sector where many miners struggle to replace depleting reserves. Successful execution would not only raise volumes but could also extend the lives of flagship operations, improving the long-term durability of cash flows. The key question for any observer is execution risk, whether projects are delivered on schedule and on budget.
If Alamos continues to convert its pipeline into producing ounces efficiently, the growth narrative could remain a defining feature of the AGI investment case.
Major Risks Investors Should Watch
No gold miner is risk-free, and Alamos Gold carries the standard hazards of the industry plus its own specifics. The most obvious is commodity-price risk: a sustained decline in gold would compress margins and could stall growth investments. Operational risks, equipment failures, lower-than-expected grades, geotechnical issues, or labor disruptions, can derail production and inflate costs. Even in stable jurisdictions, permitting delays, regulatory changes, and community or environmental considerations can slow projects. Currency movements matter too, since costs and revenues may be denominated in different currencies. Execution risk on expansion projects is real; overruns or delays can erode the value of the growth thesis. Reserve and resource estimates are inherently uncertain and can be revised. Finally, broader equity-market sentiment can move mining stocks regardless of company fundamentals.
Investors weighing AGI should recognize that the "safer" label is relative; it reflects jurisdictional and operational discipline, not immunity from the volatility that defines precious-metals equities.
What Could Drive the Stock Next
Looking ahead, the next moves in Alamos Gold shares are likely to hinge on a mix of company-specific execution and macro forces. On the company side, watch for evidence that expansion projects are ramping on schedule, that costs are trending lower, and that exploration is adding ounces. Consistent delivery against guidance tends to build investor confidence and can support a higher valuation. On the macro side, the trajectory of gold remains the dominant swing factor; a sustained move higher in bullion would lift cash flow across the portfolio and amplify the effect of operational improvements. Capital-allocation choices, balancing growth spending with returns to shareholders, could also influence sentiment, particularly among income-focused investors. Conversely, any operational stumble or a sharp gold pullback could pressure the shares.
The most constructive scenario for AGI would pair a firm gold environment with continued proof that its organic-growth model is delivering rising production and falling unit costs.
Conclusion
Alamos Gold has earned a place in the conversation about higher-quality gold equities by combining North American jurisdictional stability with cost discipline and an organic-growth strategy. Whether that profile makes it one of the "safer" precious-metals plays is ultimately a matter of perspective; what is clearer is that the company offers a coherent, repeatable model that contrasts with the boom-and-bust tendencies of riskier miners. For readers seeking to understand how a disciplined producer navigates the gold cycle, AGI provides a rich example. Yet the stock remains tethered to bullion's swings and to the perennial challenge of executing mine development on time and on budget. As always, Alamos Gold should be assessed analytically and in the context of one's own circumstances, not on its reputation or recent momentum alone.

 Nov 02, 2026
 Please wait processing your request...