
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks closed lower on Tuesday as rising Treasury yields and Middle East tensions added to Inflation concerns ahead of an expected 25-basis-point Federal Reserve rate hike. The S&P 500 fell 0.4%, the Nasdaq lost 0.6% and the Dow shed 328 points. Major technology stocks declined amid higher borrowing costs, while chipmakers recovered some ground from Monday’s selloff, led by gains in Nvidia and AMD.
Market Movers
Among the top-performing stocks of the session ReTo Eco-Solutions, Inc. surged 676.27%, while Veea Inc. rallied 149.34%. On the losing side, Future Fintech Group Inc. fell 28.61%, while Swarmer, Inc. declined 28.36%, making them the weakest performers during the trading day.
Commodities Update
Gold rose back above $4,300 an ounce and silver climbed above $64 on Wednesday as oil prices eased and bond yields steadied ahead of the US Federal Reserve’s policy decision. Investors expect a 25-basis-point rate hike and will watch for signals of further tightening later this year. Attention is also on the Bank of Japan, which is expected to raise rates, and the Bank of England, which is expected to hold them steady.
WTI crude fell to around $104 a barrel and Brent to around $108 on Wednesday, ending two sessions of gains after industry data showed a 7.1 million-barrel increase in US crude inventories. Supply concerns remained elevated, however, as Saudi Arabia’s East-West pipeline stayed offline, attacks threatened regional shipping routes, Aramco reportedly delayed some deliveries to Europe, and Libya experienced a supply halt.
Macro Updates
US Import and Export Prices Rebound in August
US import prices rose 0.7% in August 2026, exceeding expectations of 0.4%, as a 0.8% increase in nonfuel prices more than offset a slight decline in fuel prices. Export prices also rebounded, rising 0.6% after July’s revised 1.4% fall, with gains across agricultural and nonagricultural goods. On an annual basis, import prices increased 7.0% and export prices climbed 8.6%, indicating continued price pressure in US trade.
US Retail Sales Rebound in August
US retail sales rose 1.2% month over month in August 2026, beating forecasts of 0.8% and reversing July’s revised 0.5% decline. Gasoline stations led the gains, followed by online and other nonstore retailers. Sales in the categories used to calculate GDP jumped 1.4%, pointing to stronger consumer spending, although the figures are not adjusted for inflation.
Rising Mortgage Rates Weigh on US Applications
US mortgage applications fell 4.1% in the week ended September 11, extending the previous week’s 2.7% decline, as the average 30-year fixed mortgage rate rose to 6.97%, its highest level since May 2025. Refinancing applications dropped 8.8%, while purchase applications slipped 0.8%. The rise in mortgage rates followed higher Treasury yields amid inflation concerns and expectations of a Federal Reserve rate hike.
Fed Expected to Raise Rates Amid Inflation Concerns
The Federal Reserve is expected to raise its policy rate by 25 basis points to 3.75%–4.00% in September 2026, its first increase since 2023. Inflation remains above target, while higher energy prices add uncertainty to the outlook. Investors will also examine the Fed’s updated economic projections for clues about further rate increases this year.
Bonds Commentary
The US 10-year Treasury Yield hovered around 5% on Wednesday, near its highest level since July 2007, as investors awaited a widely expected 25-basis-point Federal Reserve rate hike. Traders will also watch for signals of another increase later this year. Elevated oil prices and fiscal concerns continued to support yields, although Treasury Secretary Scott Bessent said the US fiscal outlook had improved in 2026.
Futures Update
US Equity futures edged higher as investors weighed the impact of higher interest rates and concerns that AI safety calls could slow infrastructure spending. S&P 500 and Nasdaq 100 futures rose 0.3%, while Dow futures gained 100 points. Intel, Marvell and Dell each climbed more than 3% in premarket trading, ahead of an expected 25-basis-point Federal Reserve rate hike and closely watched economic projections.
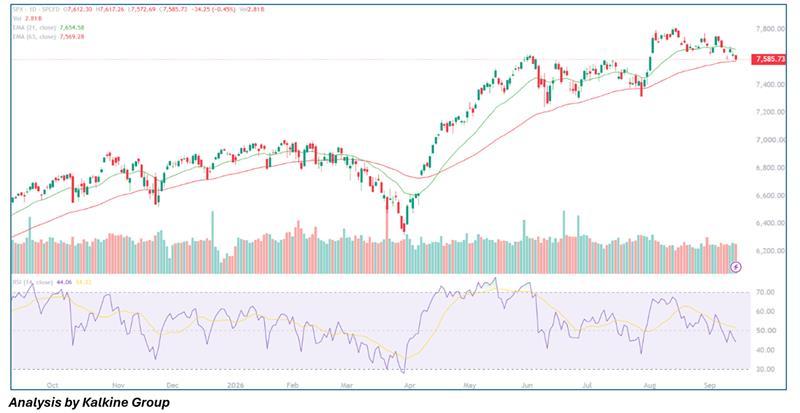
The S&P 500 index (SPX) extended its decline on Tuesday to log its lowest closing level in over a month, falling -0.45% (-34.25 points) to 7,585.73 after ranging between an opening print of 7,612.30, a morning high of 7,617.26, and an intraday trough of 7,572.69, decisively breaking beneath dynamic support at its rising 21-day EMA (7,654.58) to confirm intermediate momentum exhaustion below the 7,800.00 record highs. With the 14-day RSI sliding deeper into negative territory at 44.06 beneath its 51.33 signal line on steady Volume of 2.81B, price action remains vulnerable to an extended corrective mean-reversion down toward dynamic primary trend support at the ascending 63-day EMA (7,569.28), requiring buyers to stage a decisive close back above the 7,620.00–7,655.00 confluence band to neutralize the ongoing short-term pullback.


 Nov 02, 2026




 Please wait processing your request...