
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks closed higher on Monday as renewed AI optimism following Anthropic’s IPO filing lifted technology shares. The S&P 500 gained 0.7%, the Nasdaq rose 1.1% and the Dow added 146 points. Nvidia, Micron and AMD advanced, while Tesla surged 5.2% after a Barclays upgrade. Meta fell 1.9% amid plans to raise up to USD 95 billion through stock sales, while Verizon declined on weaker-than-expected revenue. Investors also awaited Earnings from Alphabet, Microsoft and Amazon.
Market Movers
Among the top-performing stocks of the session ClearOne, Inc. surged 52.92%, while Surgery Partners, Inc. rallied 47.62%. On the losing side, Cumberland Pharmaceuticals Inc. fell 48.76%, while XP Inc. declined 48.36%, making them the weakest performers during the trading day.
Commodities Update
Crude oil fell toward USD 100 per barrel, while Brent slipped below USD 115 on Tuesday, as renewed diplomatic efforts raised hopes of ending the US-Iran war and easing energy Supply pressures. Regional talks in Tehran and anticipated meetings in Moscow supported prospects for de-escalation. However, Houthi attacks, potential renewed conflict involving Hezbollah in Lebanon and upcoming regional elections continued to pose risks to stability and oil supplies.
Gold fell to around USD 4,000 per ounce, while silver slipped below USD 53 to near one-year lows on Tuesday, as a stronger dollar and caution ahead of Central Bank decisions weighed on precious metals. Renewed AI optimism following Anthropic’s IPO filing supported the dollar, while elevated oil prices sustained Inflation concerns despite recent declines. Investors expect the Federal Reserve to hold rates steady but will monitor its guidance for signs of a possible December hike, alongside upcoming US GDP and PCE inflation data.
Macro Updates
US Durable Goods Orders Exceed Expectations in September
US durable goods orders rose 1.8% month-on-month in September 2026, exceeding expectations of 1.5% and August’s revised 0.1% increase. Growth was driven by a 4.6% rebound in transportation orders, including a 28.4% surge in civilian aircraft bookings. Excluding transportation, orders increased 0.5%, while orders excluding defense climbed 2.2%. Core Capital Goods orders, a key indicator of Business Investment plans, rose 0.5%, slowing from August’s 1.6% gain.
Dollar Hits Two-Week High Ahead of Central Bank Decisions
The dollar index rose to 102.2 on Tuesday, extending gains for a third session as investors awaited policy decisions from major central banks. The Federal Reserve is expected to hold rates steady, with attention focused on guidance regarding a possible December hike. Improved sentiment towards AI stocks also supported the greenback, while France’s fiscal challenges and Bond Market concerns weighed on the euro. The ECB, Bank of Japan and Bank of Canada are also scheduled to announce decisions this week.
Bonds Commentary
The US 10-year Treasury Yield held below 5% after a three-week decline brought it to one-month lows. Investors awaited the Fed’s expected rate hold, guidance on a possible December hike, and upcoming GDP and PCE inflation data. Meanwhile, falling oil prices eased inflation concerns.
Futures Update
US stock futures rose on Tuesday as easing oil prices supported sentiment ahead of the Federal Reserve’s policy decision. S&P 500 and Nasdaq 100 futures gained 0.3% and 0.5%, respectively, while Dow futures added 130 points. Nvidia advanced following plans to invest USD 3 billion in Meta, while Boeing and UPS gained on improved results and guidance. Coca-Cola declined despite exceeding earnings expectations, while Alphabet and Amazon edged higher ahead of their earnings releases.
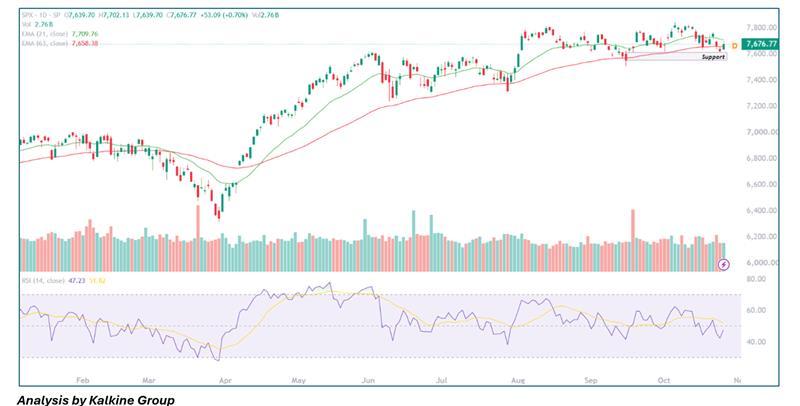
Wall Street shook off late-week selling on Monday as buyers stepped in across the board, pushing all major averages higher into the close even as initial session peaks were faded. Leading the technical turnaround, the S&P 500 added 0.70% to settle at 7,676.77, validating the key 7,550–7,600 support band and recapturing its 63-day EMA at 7,658.38. Price action formed an open-at-low structure at 7,639.70 before climbing to 7,702.13, showing strong directional control throughout regular trading hours. Momentum turned constructive as the 14-day RSI bounced to 47.23, approaching its 51.82 signal line to reflect seller exhaustion. The key technical threshold now sits overhead: while holding above 7,639–7,658 keeps the recovery leg intact, bulls must clear dynamic resistance at the 21-day EMA (7,709.76) on a closing basis to mount an assault on the 7,780–7,800 range ceiling.

 Oct 26, 2026
 Please wait processing your request...