
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US equities closed modestly lower on Monday, with the S&P 500 down 0.1%, the Nasdaq falling 0.3% and the Dow losing 61 points, as rising oil prices and bond yields intensified concerns over energy-driven Inflation and potential Fed rate increases. Nvidia dropped 2.9%, Intel fell 4.1% and Apple declined 1.5%, while financial stocks were mostly weaker. Conversely, strong cloud-demand expectations supported Microsoft, up 1.2%, and SpaceX, which gained 4.2%.
Market Movers
Among the top-performing stocks of the session Socket Mobile, Inc. surged 451.67%, while Jowell Global Ltd. rallied 158.06%. On the losing side, Sionna Therapeutics, Inc. fell 91.18%, while AirSculpt Technologies, Inc. declined 45.11%, making them the weakest performers during the trading day.
Commodities Update
WTI crude climbed above USD 83 per barrel for a fourth consecutive session, while Brent advanced to around USD 89 for a fifth straight gain, as fading prospects of a US-Iran agreement to fully reopen the Strait of Hormuz heightened Supply concerns. President Trump’s additional compensation demands complicated negotiations, although advanced Oman-Iran talks offered some optimism. Prices were further supported by US Strategic Petroleum Reserve inventories falling to their lowest level in over four decades.
Gold slipped below USD 4,400 per ounce and silver eased toward USD 64 as investors locked in gains following strong rallies and assessed the inflationary impact of rising oil prices. Despite the pullback, gold remained supported by increased Chinese institutional, ETF and central-bank demand, while silver benefited from robust solar and power-grid consumption and a 62.5% YoY rise in China’s June imports of silver-bearing ores. Markets also awaited US inflation data amid persistent US-Iran uncertainty.
Macro Updates
US Small-Business Optimism Reaches an 11-Month High
The NFIB Small Business Optimism index rose to 99.8 in July 2026 from 97.4 in June, exceeding the 97.5 forecast. Hiring plans reached their highest level since October 2022, with 20% of owners planning to add jobs, although labor availability remained the leading concern. Selling-price increases and pricing intentions eased, while weaker sales expectations, low inventory assessments and increased uncertainty over expansion and Capital spending tempered the improvement.
Dollar Holds Firm Ahead of US Inflation Data
The dollar index stabilised near 99.7, retaining previous-session gains as investors awaited US consumer and producer inflation data for clues on Federal Reserve policy. Markets increased the probability of a 25-basis-point September rate hike to 51% from 44%, while Cleveland Fed President Beth Hammack suggested that several increases may be required to restore inflation to the 2% target. Persistent US-Iran uncertainty also sustained concerns about energy-driven inflation and interest rates.
Bonds Commentary
The US 10-year Treasury Yield climbed above 4.7%, nearing its highest level since January, as rising oil prices and persistent US-Iran tensions heightened inflation concerns. Markets raised the probability of a 25-basis-point Fed rate hike in September to 51% from 44% a day earlier. Investors are awaiting key US inflation data, while Cleveland Fed President Beth Hammack indicated that multiple rate increases may be required to restore inflation to the 2% target.
Futures Update
US stock futures turned slightly higher, with the S&P 500 approaching a record, as optimism over a potential US-Iran agreement eased oil-price and inflation concerns. Lower bond yields supported bank stocks, while Nvidia rose 1.5% after securing USD 500 billion in private bank financing for AI infrastructure. Intel fell another 1.5% after increasing its planned stock sale to USD 20 billion. Investors now await US CPI data amid speculation of a possible Fed rate hike next month.
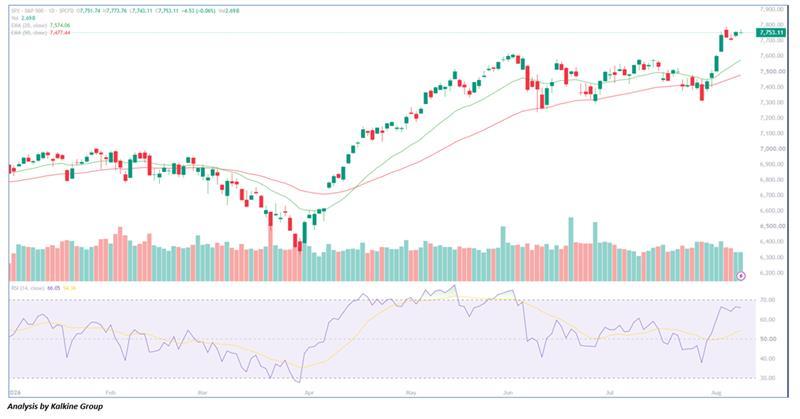
Following the strong gains recorded last week, stocks lacked a clear direction on Monday, with the major averages fluctuating around the unchanged line before ending modestly lower. Despite the subdued session, the S&P 500 retains a bullish intraday bias, holding well above its key moving averages after recently reaching fresh highs. The index closed near 7,753, comfortably above its 20-day EMA around 7,575 and 50-day EMA near 7,477, highlighting the strength of the prevailing trend. The RSI remains near 66, reflecting healthy positive momentum without signaling extreme overbought conditions. On the upside, a sustained move above 7,780 could pave the way toward 7,850–7,900, while immediate support is positioned around 7,700–7,650. Although the sharp recent rally could trigger some consolidation or profit-taking in the near term, the overall technical outlook remains constructive as long as the index holds above the 7,650–7,700 support zone.

 Nov 18, 2026
 Please wait processing your request...