
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks closed higher on Wednesday, led by a 2.3% gain in the Nasdaq, as CoreWeave’s strong sales growth and raised guidance lifted AI-related shares. The S&P 500 rose 1.3% and the Dow added 255 points. CoreWeave jumped 24.7%, while Micron gained 11.9%, AMD rose 7.3%, Broadcom advanced 4% and Nvidia added 2.9%. Reports of strong Demand for Anthropic’s planned IPO, which targets a USD 1.5 trillion valuation, also supported sentiment. Trading was light, with US bond markets closed for Veterans Day.
Market Movers
Among the top-performing stocks of the session ReTo Eco-Solutions, Inc. surged 65.95%, while Shengfeng Development Limited. rallied 43.88%. On the losing side, Ohmyhome Limited. fell 51.85%, while SMX (Security Matters) Public Limited Company. declined 41.87%, making them the weakest performers during the trading day.
Commodities Update
US crude rose toward USD 87 per barrel and Brent climbed above USD 93 on Thursday, recovering some of the week’s losses as US–Iran talks remained stalled. Tehran refused to give up its enriched nuclear material and demanded sanctions relief and an end to the US naval blockade before reopening the Strait of Hormuz. Since late October, Ukrainian drone strikes have disrupted refineries accounting for about 30% of Russia’s oil-processing capacity. Despite Thursday’s rebound, US crude remained nearly 20% below its October peak and Brent more than 20% below its own, as Middle Eastern supplies recovered and Saudi Arabia reported a 26% rise in October output.
Gold fell below USD 4,000 an ounce on Thursday, marking its third straight decline, while silver slipped toward USD 51 as stronger-than-expected US Inflation and hawkish Federal Reserve comments lifted the dollar. Fed Governor Christopher Waller said a 50-basis-point rate hike in December may be needed, while Dallas Fed President Lorie Logan backed at least two further 25-basis-point increases. Markets priced in a roughly 91% chance of a December hike as investors awaited US jobless claims, existing home sales and producer inflation data.
Macro Updates
US Dollar index Holds Near 103 as Fed Rate Hike Expectations Rise
The US Dollar Index held just below 103 on Thursday after gaining more than 1% over the previous two sessions to reach its highest level since April 2025. Stronger-than-expected October inflation and hawkish Federal Reserve comments supported the rally. Markets priced in a roughly 91% chance of a December rate hike as investors awaited US jobless claims and existing home sales data.
Bonds Commentary
The 10-year US Treasury Yield held near 5% on Thursday as stronger-than-expected October inflation and hawkish Federal Reserve comments reinforced expectations of further rate hikes. Fed Governor Christopher Waller said a 50-basis-point December increase could be justified, while Dallas Fed President Lorie Logan backed at least two more 25-basis-point hikes. Markets priced in a roughly 91% chance of a December hike as investors awaited US jobless claims and existing home sales data.
Futures Update
US stock futures were mixed on Thursday, with Nasdaq 100 futures down 1% and S&P 500 futures down 0.5%, while Dow futures were flat. Nvidia fell 8% in premarket trading amid reports that its board was considering removing co-founder and CEO Jensen Huang. AMD and Intel each fell 3%, while Nebius dropped nearly 10% after reporting earnings. Other sectors rebounded modestly despite expectations of further Federal Reserve rate hikes following Tuesday’s stronger-than-expected inflation reading.
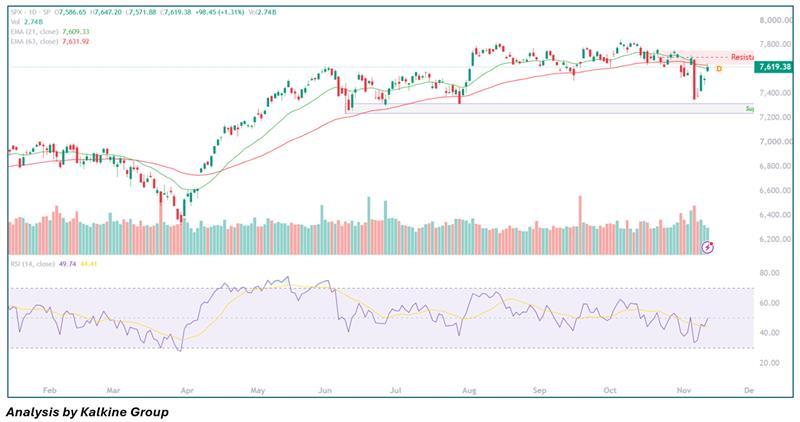
The S&P 500 Index (SPX) faces a muted intraday bearish bias, trading at 7,619.38 (+1.31% / +98.45 pts) after pushing directly into a heavy confluence of overhead resistance between the 63-day EMA (7,631.92) and the multi-month Supply ceiling at 7,650.00–7,730.00. Despite the strong rebound off the 7,571.88 intraday low, upward conviction appears tempered as session Volume contracted to 2.74B shares compared to recent distribution spikes, while the 14-day RSI stalls just beneath the neutral 50 midpoint at 49.74. With price action testing the upper boundary of its recovery range without volume expansion, failure to secure a clean breakout above the 7,647.20 session high and the 7,631.92 Moving Average barrier favors a mild mean-reversion pullback toward the 21-day EMA (7,609.33) and the 7,571.88 intraday floor, with deeper downside risk capped near the 7,500.00 psychological pivot.

 Nov 19, 2026
 Please wait processing your request...