
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks closed mixed on Friday as a renewed chip selloff pulled the S&P 500 down 0.4% and the Nasdaq down 1.2%, while the Dow edged up 51 points. AMD led the chip declines with an 8.7% drop, followed by Broadcom at 4.9%, Micron at 2.5% and Nvidia at 2%. Investors remained cautious ahead of Nvidia’s Earnings amid scrutiny of its sales to China. Producer price data showed higher energy costs were pushing up factory costs, reinforcing expectations of further Fed rate hikes. For the week, the S&P 500 gained 1.4%, the Nasdaq 100 rose 2.1% and the Dow added 472 points.
Market Movers
Among the top-performing stocks of the session Focus Universal Inc. surged 136.00%, while VirTra, Inc. rallied 61.83%. On the losing side, Suncrete, Inc. fell 37.44%, while Neuropace, Inc. declined 37.10%, making them the weakest performers during the trading day.
Commodities Update
WTI crude traded near USD 88 per barrel and Brent near USD 95 on Monday as investors weighed renewed tensions in the Middle East against signs of ample supply. Iran’s strike on a US helicopter base in Bahrain and reports of attacks on shipping raised concerns about regional oil flows, though Tehran signaled openness to diplomacy and President Trump said further US strikes might be unnecessary. The International Energy Agency projected a global oil surplus of about 2 million barrels per day this quarter as shipments through the Strait of Hormuz gradually recover.
Gold fell toward USD 3,800 per ounce on Monday, its lowest level in more than a year, while silver slid toward USD 47 per ounce, a one-year low. A stronger US dollar and elevated Treasury yields weighed on both metals as Inflation concerns fueled expectations of further Federal Reserve tightening. Markets priced in a 92% chance of a 25-basis-point hike in December and an 8% chance of a 50-basis-point increase. Investors awaited remarks from Fed Chair Kevin Warsh later on Monday and the October FOMC minutes on Wednesday. Weaker Demand from jewelry and solar cell manufacturers added pressure on silver.
Macro Updates
US Dollar Holds Near Highest Level Since April 2025 as Fed Rate Hike Expectations Strengthen
The US dollar index traded near 103.4 on Monday as strong October inflation data and hawkish remarks from Federal Reserve officials reinforced expectations of further tightening. Markets priced in a 92% chance of a 25-basis-point hike in December and an 8% chance of a 50-basis-point increase, with traders anticipating four additional hikes by September 2027. Investors awaited Fed Chair Kevin Warsh’s remarks later on Monday and Wednesday’s release of the October FOMC minutes for clues on the pace of tightening.
Bonds Commentary
The US 10-year Treasury Yield eased to 5.13% on Monday from Friday’s one-month high as oil prices edged lower. Stronger-than-expected October inflation and hawkish comments from Fed officials pushed the market-implied probability of a 25-basis-point December rate hike above 93%. Investors awaited Fed Chair Kevin Warsh’s remarks in Milan later on Monday and Wednesday’s FOMC minutes for clues on the timing of further tightening.
Futures Update
US stock futures pointed to a third straight session of losses on Monday as chipmakers fell ahead of Nvidia’s Tuesday earnings. S&P 500 futures slipped 0.7%, Nasdaq 100 futures dropped more than 1%, and Dow futures edged lower. Nvidia fell nearly 4% in premarket trading as investors awaited clarity on its role in financing the AI sector following Jensen Huang’s departure as CEO. Micron, AMD, Intel and Broadcom each fell around 5% despite reports that Anthropic’s IPO was six times oversubscribed. Walmart gained 1% ahead of Thursday’s results, while bank stocks were flat.
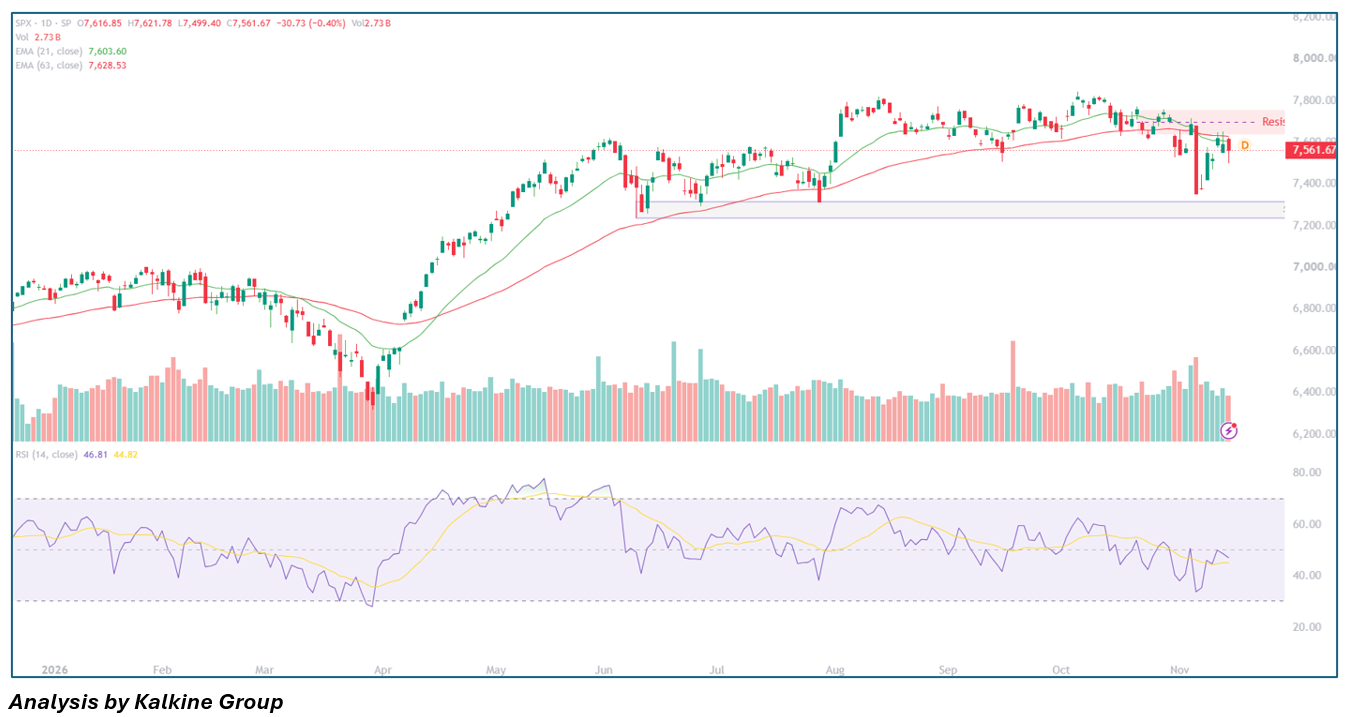
The S&P 500 Index (SPX) exhibits a cautious intraday consolidation-to-bearish pullback bias, slipping -0.40% (-30.73 pts) to trade at 7,561.67 after opening at 7,616.85, testing an intraday high of 7,621.78, and dipping to a session low of 7,499.40 on Volume of 2.73B shares. Price action faced immediate overhead rejection right at the dynamic resistance cluster formed by the 21-day EMA (7,603.60) and 63-day EMA (7,628.53), leaving spot pinned beneath the broader multi-month Supply ceiling pegged between 7,650.00 and 7,730.00. Momentum has softened beneath the neutral midpoint, with the 14-day RSI rolling over slightly to 46.81 (holding marginally above its 44.82 signal line), reflecting hesitation among buyers following recent rebound attempts. As long as price remains capped below the 7,603.60–7,628.53 Moving Average barrier, two-way range rotation is likely to persist with immediate focus on whether bulls can defend the 7,499.40–7,500.00 psychological floor, whereas a decisive breakdown exposes a deeper retest of the primary demand shelf near 7,240.00–7,320.00.

 Nov 13, 2026
 Please wait processing your request...