
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US equities closed higher on Friday ahead of earnings season, with the S&P 500 gaining 0.4%, the Nasdaq 100 rising 0.3% and the Dow adding 150 points. Sentiment was supported by SK Hynix’s strong US market debut, gains in Nvidia, AMD and Meta, and easing oil prices that reduced concerns over another Federal Reserve rate hike. Financial, industrial and manufacturing stocks also advanced, although performance across the semiconductor sector remained mixed.
Market Movers
Among the top-performing stocks of the session Global Mofy AI Limited. surged 147.03%, while Jiuzi Holdings, Inc. rallied 85.47%. On the losing side, Virax Biolabs Group Limited. fell 35.85%, while Silo Pharma, Inc. declined 26.26%, making them the weakest performers during the trading day.
Commodities Update
Crude oil prices rose more than 3% on Monday, with WTI reaching around USD 74 per barrel and Brent climbing above USD 78, after renewed US strikes on Iran heightened concerns over Middle Eastern supply disruptions. Uncertainty persisted over the Strait of Hormuz, as Iran claimed the waterway was closed while Western forces said commercial shipping remained possible. Regional tensions intensified following Iranian attacks on US allies and reported damage to a Kuwaiti offshore drilling platform, while subdued tanker traffic and continued operation of the Omani shipping corridor offered limited reassurance.
Gold fell below USD 4,100 per ounce and silver slipped under USD 59 on Monday as renewed US-Iran strikes pushed oil prices higher, strengthening expectations that persistent inflation could prompt another Federal Reserve rate hike this year. Market sentiment was also pressured by uncertainty over the Strait of Hormuz, while investors awaited upcoming US inflation data and Fed Chair Kevin Warsh’s first congressional appearance for further policy signals.
Macro Updates
The US dollar index rose above 101 on Monday, extending gains for a second session as escalating US-Iran tensions boosted safe-haven demand and pushed oil prices higher. The resulting inflation concerns reinforced expectations of one additional Federal Reserve rate hike this year, while investors awaited upcoming US inflation data and Fed Chair Kevin Warsh’s congressional testimony for clearer policy signals.
Bonds Commentary
The US 10-year Treasury yield rose to around 4.59% on Monday, near a seven-week high, as renewed US-Iran strikes pushed oil prices higher and reinforced expectations of another Federal Reserve rate increase to contain inflation. Investors also awaited key US inflation data and Fed Chair Kevin Warsh’s congressional testimony for further policy signals, while recent Fed minutes showed that some officials had considered raising rates before ultimately supporting no change.
Futures Update
US equity futures declined on Monday, with the Nasdaq 100 falling more than 1% and the S&P 500 down 0.3%, as renewed weakness in AI and semiconductor stocks compounded broader macroeconomic concerns. SK Hynix ADRs dropped 8% following a broker warning over potential earnings disappointment, while Nvidia, AMD, Intel, Micron and Sandisk also traded lower. Sentiment was further pressured by continued US-Iran strikes, which threatened Middle Eastern energy exports, inflation and borrowing costs, while major banks remained mixed ahead of upcoming earnings.
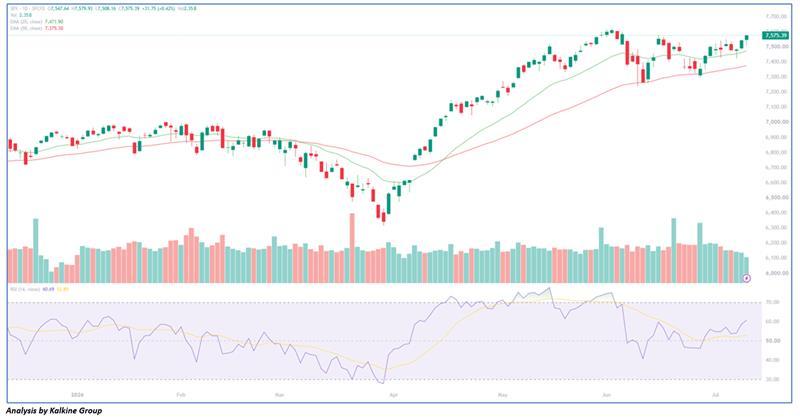
After a directionless start to Friday's session, U.S. stocks gained momentum as the day progressed, with the major averages closing modestly higher. Although buying interest remained relatively cautious and the indices eased from their intraday highs late in the session, the broader market still finished in positive territory. From a technical perspective, the S&P 500 continues to exhibit a constructive near-term trend, holding comfortably above both its 20-day EMA (7,472) and 50-day EMA (7,375), reinforcing the prevailing bullish structure. The RSI near 61 points to improving momentum without signaling overbought conditions, while the index remains in consolidation near record highs. As long as the S&P 500 stays above the 20-day EMA, the bullish outlook is expected to remain intact, with a decisive breakout above the recent highs likely to extend the ongoing uptrend.

 Nov 19, 2026
 Please wait processing your request...