
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US equities closed lower on Thursday as rebounding energy prices and rising Treasury yields strengthened expectations of a potential Federal Reserve rate hike. The S&P 500 declined 0.2%, the Nasdaq 100 fell 0.4% and the Dow lost 464 points amid renewed Strait of Hormuz tensions and hawkish Fed signals. Financial and technology stocks weakened, Western Digital and Sandisk fell sharply following disappointing updates, while SpaceX gained 6.1% despite a USD 101 billion post-IPO share unlock.
Market Movers
Among the top-performing stocks of the session TEN Holdings, Inc. surged 252.57%, while ClearOne, Inc. rallied 166.30%. On the losing side, ThredUp Inc. fell 50.48%, while BillionToOne, Inc. declined 38.89%, making them the weakest performers during the trading day.
Commodities Update
WTI crude traded near USD 77 per barrel and Brent remained below USD 82 on Friday as markets balanced hopes for a partial reopening of the Strait of Hormuz against renewed geopolitical tensions. Negotiations remained strained over Iran’s proposed restrictions and transit fees, while explosions near Qeshm Island, reported Iranian attacks and intensified Houthi activity raised fresh concerns about regional stability and shipping security.
Gold advanced toward USD 4,300 per ounce, while silver exceeded USD 63 to reach a six-week high, as investors awaited the US jobs report for signals on labour conditions and the Federal Reserve’s interest-rate outlook. Middle East tensions and higher oil prices reinforced inflation concerns, while gold benefited from Chinese institutional and central-bank demand and silver gained additional support from strong industrial consumption and a 62.5% surge in China’s silver-bearing ore imports.
Macro Updates
US Labour Market Expected to Remain Resilient
The US economy likely added 80,000 jobs in July 2026, improving from 57,000 in June, led by healthcare and a recovery in leisure and hospitality. The unemployment rate is expected to remain at 4.2%, while average hourly earnings likely increased 0.3% month over month and 3.5% year over year, indicating relatively stable labour-market conditions.
Dollar Holds Steady Ahead of US Jobs Report
The US Dollar Index remained near 99.95 as investors awaited the July employment report for clearer signals on the Federal Reserve’s policy outlook. Expectations of a 25-basis-point rate hike in September, hawkish Fed commentary and renewed inflation concerns stemming from higher oil prices provided support to the currency.
US Imposes Tariffs and Price Floors on Polysilicon Imports
The Trump administration introduced a 15% tariff and minimum import prices for polysilicon and related solar products under Section 232 to protect domestic manufacturers and counter China’s expansion in the semiconductor supply chain. The measures also allow the Commerce Department to establish incentives for companies investing in US production facilities for polysilicon and derivative products.
Bonds Commentary
The US 10-year Treasury yield held near 4.68% as investors awaited the July employment report for signals on labour-market strength and Federal Reserve policy. Expectations of a 25-basis-point September rate hike strengthened amid hawkish Fed commentary, persistent inflation pressures and higher oil prices driven by renewed tensions in the Strait of Hormuz.
Futures Update
US stock futures were slightly higher on Friday as investors awaited the July employment report, which is expected to show 80,000 new jobs and stable unemployment, potentially reinforcing expectations of a Federal Reserve rate hike. Energy-driven inflation concerns and hawkish Fed signals remained key market influences, while SpaceX held its rebound despite a major share unlock, Sandisk and Western Digital rallied in premarket trading, and Berkshire Hathaway was little changed ahead of earnings.
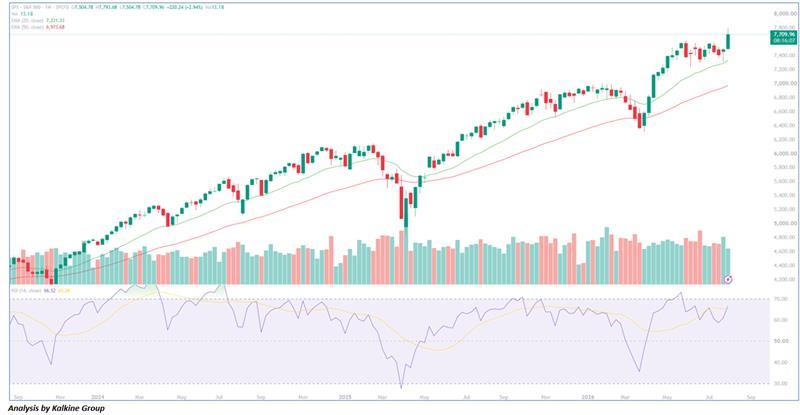
Despite choppy trading and a lack of clear direction for much of Thursday's session, the S&P 500 continues to maintain a strong bullish structure after recently breaking out to fresh record highs. Although the major averages ended modestly lower, the index remains well above its 21-day and 50-day EMAs, underscoring the strength of the prevailing uptrend. The 14-day RSI is hovering around 66, reflecting healthy bullish momentum without entering overbought territory. As long as the S&P 500 holds above the key support zone of 7,650–7,680, the broader uptrend is expected to remain intact, with immediate resistance seen in the 7,750–7,800 range. A decisive breakout above this level could pave the way for further gains, while any short-term dips are likely to attract buying interest.

 Nov 03, 2026





 Please wait processing your request...