
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks closed higher on Friday as strong Business activity data helped offset concerns over elevated bond yields and fiscal pressures. The S&P 500 gained 0.4%, the Nasdaq 100 rose 0.3% and the Dow added 518 points. Major technology stocks advanced, chipmakers traded mixed, while Walmart lost more than 10% over the week following an Earnings miss and concerns over consumer demand.
Market Movers
Among the top-performing stocks of the session Wetour Robotics Limited. surged 32.59%, while ARB IOT Group Limited. rallied 32.17%. On the losing side, Profusa, Inc. fell 44.22%, while IP Strategy Holdings, Inc. declined 38.04%, making them the weakest performers during the trading day.
Commodities Update
Crude oil prices eased after a strong weekly rally, with WTI near USD 85 per barrel and Brent around USD 93, as investors booked profits ahead of sweeping new US sanctions against Iran. The measures are expected to target Iran’s banking, energy, aviation and Cryptocurrency sectors, along with countries and entities maintaining trade ties with Tehran, potentially further restricting Iranian oil exports. Meanwhile, Iran has threatened penalties and vessel seizures for transit-rule violations in the Strait of Hormuz, keeping supply-disruption risks elevated as traffic through the key oil route remains well below normal levels.
Gold rose nearly 1% above USD 4,650 per ounce, while silver traded above USD 69 near a two-month high, supported by a weaker dollar and lower Treasury yields following expanded US government Debt buybacks. Concerns over fiscal sustainability, escalating US-Iran tensions and renewed trade uncertainty also strengthened safe-haven demand. Investors are now awaiting July PCE Inflation data and Fed Chair Kevin Warsh’s Jackson Hole speech for further signals on the interest-rate outlook.
Macro Updates
US Dollar Remains Under Pressure Amid Debt Concerns
The US dollar index held near 98.8 after steep weekly losses, pressured by concerns over the rising federal debt burden and the Treasury’s plan to buy back longer-dated securities. Investors also monitored escalating US-Iran tensions while awaiting July PCE inflation data and Fed Chair Kevin Warsh’s Jackson Hole speech for monetary-policy signals.
Bonds Commentary
The US 10-year Treasury Yield eased to 4.71% as investors awaited July PCE inflation data and Fed Governor Kevin Warsh’s Jackson Hole speech for signals on monetary policy. Persistent inflation and federal debt exceeding USD 40 trillion continued to fuel fiscal concerns, while the Treasury’s plan to expand long-dated securities Buybacks provided only temporary relief to the bond market.
Futures Update
US stock futures declined as elevated Global Bond yields and concerns over the prolonged US-Iran conflict kept investors cautious. Major US indices posted weekly losses after the 30-year Treasury yield climbed above 5.3%, raising inflation and interest-rate concerns. Markets now await new sanctions on Iran, July PCE inflation data, Fed Chair Kevin Warsh’s Jackson Hole speech, and earnings from Nvidia and Marvell Technology.
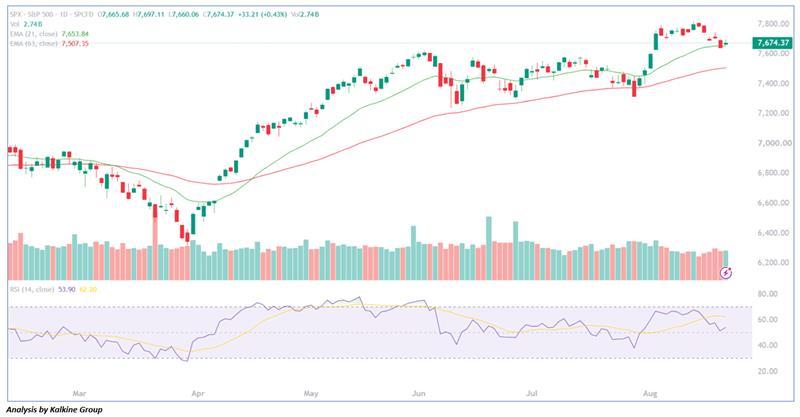
The S&P 500 pared back some of its early-session gains on Friday but stayed mostly positive, partially offsetting the previous day's steep losses. The index closed around 7,674.37 (+33.21 / +0.43%), trading between a low of 7,660.06 and a high of 7,697.11 on Volume of about 2.74B shares. It's holding above both the 21-day EMA (7,653.84) and 63-day EMA (7,507.35) — a bullish sign structurally — even as it eases off mid-August highs near 7,750–7,800. RSI (14) at 53.90, below its 62.20 signal line, points to cooling momentum after the recent rally, suggesting the market is consolidating rather than extending gains aggressively.


 Nov 02, 2026




 Please wait processing your request...