
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity

Index Update
US stocks rallied on Monday as easing US-Iran tensions and renewed confidence in AI-linked shares lifted sentiment, with the S&P 500 up 1.2%, Nasdaq 100 up 2.3%, and Dow gaining 307 points to a record high. Gains were led by Alphabet, Tesla, Amazon, Meta, Nvidia, and Comcast, while materials lagged and Apple, Microsoft, Walmart, and Verizon declined.
Market Movers
Among the top-performing stocks of the session Universe Pharmaceuticals Inc. surged 311.49%, while Decoy Therapeutics Inc. rallied 73.79%. On the losing side, Evommune, Inc. fell 40.23%, while Eshallgo Inc. declined 31.01%, making them the weakest performers during the trading day.
Commodities Update
Crude oil and Brent traded near USD 70.7 and USD 74 per barrel, respectively, on Tuesday, marking a roughly 30% Q2 decline and their steepest quarterly fall since 2020, as easing Strait of Hormuz disruptions, higher Gulf traffic, and US sanction waivers for Iranian oil added fresh supply to an already pressured market, while ongoing US-Iran negotiations in Doha and Tehran’s push to regulate maritime flows through the strait kept geopolitical uncertainty in focus.
Gold and silver remained volatile on Tuesday, trading near USD 4,000 and USD 59 an ounce, respectively, as Fed rate-hike expectations and Middle East uncertainty pressured sentiment, with gold down about 11% for the month and 14% for the quarter, while silver fell more than 23% over the same period; investors now await US employment data and US-Iran peace talks in Doha for further direction.
Macro Updates
US Strategic Petroleum Reserve Falls to Multi-Decade Low
US Strategic Petroleum Reserve crude inventories fell by 5.5 million barrels to 325.7 million in the week ended June 26, the lowest level since May 1983, as the US continued releasing reserves to ease post-Iran war supply shortages and reduce fuel prices. Strong export and refining demand further accelerated the stock drawdown, with total US crude inventories, including commercial and SPR stocks, declining by 111.4 million barrels since late February to 743.3 million as of June 19, the lowest level since 1984.
Dollar Strengthens on Fed Rate-Hike Expectations
The dollar index rose to around 101.2 on Tuesday, heading for its second straight monthly gain and its strongest monthly performance since July last year, supported by expectations of at least one Fed rate hike this year. Investors are awaiting the US jobs report for policy cues, while US-Iran peace talks and uncertainty over Strait of Hormuz oversight kept geopolitical risks in focus.
Bonds Commentary
The 10-year US Treasury yield fell below 4.38% on Tuesday, its lowest since early May, as lower energy prices eased inflation concerns and reduced expectations of a more hawkish Fed response. However, strong core inflation, resilient labor data, and debate over reducing the Fed’s Treasury holdings limited the decline in longer-term yields.
Futures Update
US stock futures were steady on Tuesday after Monday’s tech-led rally, with the S&P 500 up 1.18%, Nasdaq up 2.07%, and Dow up 0.59% to a record close, supported by easing geopolitical tensions ahead of US-Iran talks. After hours, AeroVironment surged nearly 21% on strong results, while Concentrix fell 22.5% after missing forecasts.
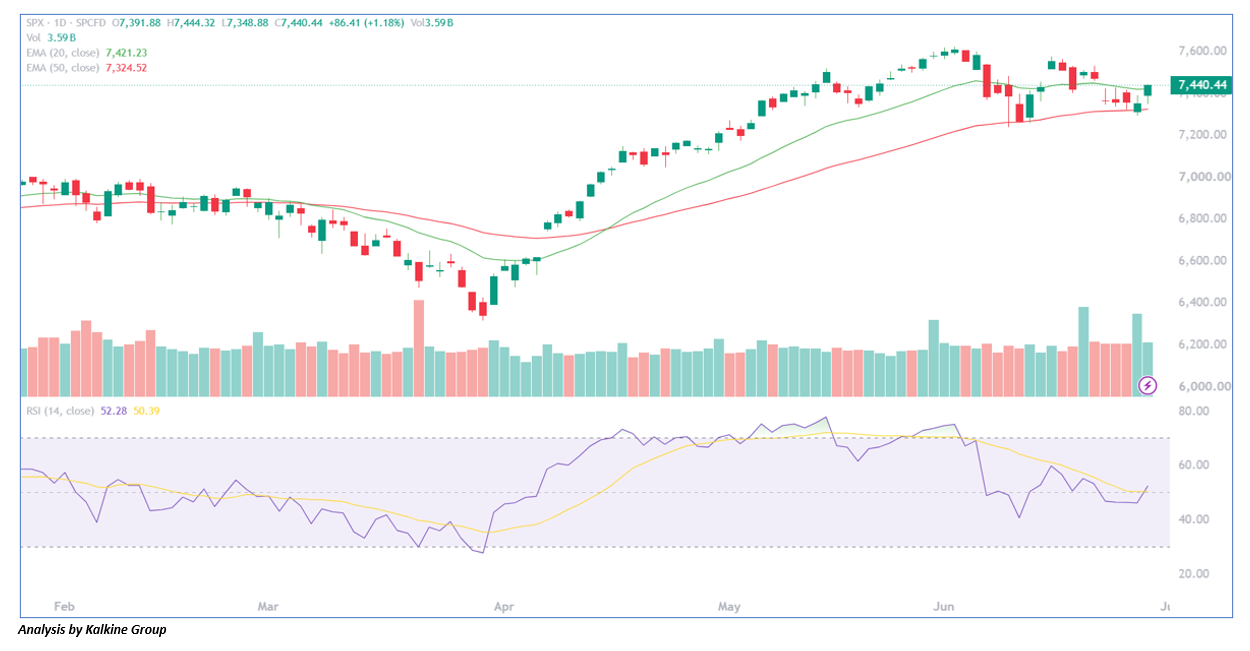
After experiencing notable volatility early in Monday's session, U.S. stocks staged a strong rebound, with the major indices finishing firmly in positive territory. The Dow Jones Industrial Average briefly climbed above the 52,000 mark to set a new record closing high before trimming some gains late in the session, while the Nasdaq and S&P 500 ended near their intraday highs. Technically, the S&P 500 has regained a constructive short-term outlook after rebounding from its 50-day EMA and reclaiming the 20-day EMA, signaling renewed buying interest. Momentum is also improving, with the RSI turning higher from around the 50 level without entering overbought territory, suggesting there is room for further upside. As long as the index holds above the 7,420–7,400 support zone, it could extend its recovery toward 7,500, with a potential retest of the recent highs around 7,580–7,600. However, a sustained break below 7,400 would weaken the near-term outlook and increase the risk of a deeper pullback toward the 50-day EMA near 7,325.

 Nov 04, 2026




 Please wait processing your request...