
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US equities closed mixed on Monday, with the S&P 500 broadly flat, the Nasdaq 100 down 0.3% and the Dow gaining 263 points. Semiconductor stocks declined amid concerns over AI-related financing and a potential slowdown in hyperscaler spending, while easing US-Iran tensions lowered oil prices and Treasury yields, supporting broader market sentiment. Major technology stocks also traded mixed ahead of key earnings releases and the Federal Reserve’s policy decision.
Market Movers
Among the top-performing stocks of the session T3 Defense Inc. surged 201.15%, while Baiya International Group Inc. rallied 116.06%. On the losing side, Instinct Bio Technical Company Holdings Inc. fell 82.32%, while AiRWA Inc. declined 73.51%, making them the weakest performers during the trading day.
Commodities Update
Crude benchmarks declined to multi-day lows on Tuesday, with WTI near USD 81 per barrel and Brent around USD 86.5, as signs of progress in US-Iran diplomacy eased immediate fears of supply disruptions. While Washington and Tehran indicated openness to negotiations and Oman proposed a regional shipping framework for the Strait of Hormuz, both sides warned of renewed retaliation if talks fail. Geopolitical risk nevertheless remains elevated, following drone threats to Saudi petroleum facilities and a claimed Houthi attack on the country’s East-West oil pipeline.
Gold declined to around USD 4,050 per ounce and silver slipped toward USD 57 on Tuesday as investors assessed a greater-than-one-third probability of a Federal Reserve rate hike on Wednesday. Expectations that the Fed may tighten policy to reinforce its inflation-fighting credibility pressured precious metals, while progress in US-Iran talks lowered oil prices and eased geopolitical and inflation concerns. However, downside risks were partly contained by warnings that US military action could resume if negotiations fail.
Macro Updates
Dollar Holds Firm Ahead of Fed Decision
The US dollar index remained near 101.5 as investors awaited the Federal Reserve’s policy decision, with markets pricing in more than a one-third probability of an immediate rate increase and a 56% chance of another move in September. The dollar stayed resilient despite progress in US-Iran negotiations lowering oil prices and easing inflationary pressures.
Bonds Commentary
The US 10-year Treasury yield declined for a third straight session to a one-week low of 4.62% as lower oil prices and a sustained US-Iran ceasefire boosted demand for government bonds. Investors are now focused on the Federal Reserve meeting, with rates expected to remain unchanged, while markets price a 35% chance of a cut and an approximately 80% probability of easing in September.
Futures Update
US equity futures were mixed on Tuesday, with the Nasdaq 100 down 1% as concerns over slowing hyperscaler AI spending and rising Chinese competition pressured chip stocks, including Micron, Sandisk, Nvidia and AMD. Meanwhile, the S&P 500 was flat and Dow futures gained 350 points as lower Treasury yields and easing energy prices supported banks, software and other non-technology sectors. JPMorgan and Visa advanced, while Coca-Cola rose 3% after raising its outlook.
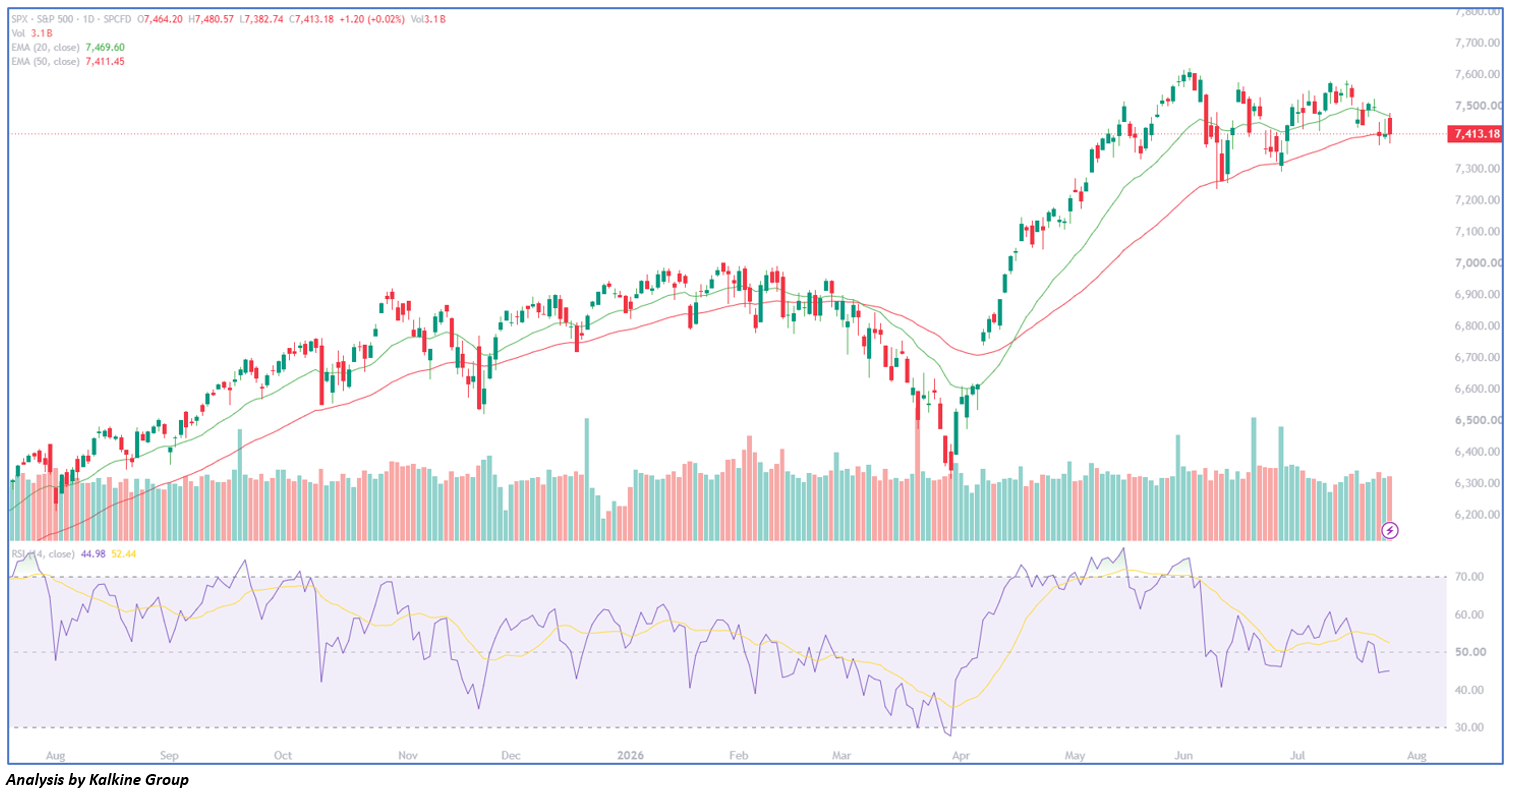
After an early attempt to move higher, stocks lost momentum on Monday, with the major averages giving back their gains and spending the rest of the session fluctuating around the unchanged mark before ending narrowly mixed. The S&P 500 continues to exhibit a slightly bearish intraday bias, trading below its 21-day EMA (7,470) while holding above the 50-day EMA (7,411), which remains an important support level. The RSI (14) has eased to around 45, signaling softer momentum but not yet indicating oversold conditions. As long as the index remains above the 50-day EMA, the broader uptrend is likely to stay intact, leaving room for a rebound toward the 7,470–7,500 resistance zone. However, a decisive break below 7,410 could strengthen bearish sentiment and open the door for a move toward the 7,320–7,350 support area.

 Nov 05, 2026

 Please wait processing your request...