
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks closed higher on Tuesday as lower oil prices eased Inflation concerns and pulled Treasury yields down. The S&P 500 gained 0.3%, the Nasdaq rose 0.6% and the Dow added 160 points, led by a rebound in technology and AI-related stocks. Nvidia climbed 2.2% ahead of its earnings, while AMD, Micron, Meta and Microsoft also advanced; financial stocks gained as lower yields supported credit-sensitive sectors.
Market Movers
Among the top-performing stocks of the session CID HoldCo, Inc. surged 124.28%, while Picard Medical, Inc. rallied 86.16%. On the losing side, Future Vision II Acquisition Corporation. fell 52.47%, while Dick's Sporting Goods Inc. declined 30.68%, making them the weakest performers during the trading day.
Commodities Update
Crude oil prices extended losses for a third session on Wednesday, with WTI falling toward USD 80 per barrel and Brent approaching USD 86, as Iran and Oman discussed a temporary maritime corridor in the Strait of Hormuz and planned further talks on a permanent arrangement. Diplomatic efforts involving Pakistan and Qatar also eased supply-disruption concerns, while softer-than-expected US measures against Iran—without secondary sanctions on its trading partners—added downward pressure on prices.
Gold eased below USD 4,650 an ounce while silver held above USD 68, both remaining near multi-month highs as investors awaited the US PCE inflation report and Fed Chair Kevin Warsh’s Jackson Hole speech. A weaker dollar, increased US Treasury Buybacks and easing inflation concerns following lower oil prices supported precious metals, while gold benefited from stronger Chinese Investment Demand and silver remained underpinned by green energy, electric vehicle and AI data-centre demand.
Macro Updates
US Mortgage Applications Decline as Borrowing Costs Remain Elevated
US mortgage applications fell 1.0% in the week ending August 21, extending the previous week’s decline, as the average 30-year fixed mortgage rate edged up to 6.78% from 6.77% and remained near a one-year high. Elevated Treasury yields, persistent inflation concerns and expectations of higher-for-longer Federal Reserve rates continued to weigh on housing demand, with refinancing applications falling 2.0% and purchase applications declining 0.3%.
US Dollar Holds Near Three-Month Low Ahead of PCE Data
The US Dollar index remained steady near 99 as investors awaited the PCE inflation report and Fed Chair Kevin Warsh’s Jackson Hole speech. Concerns over the Treasury’s expanded debt-buyback programme and longer-term US Debt risks continued to pressure the currency, while falling oil prices eased inflation fears and reduced safe-haven demand for the dollar.
US Crude Inventories Rise More Than Expected
US crude inventories increased by 4.2 million barrels in the week ended August 21, exceeding expectations for a 1.9 million-barrel build, while Cushing stocks rose by 1 million barrels. Crude production climbed to 13.83 million barrels per day, up 503,000 bpd year over year. Meanwhile, the Strategic Petroleum Reserve fell by 3.7 million barrels to 289.7 million, while gasoline and distillate inventories declined by 3.2 million and 500,000 barrels, respectively.
Bonds Commentary
The US 10-year Treasury Yield held near 4.64% on Wednesday after falling almost 10 basis points in the previous session, as lower oil prices eased inflation concerns. Investors continued to assess the Treasury Department’s expanded debt-buyback plan while awaiting the US PCE inflation report and Fed Chair Kevin Warsh’s Jackson Hole speech for signals on the monetary-policy outlook.
Futures Update
US stock futures were broadly unchanged on Wednesday as investors awaited the PCE inflation report and Nvidia’s quarterly Earnings for signals on interest rates and AI demand. On Tuesday, the Dow gained 0.3%, the S&P 500 rose 0.32% and the Nasdaq advanced 0.66%, supported by technology and AI-related stocks, lower Treasury yields and easing oil-driven inflation concerns.
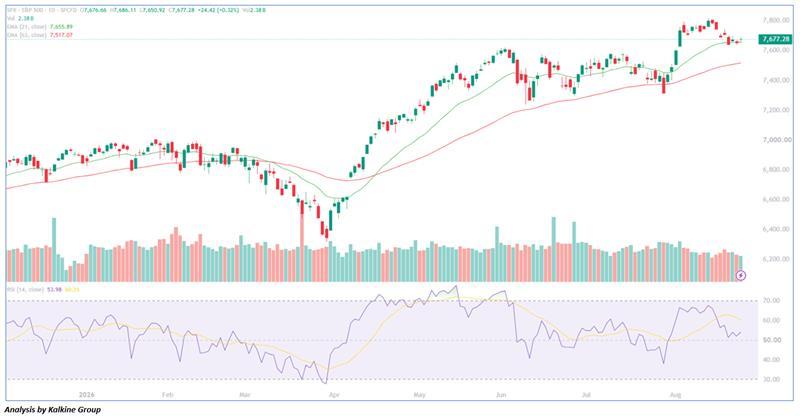
Wall Street closed higher across major averages on Tuesday as falling Crude Oil prices fueled an early rally, and despite giving up some initial gains, the benchmark index preserved a constructive tone to finish up 0.32% at 7,677.28. Technically, the market remains in a healthy consolidation phase above its rising 21-day EMA (7,655.89) and key intraday support at 7,650, while overhead resistance holds firm in the 7,700–7,720 zone ahead of recent highs near 7,800. With momentum holding steady (RSI ~54) on muted volume, the setup points toward neutral-to-bullish, range-bound trading with room for an intraday retest of upper resistance.

 Nov 04, 2026




 Please wait processing your request...