
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks closed higher on Monday as easing US-Iran tensions, lower fuel prices and declining Treasury yields strengthened risk appetite. The S&P 500 gained 1.5%, the Dow added 693 points to a record 53,178 and the Nasdaq 100 rose 1.8%, led by strong gains in megacap technology and semiconductor stocks. Investors now await earnings from SpaceX and AMD.
Market Movers
Among the top-performing stocks of the session Hydrofarm Holdings Group, Inc. surged 298.15%, while T3 Defense Inc. rallied 122.18%. On the losing side, PN Smart Energy Limited. fell 51.19%, while Inflection Point Acquisition Corp. III. declined 48.79%, making them the weakest performers during the trading day.
Commodities Update
WTI crude rose toward USD 81.8 per barrel and Brent approached USD 85 on Tuesday, recovering some of the previous session’s losses amid uncertainty over US-Iran negotiations and the reopening of the Strait of Hormuz. While President Trump expressed optimism about a potential agreement, Iran denied that direct talks were underway. Prices were tempered by improved alternative export routes, resumed Kazakh crude flows and a modest OPEC+ production increase.
Gold held near USD 4,050 per ounce, while silver rose to USD 59 on Tuesday as geopolitical uncertainty supported safe-haven demand. However, gains were limited by expectations of further monetary tightening, with markets pricing in a 63% probability of a September rate hike following hawkish signals from Federal Reserve policymakers. Investors are now focused on upcoming US labour-market data and developments in US-Iran negotiations.
Macro Updates
Dollar Holds Near 100 Amid Fed Policy Uncertainty
The dollar index hovered near 100 as investors assessed the likelihood of a September rate hike and awaited US job openings and trade data. The dollar also recovered against the yen following coordinated US-Japan intervention, although the possibility of further currency action kept markets cautious.
Bonds Commentary
The US 10-year Treasury yield held near 4.69% as investors assessed the Federal Reserve’s policy outlook amid Middle East uncertainty. Markets priced in a 65% probability of a 25-basis-point September rate hike, while attention shifted to upcoming JOLTS job openings and trade data for further economic signals.
Futures Update
US stock futures edged higher after strong Monday gains, when the Nasdaq rose 2.13%, the S&P 500 gained 1.48% and the Dow advanced 1.32%. Megacap technology stocks led the rally, while a roughly 5% decline in oil prices eased inflation and interest-rate concerns. Investors now await earnings from SpaceX, AMD, Caterpillar, Merck and McDonald’s.
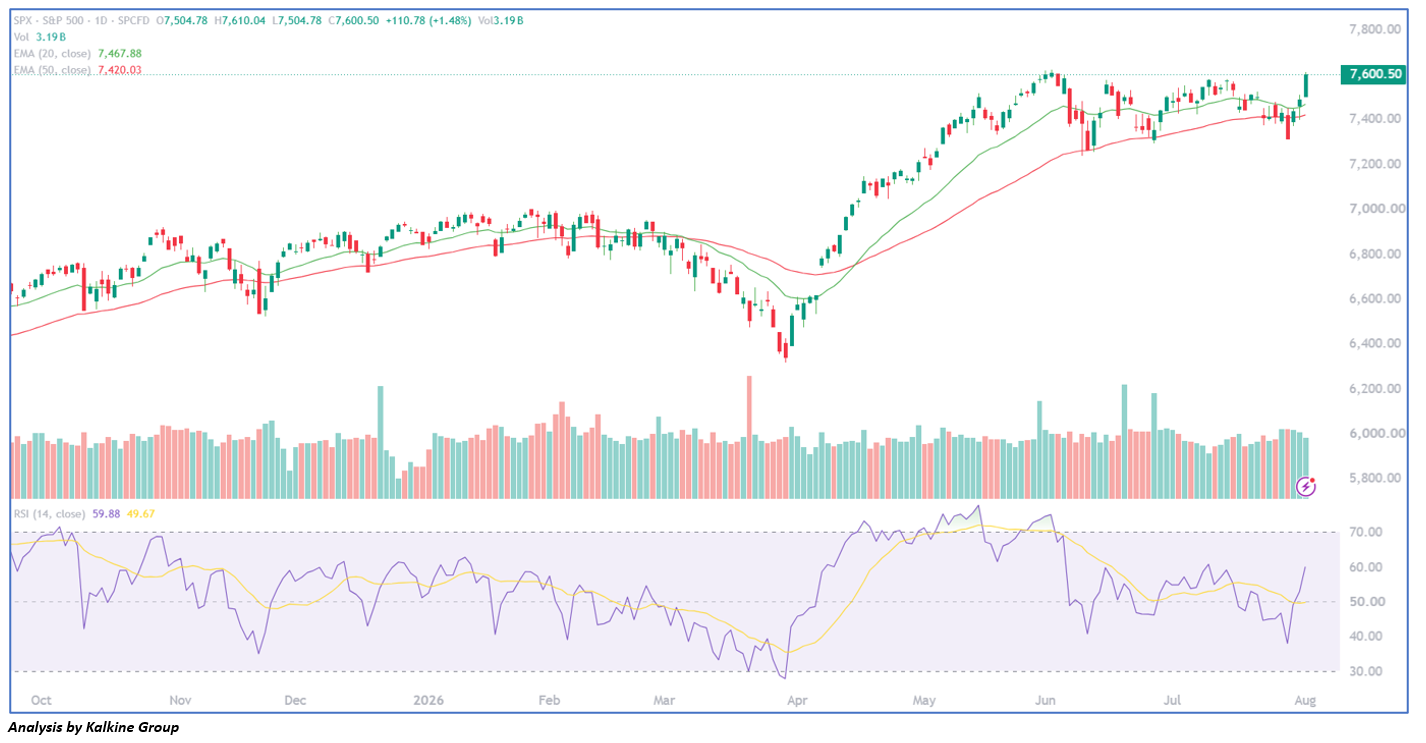
Stocks rallied strongly on Monday, building on the momentum from the previous two sessions. After opening sharply higher, buying interest remained firm throughout the day, pushing the major averages steadily upward and allowing them to finish near their session highs. From a technical standpoint, the S&P 500 reinforced its bullish short-term outlook, closing at 7,600.50, up 1.48%. The index decisively reclaimed both its 20-day EMA (7,467.88) and 50-day EMA (7,420.03), signaling renewed buying strength after a period of consolidation. The formation of a strong bullish candlestick, supported by healthy trading volume, suggests that buyers have regained control of the near-term trend. Meanwhile, the 14-day RSI has improved to around 60, reflecting strengthening momentum while remaining below overbought levels, leaving room for further gains. As long as the index holds above the 7,540–7,560 support zone, the bullish bias is expected to remain intact. On the upside, immediate resistance is seen in the 7,650–7,700 region, with a decisive breakout above this range potentially opening the door to fresh record highs. However, a sustained move back below the 20-day EMA would indicate fading momentum and could weaken the current bullish outlook.

 Nov 04, 2026




 Please wait processing your request...