
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stocks closed mixed on Wednesday ahead of Nvidia’s earnings, with the S&P 500 nearly flat, the Nasdaq slightly higher and the Dow down 113 points. Most technology stocks advanced, including Microsoft, Meta, Micron and AMD, while Nvidia declined 1.6% and Intuit fell 3.2% following a weaker-than-expected outlook. Strong consumer data and elevated PCE Inflation reinforced expectations that the Federal Reserve would maintain a restrictive policy stance, weighing on traditional sectors.
Market Movers
Among the top-performing stocks of the session Cre8 Enterprise Limited, Inc. surged 164.98%, while YY Group Holding Limited. rallied 84.35%. On the losing side, Greenland Mines Ltd. fell 48.09%, while Wetour Robotics Limited. declined 38.96%, making them the weakest performers during the trading day.
Commodities Update
Crude oil stabilized on Thursday after three consecutive sessions of losses, with WTI trading near USD 82 per barrel and Brent around USD 88. Prices were supported by Ukrainian attacks on Russian refineries and ports, which could restrict the country’s energy exports, while hopes of easing disruptions through the Strait of Hormuz limited gains. Iran and Oman reached a revenue-sharing agreement over the waterway, although Tehran cautioned that it would not guarantee an immediate reopening. Meanwhile, Saudi Arabia is reportedly increasing loadings from Persian Gulf terminals to reduce exposure to Houthi-related risks in the Red Sea.
Gold traded near USD 4,600 per ounce on Thursday, while silver climbed toward USD 69 and approached a two-month high, as investors assessed the Federal Reserve’s policy outlook ahead of its September meeting. Stronger-than-expected US PCE inflation reinforced expectations that interest rates could remain elevated, with attention turning to Fed Chair Kevin Warsh’s Jackson Hole speech. Both metals remained supported by Demand for protection against US Debt risks and a weaker dollar, while gold benefited from higher Chinese imports and silver gained additional support from strong industrial demand across solar energy, electric vehicles and AI data-centre infrastructure.
Macro Updates
Dollar Strengthens on Firm Inflation Data
The US dollar index traded above 99 on Thursday, supported by stronger-than-expected PCE inflation that increased expectations of a Federal Reserve rate hike before year-end. Investors awaited Fed Chair Kevin Warsh’s Jackson Hole speech while assessing easing oil prices, the Treasury’s expanded debt-buyback programme and broader US fiscal risks.
US Crude Inventories Edge Higher
US crude inventories rose by 0.095 million barrels to 428.9 million barrels in the week ended August 21, below expectations for a 0.6 million-barrel increase, while Cushing stocks climbed by 1.176 million barrels. Gasoline and distillate inventories fell more sharply than forecast, declining by 2.536 million and 2.228 million barrels, respectively. Meanwhile, refinery runs were broadly stable and net crude imports decreased by 161,000 barrels per day.
Bonds Commentary
The 10-year US Treasury Yield rose to around 4.66% on Thursday, extending gains for a second session after stronger-than-expected PCE inflation increased expectations of a Federal Reserve rate hike before year-end. Investors are awaiting Fed Chair Kevin Warsh’s Jackson Hole speech while assessing concerns that the Treasury’s planned expansion of bond Buybacks could undermine market credibility.
Futures Update
US stock futures advanced on Thursday after Nvidia’s strong Q2 results and bullish sales outlook reinforced confidence in sustained AI infrastructure demand. Nasdaq 100 futures rose 1%, while S&P 500 and Dow futures gained around 0.5% each. Nvidia climbed more than 4% in extended trading, while Salesforce surged nearly 13% and Okta jumped 20% following better-than-expected results. Investors now await Earnings from Workday, Autodesk, MongoDB, Dollar General and Best Buy.
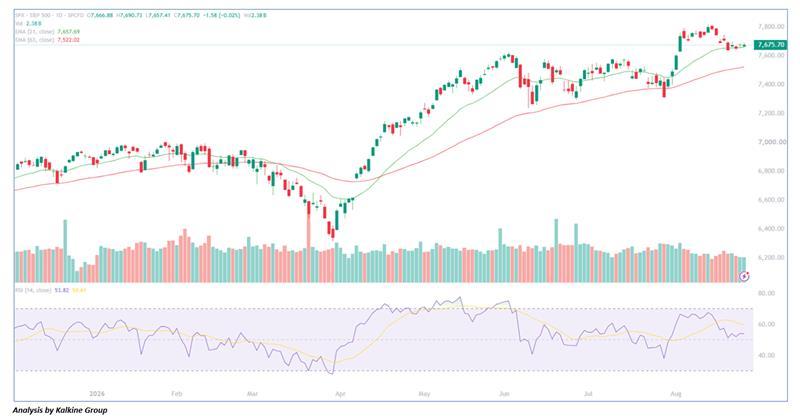
After ending the previous session mostly higher, U.S. stocks lacked a clear direction on Wednesday, with the major averages fluctuating around the unchanged line before finishing modestly lower. Against this backdrop, the S&P 500 maintains a cautiously bullish intraday setup, holding at 7,675.70 and just above its 21-day EMA at 7,657.69, while the 63-day EMA at 7,522.02 remains a key secondary support level. Sustaining the 7,655–7,660 zone could encourage a rebound toward 7,720, followed by a potential retest of the 7,780–7,800 record-high region. However, a decisive break below 7,655 could signal deeper weakness toward 7,600 and potentially the 7,520–7,530 area. With RSI(14) at 53.82 and easing toward neutral, the 7,655 support zone remains the key near-term pivot for determining the next directional move.


 Nov 02, 2026




 Please wait processing your request...