
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US equities closed higher on Thursday as softer-than-expected producer and consumer Inflation strengthened expectations that the Federal Reserve would keep interest rates unchanged next month. The S&P 500 gained 0.6% to a record high, the Nasdaq advanced 1.1% and the Dow added 70 points. Semiconductor stocks rallied on sustained AI-spending optimism, led by Sandisk, Micron and Marvell. However, Cisco declined 8.4% on a weaker AI data-centre sales outlook, while banking and industrial stocks also underperformed.
Market Movers
Among the top-performing stocks of the session FGI Industries Ltd. surged 147.78%, while Inno Holdings Inc. rallied 57.33%. On the losing side, National Cellebrite DI Ltd. fell 29.18%, while Securitize Corp. declined 27.48%, making them the weakest performers during the trading day.
Commodities Update
WTI crude traded above USD 81 per barrel and Brent hovered around USD 87 on Friday, with both benchmarks gaining nearly 5% for the week. Prices were supported by intensified US economic pressure on Iran, continued uncertainty over reopening the Strait of Hormuz, risky shipping conditions and the IEA’s warning of the widest global Supply Deficit in five years. Houthi attacks on Saudi Arabia’s Jazan refinery added to supply concerns, although additional Middle Eastern crude shipments to the US could provide some relief to low inventories.
Gold fell below USD 4,350 per ounce and silver slipped below USD 64 on Friday as investors secured gains while evaluating the Federal Reserve’s policy outlook and Middle East tensions. Softer-than-expected US core producer inflation, following subdued consumer-price data, reduced expectations of a near-term rate increase, with the probability of a 25-basis-point September hike declining to around 35% from 55% a week earlier. However, stalled negotiations over reopening the Strait of Hormuz sustained concerns that further escalation could raise energy prices and revive inflationary pressures.
Macro Updates
Softer Inflation Weighs on the US Dollar
The US Dollar index declined to around 99.8 on Friday, extending losses for a second session as subdued CPI and producer-price data reduced expectations of a September Federal Reserve rate increase. Markets lowered the probability of a 25-basis-point hike to approximately 35% from 55% a week earlier. However, uncertainty surrounding the Middle East conflict and the reopening of the Strait of Hormuz remains a risk to energy prices and the inflation outlook.
US Credit Ratings Remain Stable Despite Fiscal Pressures
Fitch affirmed the US sovereign rating at AA+ with a stable outlook, supported by the country’s large, resilient economy, high per-capita income and the dollar’s global reserve-currency status. However, growth is projected to slow to 1.9% during 2026–2027, while inflation is expected to remain elevated at 3.4%. The fiscal deficit is forecast to widen to 7.4% of GDP amid rising military, interest and entitlement costs. Moody’s maintains an Aa1 stable rating, while DBRS rates the US AAA with a stable outlook.
Bonds Commentary
The 10-year US Treasury Yield held near 4.65% on Friday as subdued CPI data and flat July producer prices eased inflation concerns and reduced expectations of a September Federal Reserve rate increase. Markets lowered the probability of a 25-basis-point hike to around 35% from 55% a week earlier. However, uncertainty surrounding the Middle East conflict and the reopening of the Strait of Hormuz remains a key risk to energy prices and the inflation outlook.
Futures Update
US Equity futures were largely unchanged on Friday as optimism over strong technology Earnings and increased AI infrastructure spending was offset by macroeconomic and inflation concerns. The S&P 500 remained near its record high, while Nasdaq 100 and Dow futures traded flat. Semiconductor stocks extended gains, led by Sandisk, Micron and Seagate, amid expectations of higher hyperscaler investment. However, Iran-related oil-supply risks and concerns about potential Federal Reserve rate increases continued to weigh on industrial and banking stocks.
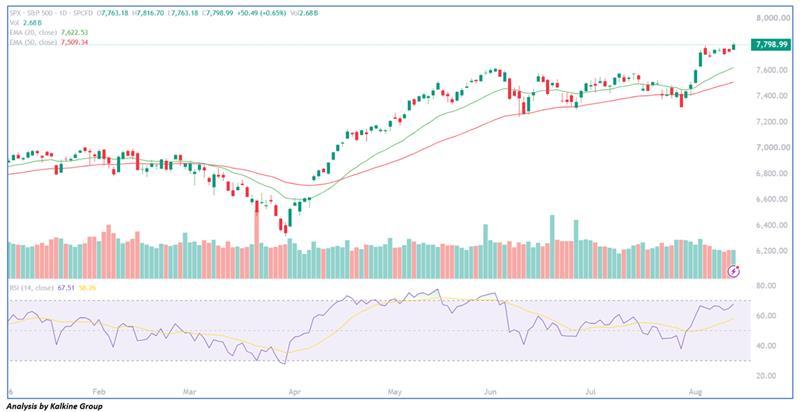
Stocks moved broadly higher during Thursday’s session, extending the moderate gains recorded in the previous sessions. All three major averages finished in positive territory, with the S&P 500 climbing to another record closing high. The S&P 500 continues to exhibit a strong bullish intraday bias, trading near record levels at 7,798.99 and comfortably above its 20-day EMA at 7,622.53 and 50-day EMA at 7,509.34. The index maintains a well-defined higher-high and higher-low pattern, while the RSI at 67.51 reflects firm buying momentum without entering deeply overbought territory. The recent breakout above 7,700 has reinforced the bullish structure, with 7,800 emerging as the immediate psychological resistance level. A decisive break above this mark could drive the index toward 7,850–7,900, while support is positioned around 7,760–7,700. The broader uptrend remains intact as long as the S&P 500 holds above its 20-day EMA.

 Nov 17, 2026
 Please wait processing your request...