
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US stock indices closed mostly lower on Monday as rising oil prices and Treasury yields heightened Inflation concerns and rate-hike expectations. The S&P 500 fell 0.3%, the Nasdaq slipped 0.1% and the Dow lost 374 points, with major technology and financial stocks declining. Nvidia gained 1.4% following its USD 3.5 billion Investment in MediaTek. Despite Monday’s weakness, all three major indices advanced in August.
Market Movers
Among the top-performing stocks of the session Antelope Enterprise Holdings Limited surged 83.33%, while Nocera, Inc. rallied 49.74%. On the losing side, CID HoldCo, Inc. fell 25.00%, while Z Squared Inc. declined 23.58%, making them the weakest performers during the trading day.
Commodities Update
Crude oil prices advanced on Tuesday, with WTI trading around USD 88 per barrel and Brent above USD 92, extending gains of 2.8% and 2.7%, respectively, from Monday. Prices rose as renewed US-Iran hostilities and attacks on tankers heightened concerns over prolonged Supply disruptions through the Strait of Hormuz. Although major regional producers continue to export crude through the waterway, the threat of further attacks remains a significant risk to energy shipments.
Gold fell more than 1% to around USD 4,375 per ounce, while silver declined over 2% to below USD 65, with both reaching their lowest levels since August 19. The metals were pressured by US Treasury yields rising to their highest since January 2025 amid inflation concerns and growing expectations of a near-term Federal Reserve rate hike. Investors now await the ADP employment report and nonfarm payrolls for further signals on the Fed’s policy path.
Macro Updates
US Logistics Growth Slows as Cost Pressures Intensify
The US Logistics Managers’ index declined to 66.6 in August 2026 from 68.9 in July, marking its slowest expansion in six months as inventory growth moderated. However, cost pressures intensified, with inventory costs rising to 78.6, Warehousing prices remaining elevated at 75 and transportation prices surging to 90. Despite improving warehousing capacity, constrained transportation capacity and persistently rising costs continued to challenge the logistics sector.
US Dollar Strengthens on Rate-Hike Expectations
The US Dollar Index climbed above 99.5 on Tuesday as hawkish comments from Federal Reserve Chair Kevin Warsh and rising oil prices reinforced inflation concerns. Markets now assign more than a 65% probability of a September rate hike, compared with around 36% before Warsh’s remarks. Investors are also awaiting US business-activity data and Friday’s August employment report for further indications of the Fed’s policy direction.
Bonds Commentary
The US 10-year Treasury Yield rose for a fifth consecutive session to 4.79%, its highest since January 2025, as rising oil prices fueled inflation concerns and expectations of tighter Federal Reserve policy. Markets now assign a 68% probability of a 25-basis-point rate hike this month, up from 40% last week. Meanwhile, the 30-year yield climbed to 5.28%, approaching levels seen before the Treasury expanded its bond-buyback programme.
Futures Update
US stock futures declined on Tuesday, with S&P 500 and Dow contracts down 0.5% and Nasdaq 100 futures falling more than 1%, as tight financial conditions and rising yields fueled growth concerns. Renewed US-Iran hostilities heightened inflation risks and expectations of further central-bank rate hikes, while increased AI-related corporate Debt issuance added pressure on Credit markets. Technology stocks led the losses, including Marvell, Intel, Sandisk, Amazon, Tesla and Nvidia.
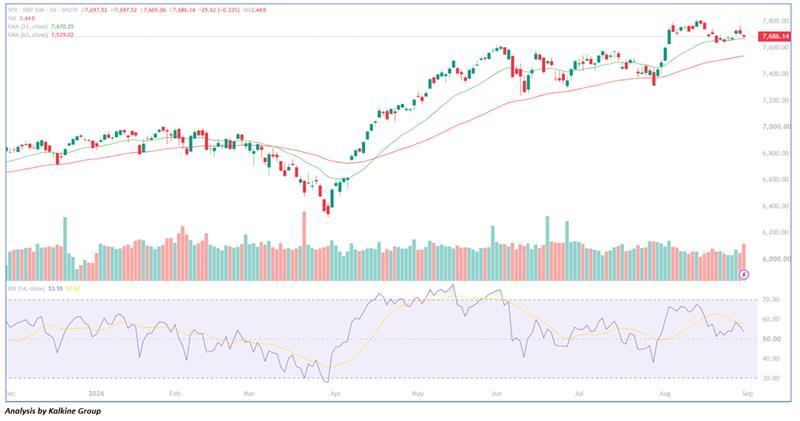
Stocks moved mostly lower on Monday, extending the pullback from Friday as renewed concerns over a potential escalation of the Middle East conflict weighed on investor sentiment. Although the major averages recovered some ground late in the session, they remained firmly in negative territory at the close. The S&P 500 is trading near 7,686, consolidating in a tight intraday range around its 21-day EMA at 7,670 after retreating from recent highs near 7,800. The near-term bias remains neutral to cautiously bullish as long as the index holds the 7,665–7,670 dynamic support zone. A sustained move above 7,720 would strengthen the bullish setup and could pave the way for a retest of 7,780–7,800, while a decisive break below 7,665 would increase downside risk toward 7,580–7,600, followed by the 63-day EMA near 7,539.

 Nov 03, 2026





 Please wait processing your request...