
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US equities rallied sharply on Tuesday as strong corporate earnings and lower oil prices lifted sentiment, with the S&P 500 rising 1.8% and the Dow gaining 907 points to record highs, while the Nasdaq 100 advanced 3.3%. Palantir surged 29% following strong quarterly results, semiconductor stocks posted broad gains and Caterpillar climbed 5.5% after exceeding earnings expectations and raising its revenue outlook. Meanwhile, SpaceX declined in after-hours trading as elevated capital expenditure overshadowed better-than-expected revenue.
Market Movers
Among the top-performing stocks of the session Autonomix Medical, Inc. surged 434.25%, while Ibotta, Inc. rallied 51.91%. On the losing side, AdaptHealth Corp. fell 38.04%, while Better Home & Finance Holding Company. declined 36.74%, making them the weakest performers during the trading day.
Commodities Update
WTI crude rose to around USD 76 per barrel and Brent approached USD 80 on Wednesday, ending a two-day decline after Yemen’s Houthis claimed an attack on a Saudi vessel in the Red Sea. However, prices remained below recent highs amid growing optimism that the US, Iran and Oman could soon finalise a 60-day interim agreement to reopen the Strait of Hormuz without tolls. Diplomatic efforts also included a Qatari proposal, possible European assistance in clearing mines and Saudi-Houthi talks aimed at preventing further escalation.
Gold approached USD 4,200 per ounce and silver surpassed USD 61 on Wednesday, extending gains for a third consecutive session as progress toward reopening the Strait of Hormuz eased inflation concerns and reduced expectations for a September Federal Reserve rate hike to 57% from 67%. Investors now await US labour-market data for further policy signals, while continued inflows into Chinese gold-backed ETFs provided additional support to bullion prices.
Macro Updates
Higher Mortgage Rates Weigh on US Loan Demand
US mortgage applications declined 2.9% in the final week of July, extending the previous week’s 6.4% fall, as the average 30-year fixed mortgage rate rose five basis points to a one-year high of 6.81%. Higher Treasury yields and renewed inflation concerns pressured borrowing activity, with home-purchase applications falling approximately 4% and refinancing demand declining about 2% to its lowest level since May 2025.
Easing Rate-Hike Expectations Pressure the Dollar
The US Dollar Index remained below 100 on Wednesday as progress toward reopening the Strait of Hormuz lowered oil prices and inflation concerns, reducing expectations for a September Federal Reserve rate hike to 57% from 67%. Investors awaited US labour-market data for further policy signals, while the dollar remained weak against the yen amid indications that the US and Japan were prepared to intervene again if necessary.
US Crude Inventories Rise Against Expectations
US crude oil inventories increased by 2.69 million barrels in the week ended July 31, contrary to expectations for a 2 million-barrel draw, while Cushing stocks rose by 2.36 million barrels. Crude production remained broadly stable at 13.80 million barrels per day, gasoline inventories edged higher and distillate stocks declined by 1.2 million barrels. Meanwhile, the Strategic Petroleum Reserve fell by another 2.9 million barrels to 304.8 million barrels.
Bonds Commentary
The US 10-year Treasury yield fell to around 4.6% on Wednesday, extending its decline for a third session as progress toward reopening the Strait of Hormuz lowered oil prices, inflation concerns and expectations for aggressive monetary tightening. The probability of a September Federal Reserve rate hike declined to approximately 57% from 67%, while investors awaited upcoming US labour-market data for further policy signals.
Futures Update
US stock futures edged higher on Wednesday after the Dow and S&P 500 reached record highs and the Nasdaq Composite surged 2.59%, supported by strong earnings and optimism over a potential reopening of the Strait of Hormuz. However, SpaceX and AMD declined sharply in extended trading amid concerns about elevated AI spending and a modest earnings beat, respectively, while investors awaited results from Eli Lilly, AppLovin, Walt Disney, Uber and Sandisk.
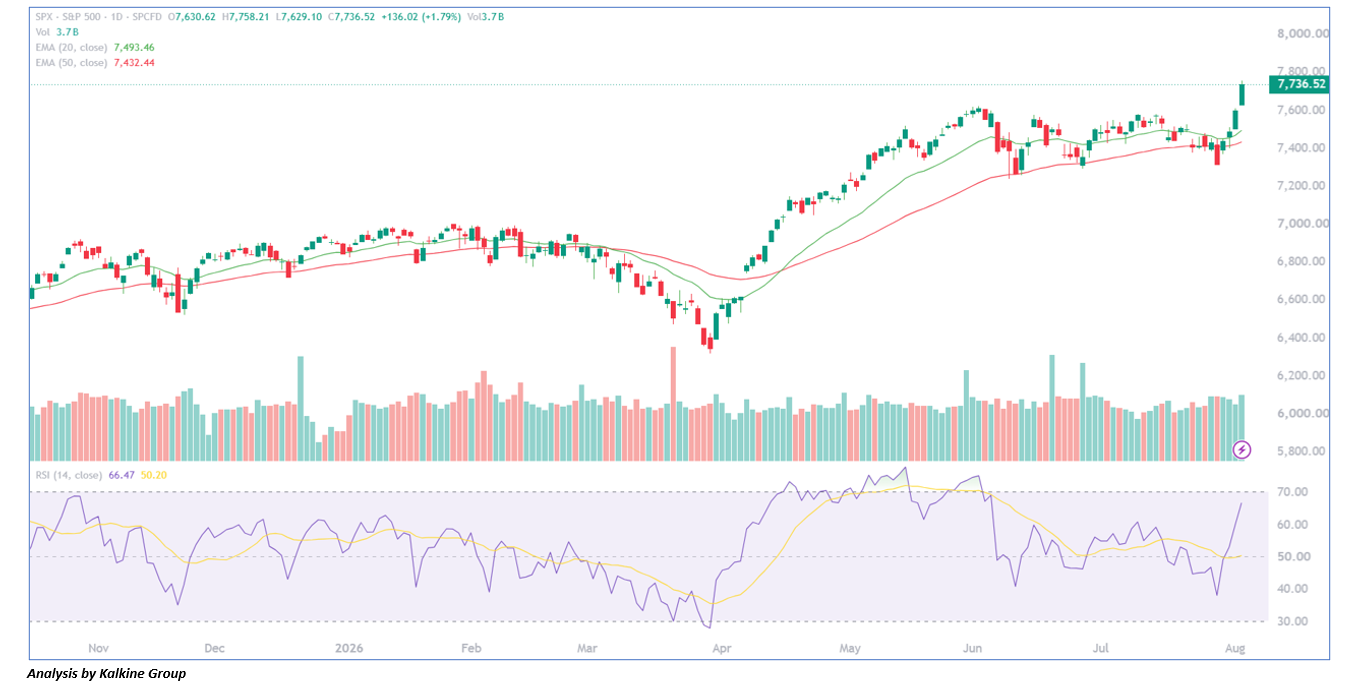
The major U.S. indices rallied sharply on Tuesday, building on the strong gains recorded in recent sessions. The Dow Jones Industrial Average, Nasdaq Composite, and S&P 500 all advanced to fresh record closing highs, underscoring broad-based bullish sentiment across the market. From a technical standpoint, the S&P 500 has reinforced its bullish outlook by breaking decisively above its recent consolidation range and continuing to trade well above both the 20-day and 50-day EMAs, signaling a sustained upward trend. The rally has been accompanied by improving trading volumes, while the 14-day RSI has risen to around 66, reflecting strengthening momentum without indicating extreme overbought conditions. As long as the index remains above the 7,680–7,700 support zone, the near-term bias is expected to stay positive, with the next upside targets seen around 7,780–7,850. However, a failure to hold above the recent breakout level could trigger short-term profit booking, potentially leading to a pullback toward the 20-day EMA before the broader uptrend resumes.

 Nov 03, 2026





 Please wait processing your request...