
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update
US equities closed lower on Monday, with the S&P 500 falling 0.5%, the Nasdaq 100 declining 0.8% and the Dow losing 152 points as AI-related safety concerns triggered a broad selloff in chipmakers and infrastructure stocks. Sentiment was further pressured by the 10-year Treasury Yield briefly exceeding 5% and surging crude prices, which strengthened expectations of a 25-basis-point Fed rate hike.
Market Movers
Among the top-performing stocks of the session Future Fintech Group Inc. surged 179.17%, while Basel Medical Group Ltd. rallied 55.90%. On the losing side, Horizon Quantum Holdings Ltd. fell 32.06%, while TEN Holdings, Inc. declined 28.81%, making them the weakest performers during the trading day.
Commodities Update
WTI crude rose to around USD 103.5 per barrel and Brent reached USD 107.5 on Tuesday, marking four-month highs amid continued Middle Eastern Supply disruptions. Saudi Arabia’s East-West pipeline remains offline following recent attacks, limiting an alternative route around the Strait of Hormuz, while uncertainty over US–Iran negotiations and a potential halt to attacks on energy infrastructure in Ukraine further supported prices.
Gold hovered around USD 4,300 per ounce and silver near USD 63, both close to five-week lows, as rising oil prices and a nearly 92% probability of a 25-basis-point Federal Reserve rate hike lifted Treasury yields and pressured non-yielding metals. Copper remained near a seven-week low of USD 6.3 per pound amid increased London Warehouse inflows, easing supply concerns, delayed US Tariff action and continued weakness in parts of China’s economy.
Macro Updates
Dollar Strengthens Ahead of Expected Fed Rate Hike
The dollar index climbed above 99.5 for a fifth consecutive session as markets priced in a 92% probability of a 25-basis-point Federal Reserve rate hike. Higher oil-driven inflation, uncertainty over future Monetary Policy and weaker Equity sentiment amid AI-related concerns further supported Demand for the dollar.
Bonds Commentary
The US 10-year Treasury yield climbed above 5%, its highest since July 2007, as surging energy prices, Inflation and fiscal concerns intensified the Global Bond selloff. Expectations of a 25-basis-point Fed rate hike and heavy Debt issuance by AI companies added further upward pressure on yields.
Futures Update
US equity futures slipped up to 0.3% as rising bond yields, Middle East-driven energy supply risks and expectations of a 25-basis-point Fed rate hike pressured sentiment. Debt-heavy AI companies declined on higher borrowing-cost concerns, while semiconductor stocks rebounded from the previous session’s losses.
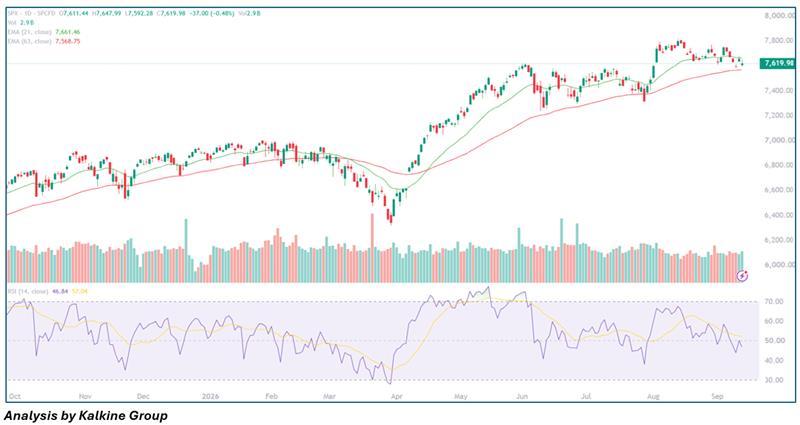
Following Monday's initial steep drop and subsequent intraday rebound, the S&P 500 Index (SPX) closed down -0.48% (-37.00 points) at 7,619.98 after fluctuating between a low of 7,592.28 and a high of 7,647.99, slipping marginally beneath dynamic support at its rising 21-day EMA (7,661.46) as upside momentum stalls beneath recent record peaks near 7,800.00. With the 14-day RSI easing to a neutral 46.84 below its 52.04 signal line and Volume printing at 2.9B, sustained trading below the 21-day EMA threatens an extended corrective pullback toward primary trend support at the ascending 63-day EMA (7,568.75), requiring bulls to decisively reclaim the 7,650.00–7,665.00 threshold to revive bullish continuation toward the 7,750.00–7,800.00 overhead resistance zone.

 Nov 03, 2026





 Please wait processing your request...