
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
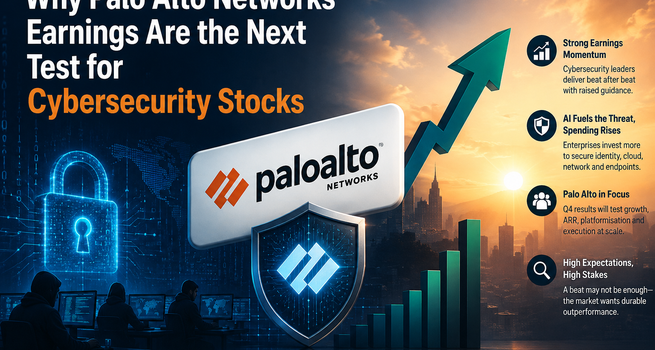
- Palo Alto Networks (NASDAQ:PANW) reports fiscal fourth-quarter results after the close on September 1, with the stock technically still in bullish territory.
- The Street expects Revenue of roughly $3.35 billion and non-GAAP EPS of $0.98, with Next-Generation Security ARR approaching $9 billion.
- Last quarter is the cautionary precedent: Palo Alto beat on revenue and EPS, with ARR up 60% year-over-year, yet the stock still fell 5-6% the next day on high expectations.
- A beat alone may not move the stock this time either; the reaction is more likely to hinge on ARR, remaining performance obligations, platformization progress, and fiscal 2027 commentary.
- Options markets are pricing an approximately 11% swing in either direction, underscoring how much is already priced in before results land.
A Chart That Still Says Buy
Palo Alto Networks (NASDAQ:PANW) heads into fiscal fourth-quarter earnings, due after the close on September 1st, with its technical picture intact. The stock remains in bullish territory on the charts, part of a broader run that has taken shares up more than 100% this year alongside a Cybersecurity sector that has outperformed the wider market by a wide margin. But a healthy chart is not the same thing as a low bar. This is a high-expectations setup, and tomorrow's reaction is likely to depend less on whether Palo Alto simply beats estimates than on the quality of the guidance and the annual Recurring Revenue numbers behind it.
The Precedent: A Beat That Wasn't Enough
Palo Alto's most recent quarter is the clearest evidence of that dynamic. Fiscal third-quarter results, released in June, showed revenue of $3.00 billion, up 31% year-over-year, and adjusted Earnings of $0.85 a share, both ahead of consensus. Next-Generation Security annual recurring revenue reached $8.13 billion, up 60% year-over-year—by most measures, an excellent quarter. The stock still fell 5-6% the following day. Expectations were already so high that a clean beat on every headline number was treated as confirmation of what the market had assumed, not as new information worth paying up for.
What the Street Wants This Time
For fiscal fourth quarter, the Street is looking for revenue of roughly $3.35 billion, up 32% year-over-year, and non-GAAP Earnings Per Share of $0.98, with Next-Generation Security ARR approaching $9 billion—company guidance points to $8.90-8.95 billion, up 59-60%. Remaining performance obligations are guided to $20.9-21.0 billion. Those numbers already assume a strong quarter. A beat alone, in other words, may not be enough.
What could extend the bullish setup is a result that clears those figures by a meaningful margin: ARR and RPO coming in well above guidance, further evidence of platformization—larger customers consolidating spend onto Palo Alto's full stack rather than buying point products elsewhere—and commentary on fiscal 2027 that suggests the current growth rate is durable rather than borrowed from future quarters. Progress integrating the CyberArk and Chronosphere acquisitions, and any update on the China regulatory review, will also feed into how the guidance is read.
The other outcome is the one investors saw in June: results that are merely good rather than exceptional, met by profit-taking in a stock that has already run hard. Options markets are pricing an approximately 11% move in either direction, a figure that itself reflects how binary the setup has become. Palo Alto has a long history of beating consensus, often by mid-single digits on earnings per share—which is exactly why a repeat performance is already assumed, and why the stock's reaction has increasingly become a referendum on guidance rather than on the quarter just reported.
Watch the Price Action, Not Just the Headlines
The practical takeaway is to watch how the stock trades in the hours and days after the report rather than fixating on whether the headline revenue and earnings numbers clear consensus. If ARR, RPO and platformization metrics come in meaningfully above expectations, and management's fiscal 2027 framing is confident, the technical uptrend has room to extend. If the quarter lands in line—good, but not exceptional—the more likely outcome is a repeat of June: a fundamentally solid print met by a sell-the-news reaction, as a market already positioned for outperformance takes profits rather than adds to them.
Palo Alto's setup, in short, is bullish on the chart and unforgiving on the numbers. The stock does not need a disaster to fall; it simply needs a quarter that fails to exceed an already elevated bar.
When does Palo Alto Networks report fiscal fourth-quarter earnings?
Palo Alto Networks (NASDAQ:PANW) is scheduled to report results, covering the fiscal fourth quarter ended July 31, after the market close on September 1.
Why did Palo Alto's stock fall after its last earnings beat?
Despite beating on revenue and EPS in fiscal third-quarter results, with Next-Generation Security ARR up 60% year-over-year, the stock fell 5-6% the next day because expectations going into the print were already very high.
What metrics matter most for Palo Alto's upcoming report?
Investors are focused on Next-Generation Security ARR (guided near $9 billion), remaining performance obligations, platformization progress, and management commentary on fiscal 2027, rather than the headline revenue and EPS beat alone.

 Nov 17, 2026
 Please wait processing your request...