
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
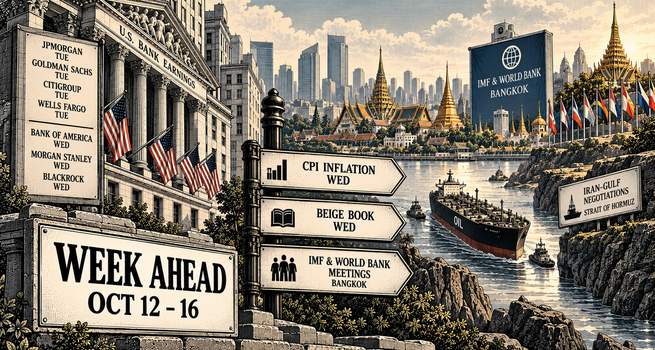
The third-quarter US Earnings season begins in earnest this week, with the largest lenders, Citigroup, Goldman Sachs, JPMorgan Chase, Wells Fargo, Bank of America and Morgan Stanley, reporting in close succession alongside corporate heavyweights Johnson & Johnson, UnitedHealth Group and BlackRock. September consumer price data on Wednesday will be the week's single most closely watched release, offering one of the last major Inflation readings before the Federal Reserve's next policy decision later this month. Headline CPI is expected to rise 3.6% on an annual basis, with the core measure estimated at 2.5%, against a Fed target of 2%. The IMF and World Bank hold their annual meetings in Bangkok this week against a backdrop of elevated energy costs, record public Debt and jittery bond markets, with a flurry of Central Bank speeches, including from Fed Chair Kevin Warsh, adding a global dimension to a week already dense with domestic catalysts. Progress or escalation in Iran-Gulf negotiations remains the backdrop variable most capable of moving energy prices, and with them, the inflation data markets are about to receive.
Major Ex-Dividend Dates This Week
|
Day |
Company |
Ticker |
Dividend |
Yield |
|---|---|---|---|---|
|
Tuesday, Oct 13 |
Accenture |
$1.71 |
3.28% |
|
|
Tuesday, Oct 13 |
General Mills |
$0.61 |
7.49% |
|
|
Wednesday, Oct 14 |
Micron Technology |
$0.15 |
0.06% |
|
|
Wednesday, Oct 14 |
PNC Financial Services |
$2.00 |
3.64% |
|
|
Thursday, Oct 15 |
AbbVie |
$1.73 |
2.54% |
|
|
Thursday, Oct 15 |
Delta Air Lines |
$0.22 |
1.05% |
|
|
Thursday, Oct 15 |
Freeport-McMoRan |
$0.15 |
0.84% |
|
|
Friday, Oct 16 |
TD Synnex |
$0.48 |
0.72% |
|
|
Friday, Oct 16 |
Cracker Barrel |
$0.25 |
1.81% |
|
|
Friday, Oct 16 |
EOG Resources |
$1.02 |
2.75% |
Monday, October 12
Market
No economic data or earnings are scheduled. Columbus Day holds limited impact on Equity trading, though bond markets observe a modified schedule. Attention is already turning to Tuesday's bank earnings and the IMF and World Bank meetings opening in Bangkok.
Tuesday, October 13
Earnings
JPMorgan Chase (NYSE:JPM), Goldman Sachs (NYSE:GS), Citigroup (NYSE:C) and Wells Fargo (NYSE:WFC) all report before the open, kicking off what is expected to be an exceptionally strong quarter for US corporate profits, with S&P 500 earnings forecast to have jumped more than 30% in the third quarter following a robust first half. Bank stocks have been among the worst-performing groups recently, with the S&P 500 banks index down roughly 9% over the past month amid rising Treasury yields, making this week's results as much a test of whether that weakness reflects genuine deterioration beneath the surface as a read on the quarter itself. Investors will focus closely on how higher rates and elevated energy costs are rippling through to consumer spending and activity in capital markets. Johnson & Johnson (NYSE:JNJ) and UnitedHealth Group (NYSE:UNH) also report before the open, adding healthcare into the mix on the same day as the money-centre banks. Domino's Pizza (NASDAQ:DPZ) and Albertsons (NYSE:ACI) round out the day with consumer-facing reads.
Economic Data
The NFIB Index of Small Business Optimism for September, prior at 98.7, opens the week's data calendar at 6:00 am ET. Existing home sales for September, prior at 4.0 million and forecast to edge down to 3.97 million, land at 10:00 am ET. The monthly Treasury balance for September, prior at -$167 billion, closes Tuesday's releases.
Wednesday, October 14
Earnings
Bank of America (NYSE:BAC), Morgan Stanley (NYSE:MS) and BlackRock (NYSE:BLK) report before the open, completing the sweep of the six largest US lenders alongside Tuesday's four. State Street (NYSE:STT) also reports, extending the financial services read. Fastenal (NASDAQ:FAST) rounds out the morning with an industrial distribution signal tied to broader Manufacturing activity.
Economic Data
September CPI is the week's defining release, landing at 8:30 am ET. Headline CPI is forecast at 0.6% month-on-month and 3.6% year-on-year, up from 3.4% in August, largely reflecting higher fuel costs. Core CPI, which excludes food and energy, is forecast at 0.2% month-on-month and 2.5% year-on-year, up from 2.4%. Sticky services inflation within the core measure remains the component investors most want to see cool before growing confident the Fed can avoid a more aggressive path than currently priced. The Federal Reserve's Beige Book is released at 2:00 pm ET, providing a qualitative district-by-district read on economic conditions ahead of the Fed's late-October meeting.
Thursday, October 15
Earnings
Thursday is the week's heaviest earnings day. Bank of New York Mellon (NYSE:BNY), PNC Financial Services (NYSE:PNC), U.S. Bancorp (NYSE:USB) and Charles Schwab (NASDAQ:SCHW) report before the open, extending the regional and super-regional bank read beyond Tuesday's money-centre names. Marsh McLennan (NYSE:MMC) and Travelers Companies also add an insurance dimension. Prologis (NYSE:PLD) reports mid-morning, offering a logistics real estate read tied to global trade volumes.
Economic Data
Retail sales for September, prior at 1.2%, are forecast to ease to 0.3% at 8:30 am ET, a deceleration that will be read against Wednesday's CPI print for signs of whether consumer spending is cooling in step with or faster than inflation. The Empire State Manufacturing Survey for October, prior at 7.6, and the Philadelphia Fed Business Outlook Survey for October, prior at 23.2 and forecast at 25, provide two regional cross-checks on factory activity. September PPI is forecast at 0.6% month-on-month, accelerating slightly from August, with core PPI at 0.3%, feeding directly into expectations for how durable the CPI trend proves to be. Weekly jobless claims for the week ending October 10, prior at 197,000 and forecast at 202,000, round out the morning. Manufacturing and trade inventories for August, prior at 0.8%, close the day's releases.
Federal Reserve
Fed Chair Kevin Warsh delivers remarks in Thailand, timed to the IMF and World Bank annual meetings in Bangkok. Cleveland Fed President Beth Hammack speaks earlier at a Women's Trading Network Fireside Discussion. Both appearances will be parsed for any signal on how officials are weighing this week's CPI and PPI data ahead of the late-October meeting.
Friday, October 16
Earnings
M&T Bank (NYSE:MTB), Regions Financial (NYSE:RF), Citizens Financial Group (NYSE:CFG), Travelers Companies (NYSE:TRV) and Truist Financial (NYSE:TFC) report before the open, closing out the week's dense run of regional bank results.
Economic Data
Import prices for September, prior at 0.7%, are due alongside industrial production for September, prior at 0% and forecast to rebound to 0.4%, with capacity utilisation, prior at 76.3%, forecast at 76.6%, providing context on whether the rebound reflects genuine Demand strength.
Geopolitical Backdrop
Signs of progress in negotiations, or conversely, the risk of escalatory strikes involving Iran, the US and Gulf nations, remain the dominant variable shaping energy prices and, through them, the inflation data markets are digesting this week. High energy inflation has kept Global Bond yields near multi-decade highs, with the benchmark 10-year Treasury Yield last around 5.23%, after recently reaching its highest level in 24 years. A 5% yield on the 10-year had previously been treated as a key threshold likely to pressure equities, yet stocks have so far absorbed yields well above that level without a significant correction, a resilience some investors believe cannot persist indefinitely if yields continue climbing.
The IMF and World Bank annual meetings in Bangkok add a second structural theme to the week: record public debt levels across major economies, elevated energy costs and jittery bond markets form the backdrop against which the IMF updates its World Economic Outlook. Persistent protectionist measures affecting China's trade relationships, alongside fresh Chinese trade balance and Credit aggregate data, round out a week in which global policy coordination, or the lack of it, will be as closely watched as any single domestic data point.
The Week in Context
Two threads will determine how the week is ultimately read. First, whether the banks, having underperformed the broader market by a wide Margin over the past month, can deliver results strong enough to suggest the recent weakness in financial shares was sentiment-driven rather than a genuine signal of stress beneath the surface of the economy. A clean set of results across JPMorgan, Goldman Sachs, Citigroup, Wells Fargo, Morgan Stanley and Bank of America would likely be met with some relief. Second, whether Wednesday's CPI print confirms that inflation is merely elevated rather than reaccelerating in a way that would force the Fed's hand beyond what markets currently expect. A hotter-than-forecast core reading, particularly in services, would revive hiking bets that have recently been pared back, while a print in line with or below consensus would support the case for a more patient central bank. With earnings season now fully underway and Treasury yields already testing levels last seen a generation ago, the combination of bank results and the CPI data gives this week outsized influence over how the final quarter of 2026 is priced.

 Oct 28, 2026
 Please wait processing your request...