
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Momentum Shifts
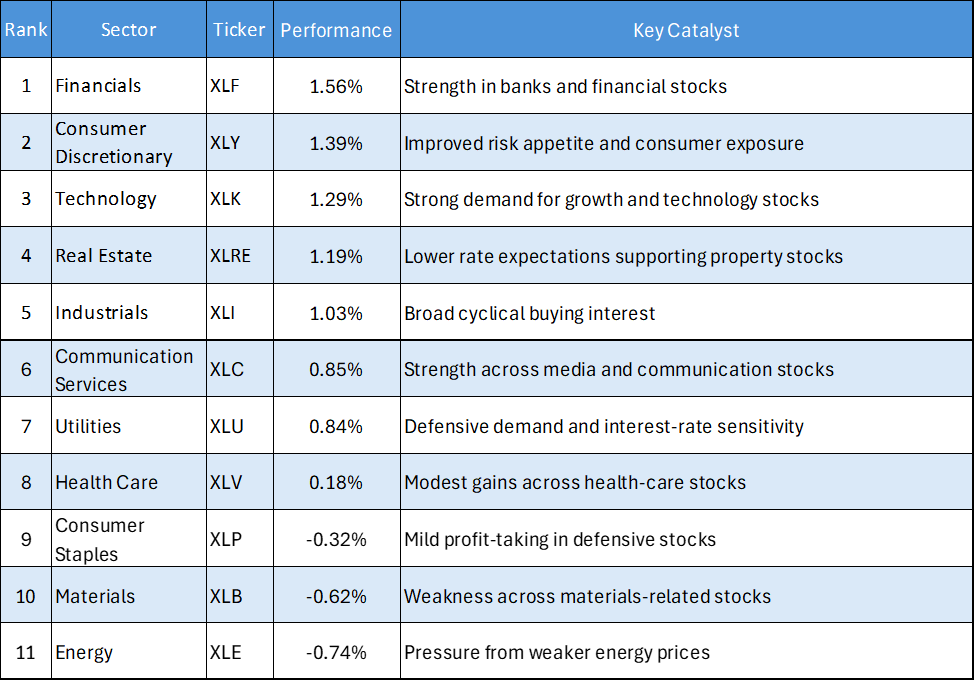
- Financials Lead Daily Performance: XLF gained 1.56%, recording the strongest advance among the 11 sectors.
- Consumer Discretionary Strengthens: XLY rose 1.39%, ranking second among the sectors.
- Technology Rebounds: XLK gained 1.29%, showing strong short-term price performance.
- Real Estate and Industrials Advance: XLRE and XLI increased 1.19% and 1.03%, respectively.
- Communication Services and Utilities Gain: XLC rose 0.85%, while XLU advanced 0.84%.
- Health Care Edges Higher: XLV gained 0.18%.
- Consumer Staples, Materials and Energy Decline: XLP, XLB and XLE fell 0.32%, 0.62% and 0.74%, respectively.
- Broad Participation Remains Positive: Eight of the 11 sectors advanced during the session.
The latest US sector performance data for 3 September 2026 shows a broadly positive session, with eight of 11 sectors recording gains. Financials delivered the strongest advance, followed by Consumer Discretionary, Technology and Real Estate. In contrast, Energy, Materials and Consumer Staples remained under pressure.
The latest session represents a notable improvement in short-term performance across several cyclical and growth-oriented sectors, although the divergence between strong financial and technology gains and weakness in Energy and Materials remains important.
Performance Breakdown by Sector
Momentum Breakdown
Financials, Consumer Discretionary and Technology Lead Daily Gains
Financials (XLF), Consumer Discretionary (XLY) and Technology (XLK) were the strongest performers on 3 September.
XLF gained 1.56%, recording the largest advance among the 11 sectors. Consumer Discretionary followed with a 1.39% gain, while Technology increased 1.29%.
The strength across these three sectors indicates strong short-term buying interest, particularly in Financials and Technology. The simultaneous advance in cyclical and growth-sensitive sectors also points to broader participation in the market recovery.
Real Estate and Industrials Show Solid Strength
Real Estate (XLRE) gained 1.19%, making it the fourth-strongest sector of the session. Industrials (XLI) also advanced 1.03%.
Both sectors recorded gains above 1%, placing them among the strongest performers. Continued relative improvement in these areas would be important for determining whether the current market recovery can broaden further.
Communication Services and Utilities Advance
Communication Services (XLC) gained 0.85%, while Utilities (XLU) rose 0.84%.
The relatively similar performance of these two sectors suggests that the session's strength was not limited to higher-beta areas. Utilities' advance is particularly notable because the sector can behave more defensively than cyclical sectors, providing another indication of broad market participation.
Health Care Posts a Modest Gain
Health Care (XLV) increased only 0.18%, making it one of the weaker advancing sectors.
Although the sector remained positive, its relatively small gain compared with Financials, Consumer Discretionary, Technology and Real Estate indicates more limited short-term buying momentum.
Energy, Materials and Consumer Staples Lag
The weakest performance came from Energy (XLE), Materials (XLB) and Consumer Staples (XLP).
Energy declined 0.74%, followed by Materials at -0.62% and Consumer Staples at -0.32%. The weakness in Energy and Materials contrasts sharply with the strength across Financials, Technology and other cyclical sectors.
A sustained recovery in these lagging areas would be necessary to provide stronger confirmation of a broad-based sector rotation.
Strategic Summary
The US sector performance picture on 3 September 2026 was broadly constructive, with eight of 11 sectors advancing. Financials was the standout performer, gaining 1.56%, followed by Consumer Discretionary at 1.39% and Technology at 1.29%.
Real Estate and Industrials also recorded gains above 1%, while Communication Services and Utilities posted solid advances. This broad participation suggests that buying interest extended across several different areas of the market.
However, Energy and Materials remained weak, falling 0.74% and 0.62%, respectively, while Consumer Staples also declined modestly.
Overall, the session showed broad short-term market strength led by Financials, Consumer Discretionary and Technology. The next important consideration is whether these gains translate into sustained relative-momentum improvement and whether the weaker Energy and Materials sectors can recover. The reference article similarly uses daily performance alongside RRG positioning to assess whether short-term gains are supported by broader momentum.


 Nov 04, 2026





 Please wait processing your request...