
 CA
 NZ
 UK
 AU
 IND

 US

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Technology (XLK), Health Care (XLV), Consumer Discretionary (XLY) and Energy (XLE) are positioned in the Leading quadrant.
- Communication Services (XLC) is the only sector in the Improving quadrant, indicating a recovering momentum profile.
- Materials (XLB), Financials (XLF), Industrials (XLI), Consumer Staples (XLP), Real Estate (XLRE) and Utilities (XLU) remain in the Lagging quadrant.
- No sector is currently positioned in the Weakening quadrant.
- Sector momentum remains concentrated, with a small group of Leading sectors and a broad group of Lagging sectors.
The latest US sector momentum visualization for 20 August 2026 shows a highly uneven rotation environment. Technology, Health Care, Consumer Discretionary and Energy remain in the Leading quadrant, while Communication Services is positioned in Improving. Six sectors remain in Lagging, indicating that momentum Leadership has yet to broaden meaningfully.
Momentum Breakdown by Sector
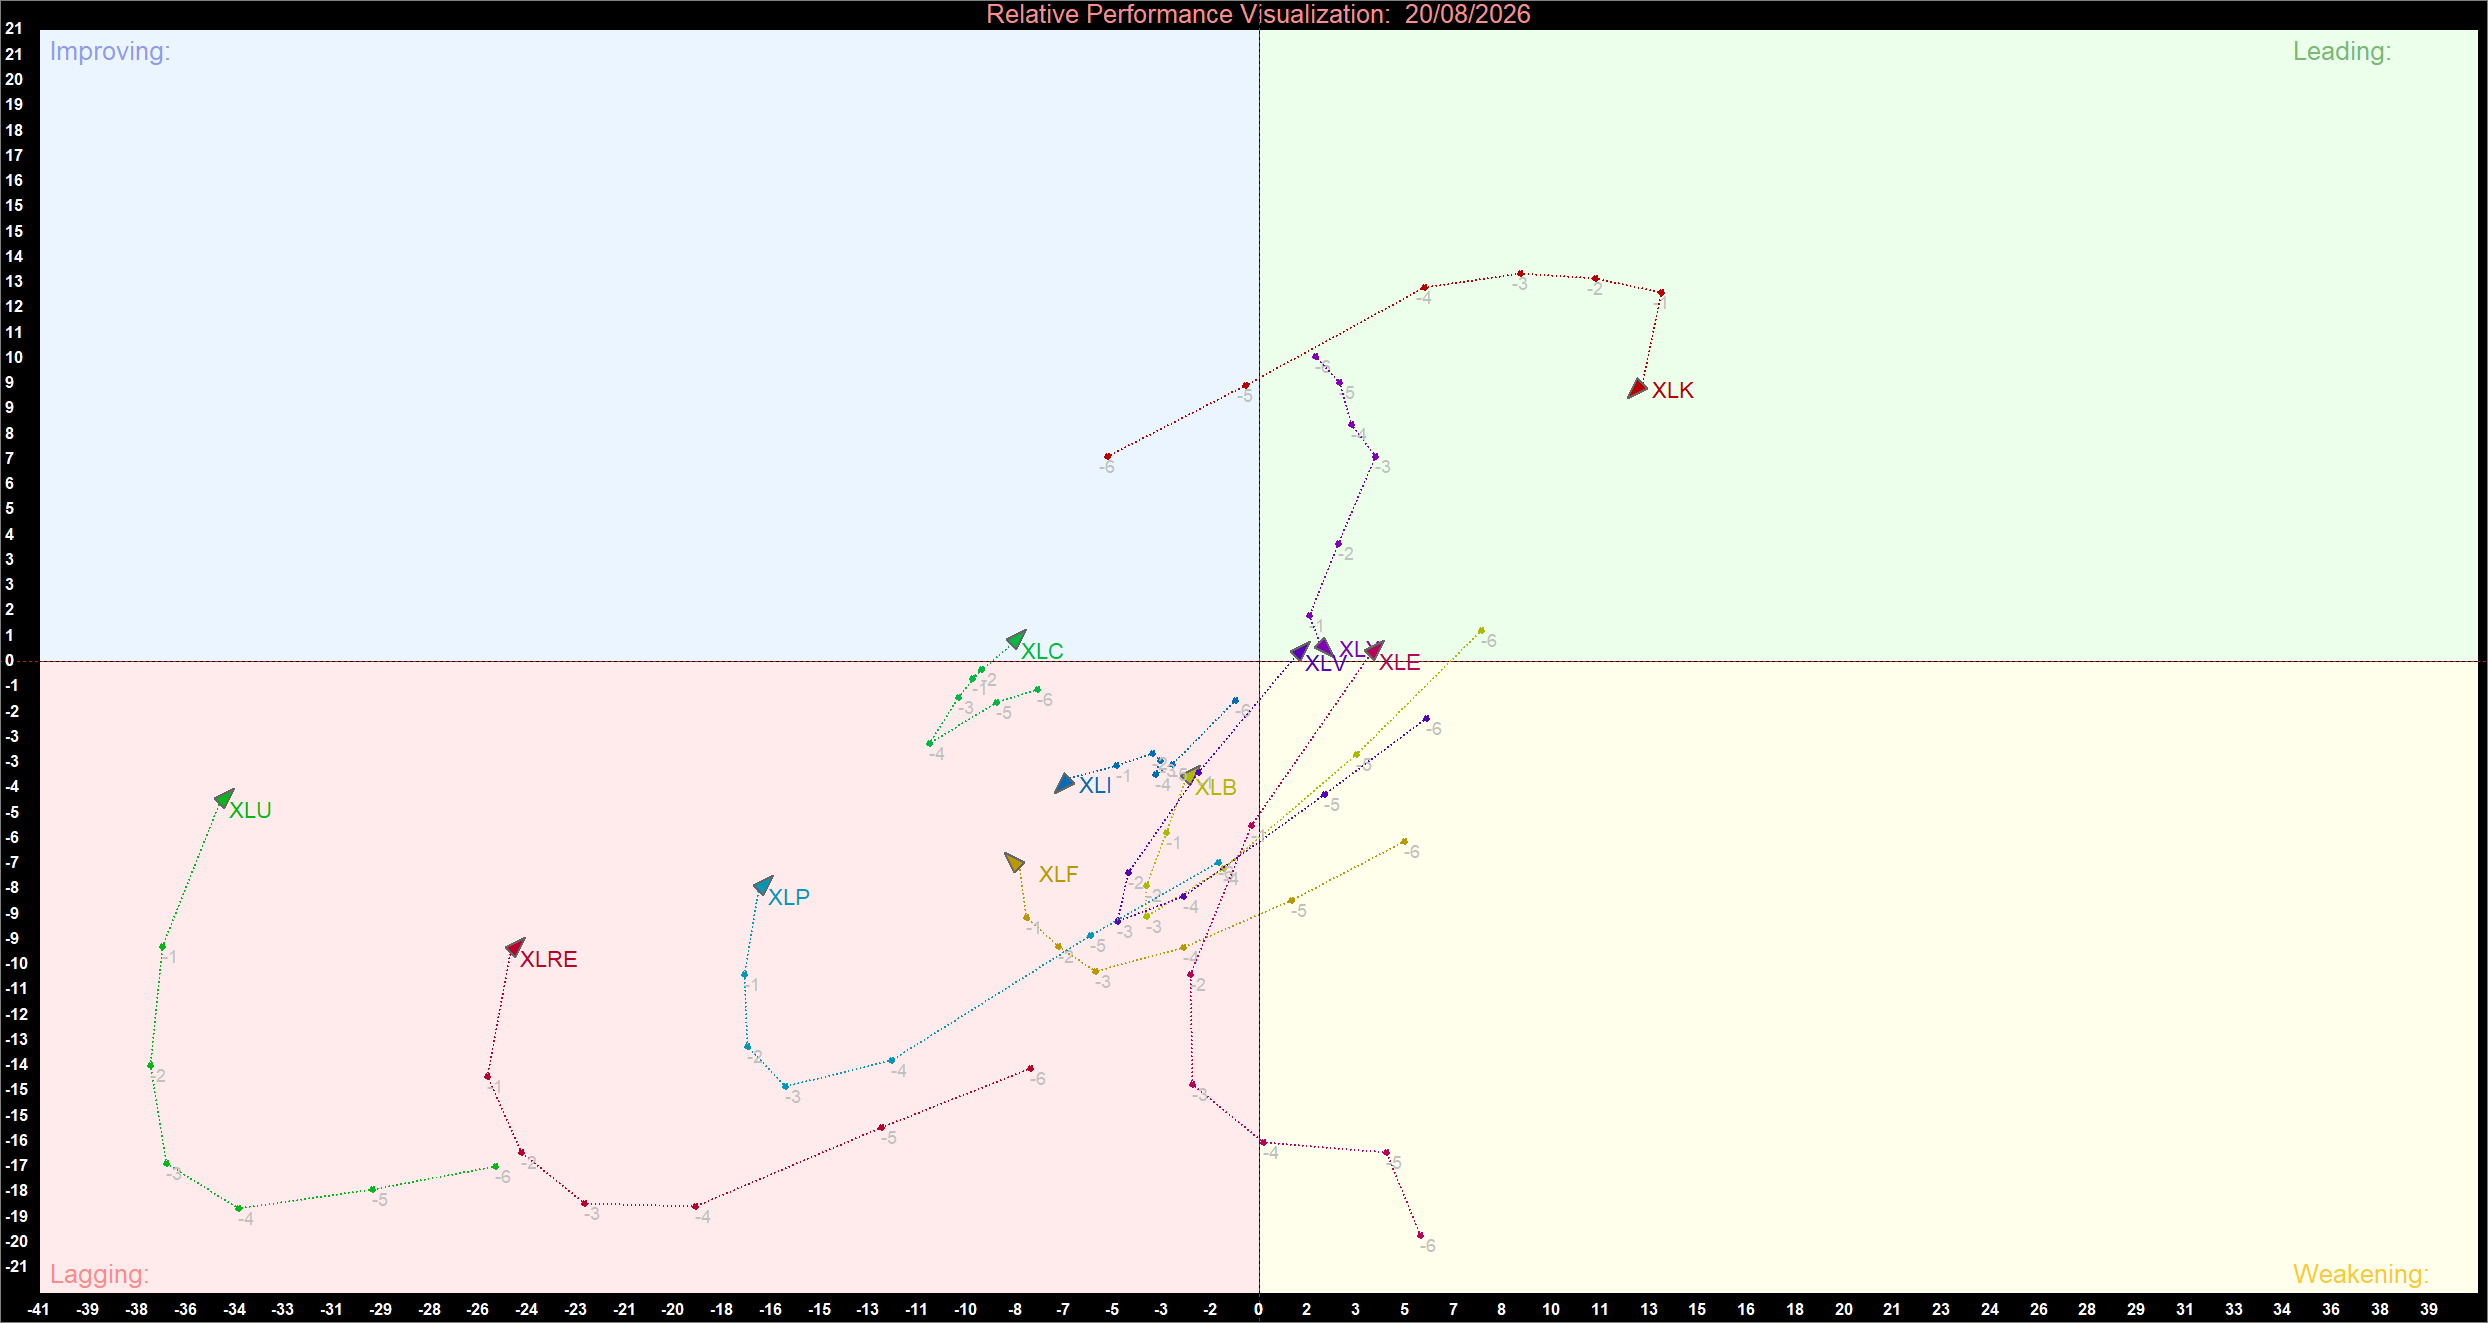
US Sector Relative Momentum Chart (at the closing price of 20/08/2026). Powered by: amibroker.com.
Leading: Technology, Health Care, Consumer Discretionary and Energy
Technology (XLK) remains in the Leading quadrant and continues to display strong relative momentum. Its position places it among the dominant sectors within the current rotation structure.
Health Care (XLV) is also positioned in Leading, indicating that its relative momentum remains strong. Consumer Discretionary (XLY) similarly maintains a Leading position, reinforcing its status as one of the stronger areas of the market.
Energy (XLE) completes the Leading group. Its position indicates strong relative momentum and keeps the sector among the primary areas of market leadership.
Improving: Communication Services
Communication Services (XLC) is the only sector positioned in the Improving quadrant. This indicates that its momentum profile is recovering and moving toward stronger relative positioning.
A continued improvement in its trajectory could eventually move XLC into the Leading quadrant. Conversely, a deterioration in momentum could return the sector toward Lagging.
Lagging: Materials, Financials and Industrials
Materials (XLB), Financials (XLF) and Industrials (XLI) remain in the Lagging quadrant, indicating weaker relative momentum.
Industrials remains among the weaker momentum areas, while Financials and Materials have yet to generate sufficient relative strength to transition into Improving.
Lagging: Consumer Staples, Real Estate and Utilities
Consumer Staples (XLP), Real Estate (XLRE) and Utilities (XLU) also remain in Lagging. Their positions indicate that relative momentum continues to be weaker compared with the current Leading sectors.
The continued Lagging classification across these sectors suggests that defensive and rate-sensitive areas have not yet established enough momentum to challenge the current leaders.
Strategic Summary
The latest US sector momentum analysis shows a concentrated leadership structure. Technology, Health Care, Consumer Discretionary and Energy remain in Leading, while Communication Services is the only sector showing an Improving momentum profile.
Materials, Financials, Industrials, Consumer Staples, Real Estate and Utilities remain in Lagging, while no sector is currently positioned in Weakening.
Overall, sector momentum remains selective. A sustained move by Communication Services and the Lagging sectors toward Improving would provide stronger evidence of broader momentum expansion, while continued Leading positions for XLK, XLV, XLY and XLE would reinforce their status as the dominant momentum sectors.


 Nov 04, 2026





 Please wait processing your request...